Tag: business protection

  • How to Choose Commercial Vehicle Insurance Online: A Comprehensive Guide

    How to Choose Commercial Vehicle Insurance Online: A Comprehensive Guide

    Understanding Commercial Vehicle Insurance Coverage

    How to choose commercial vehicle insurance online – Understanding commercial vehicle insurance coverage is crucial for protecting your business and its assets. Various types of coverage are available, each designed to address specific risks and provide financial protection.

    It’s essential to comprehend the coverage limits and deductibles associated with each policy. Coverage limits determine the maximum amount the insurer will pay for a covered claim, while deductibles represent the amount you pay out-of-pocket before the insurance coverage kicks in.

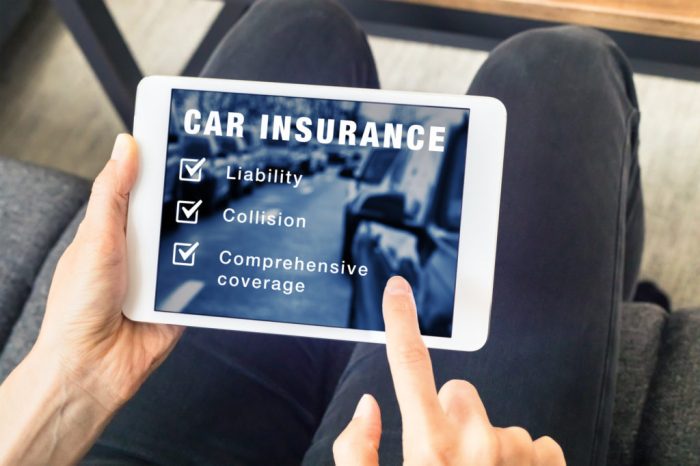
    Liability Coverage

    Liability coverage protects your business from financial responsibility if your commercial vehicle causes bodily injury or property damage to others. It covers expenses such as medical bills, legal fees, and repair costs.

    Collision Coverage

    Collision coverage provides financial protection for damage to your commercial vehicle resulting from a collision with another vehicle or object. It covers repairs or replacement of your vehicle, up to the policy’s coverage limits.

    Comprehensive Coverage

    Comprehensive coverage offers protection against non-collision-related damages or losses, such as theft, vandalism, fire, or natural disasters. It provides financial reimbursement for the repair or replacement of your commercial vehicle, subject to the policy’s coverage limits.

    Comparing Quotes from Multiple Insurers: How To Choose Commercial Vehicle Insurance Online
    How to choose commercial vehicle insurance online

    Obtaining quotes from various insurance companies is crucial for finding the most suitable and cost-effective commercial vehicle insurance policy. To begin, gather necessary information about your business, vehicles, and drivers, as these details will be required by insurers.

    Once you have this information, you can start reaching out to insurance providers. You can request quotes online, over the phone, or through an insurance broker. When comparing quotes, pay attention to the following factors:

    Coverage, How to choose commercial vehicle insurance online

    • Ensure that the coverage provided by each policy meets your specific business needs.
    • Consider the types of risks you face and the level of protection required.
    • Review the policy’s exclusions and limitations carefully.

    Cost

    • Compare the premiums and deductibles offered by different insurers.
    • Consider the long-term cost of the policy, including potential premium increases.
    • Inquire about discounts and payment options to reduce the cost.

    Reputation

    • Research the reputation of each insurance company.
    • Read online reviews and consult with industry experts.
    • Consider the company’s financial stability and claims handling process.

    Negotiating

    • Once you have compared quotes, negotiate with insurance companies to secure the best deal.
    • Explain your business’s risk profile and safety measures to demonstrate your insurability.
    • Be prepared to provide additional documentation or references to support your request.

    Evaluating Insurance Company Reputation and Financial Stability
    Insurance car policy keys desk quoteinspector small options description kb px 1920 1280 original

    When choosing commercial vehicle insurance online, it’s crucial to select an insurance company with a strong reputation and financial stability. A reputable insurer provides peace of mind knowing that your business is protected in the event of an accident or claim.

    Researching Insurance Companies

    Before purchasing a policy, thoroughly research insurance companies. Check industry ratings from organizations like AM Best, Standard & Poor’s, and Moody’s. These ratings provide insights into the company’s financial strength and claims-paying ability. Additionally, read customer reviews on platforms like Trustpilot and Google My Business to gauge the company’s customer service and claims-handling process.

    Assessing Claims-Handling Process and Customer Service

    An efficient claims-handling process is essential. Look for companies that have a dedicated claims department and offer 24/7 claims reporting. Inquire about the average claim settlement time and read reviews to understand how the company handles disputes. Furthermore, consider the company’s customer service.

    Ensure they have responsive and knowledgeable representatives who can assist you with questions or concerns promptly.

    Customizing Your Coverage to Meet Specific Needs
    How to choose commercial vehicle insurance online

    Commercial vehicle insurance policies are not one-size-fits-all. To ensure your business is adequately protected, you need to customize your coverage to meet your specific needs. This can be done by adding endorsements or riders to your policy.

    Endorsements and riders are additional coverages that can be added to your policy to provide specific protection. For example, you can add an endorsement for:

    • Increased liability limits
    • Collision and comprehensive coverage
    • Uninsured/underinsured motorist coverage
    • Towing and labor coverage

    The cost of your policy will increase as you add more endorsements or riders. However, it is important to remember that the additional coverage can protect your business from financial losses in the event of an accident.

    Determining Which Additional Coverages Are Necessary

    The best way to determine which additional coverages are necessary for your business is to talk to your insurance agent. They can help you assess your risks and recommend the right coverage for your needs.

    Here are some factors to consider when determining which additional coverages are necessary:

    • The type of business you operate
    • The number of vehicles you own
    • The value of your vehicles
    • The frequency with which you use your vehicles
    • The areas in which you operate your vehicles

    By considering these factors, you can make sure that you have the right coverage in place to protect your business from financial losses.

    Examples of How Customized Coverage Can Protect Your Business

    Here are some examples of how customized coverage can protect your business from financial losses:

    • If you have a commercial vehicle that is used to transport goods, you may want to add an endorsement for increased liability limits. This will protect you in the event that you are involved in an accident and someone is injured or killed.

    • If you have a commercial vehicle that is used to transport passengers, you may want to add an endorsement for uninsured/underinsured motorist coverage. This will protect you in the event that you are involved in an accident with a driver who does not have insurance or who has insufficient insurance.

    • If you have a commercial vehicle that is used to tow other vehicles, you may want to add an endorsement for towing and labor coverage. This will protect you in the event that your tow truck is involved in an accident or if you need to tow a vehicle.

    By customizing your commercial vehicle insurance coverage, you can make sure that your business is protected from financial losses in the event of an accident.

    Managing Your Insurance Policy and Renewals

    Regularly reviewing your commercial vehicle insurance policy is crucial to ensure it meets your evolving business needs. As your business grows and changes, so should your insurance coverage. Make adjustments to your policy limits, deductibles, and coverage options to align with your current risk profile and financial situation.

    To avoid lapses in coverage, mark your calendar for the policy renewal date. Begin the renewal process well in advance to gather quotes from multiple insurers and compare coverage options. This allows ample time to secure the best coverage at a competitive price.

    Keeping Your Insurance Costs Down

    • Maintain a clean driving record: Avoid traffic violations and accidents to demonstrate responsible driving habits.
    • Take advantage of discounts: Ask your insurer about available discounts, such as multi-vehicle policies, loyalty discounts, and safety features installed on your vehicles.
    • Increase your deductible: Consider raising your deductible to lower your premiums. However, ensure you choose a deductible that you can comfortably afford to pay in the event of a claim.
    • Shop around for quotes: Regularly compare quotes from multiple insurers to find the best coverage and rates.

    FAQ Corner

    What factors should I consider when comparing commercial vehicle insurance quotes?

    When comparing quotes, consider coverage options, cost, deductibles, policy limits, reputation of the insurance company, and customer service.

    How can I customize my commercial vehicle insurance coverage?

    You can add endorsements or riders to your policy to cover specific needs, such as hired and non-owned auto liability, cargo insurance, or roadside assistance.

    What is the importance of understanding coverage limits and deductibles?

    Coverage limits determine the maximum amount the insurance company will pay for a covered loss, while deductibles represent the amount you pay out of pocket before insurance coverage kicks in.

  • Small Business Insurance Agents Near Me: Protect Your Enterprise

    Small Business Insurance Agents Near Me: Protect Your Enterprise

    Small business insurance agents near me: your local experts in safeguarding your enterprise. In today’s competitive market, protecting your business from unexpected events is paramount. Our comprehensive guide connects you with reputable agents who understand the unique risks and needs of small businesses, ensuring you have the coverage you need to thrive.

    With a focus on local listings, customer testimonials, and industry expertise, this guide empowers you to make informed decisions about your insurance needs. Discover the latest technological advancements and innovative solutions that streamline the insurance process, enhancing customer service and reducing costs.

    Local Business Listings

    Finding a reliable small business insurance agent in your local area is essential for protecting your business from financial risks. To help you find the best agent for your needs, we’ve compiled a comprehensive list of local agents, including their contact information and service offerings.

    Our interactive HTML table below provides an easy way to compare and choose the right agent for your business. Simply click on the column headers to sort the results by agent name, address, phone number, or website.

    Agent Listings

    Agent Name Address Phone Number Website
    [Agent Name 1] [Address 1] [Phone Number 1] [Website 1]
    [Agent Name 2] [Address 2] [Phone Number 2] [Website 2]
    [Agent Name 3] [Address 3] [Phone Number 3] [Website 3]

    Customer Reviews and Testimonials

    Chesterfield rates markham lv expensive update millennial insurer

    Establish credibility and trustworthiness by showcasing genuine customer reviews and testimonials that attest to the reliability and expertise of the recommended insurance agents.

    Present the reviews in an organized and visually appealing manner, using bullet points or blockquotes, to highlight key aspects of customer satisfaction.

    Positive Feedback

    • “I highly recommend this agent. They were extremely knowledgeable and helpful in finding the right insurance coverage for my business.”
    • “The agent was very responsive and went above and beyond to ensure I understood the policy and my coverage options.”
    • “I have been a client for several years and have always been impressed with the agent’s professionalism and dedication to providing excellent customer service.”

    Personalized Service

    • “The agent took the time to understand my specific business needs and tailored the coverage to fit my requirements.”
    • “I felt like I was working with a trusted advisor who genuinely cared about my business’s well-being.”
    • “The agent was proactive in reaching out to me to review my coverage and make sure it was up to date.”

    Insurance Coverage Options

    Small business insurance agents near me

    Small businesses face unique risks and liabilities, making it crucial to secure comprehensive insurance coverage. Different types of insurance policies provide varying levels of protection, catering to specific business needs.

    General Liability Insurance

    General liability insurance protects businesses against claims of bodily injury, property damage, or personal injury caused by their operations, products, or services. It covers legal defense costs and damages awarded to the injured party.

    Property Insurance

    Property insurance safeguards a business’s physical assets, such as buildings, equipment, inventory, and business records. It covers losses or damages due to fire, theft, vandalism, natural disasters, and other covered perils.

    Workers’ Compensation Insurance

    Workers’ compensation insurance provides coverage for employees who suffer work-related injuries or illnesses. It covers medical expenses, lost wages, and disability benefits, protecting both the employee and the business from financial burdens.

    Comparison of Coverage Options

    The table below compares the key features of general liability, property, and workers’ compensation insurance:

    Coverage Type Coverage Scope Premiums Deductibles
    General Liability Bodily injury, property damage, personal injury Varies based on risk factors Typically low
    Property Physical assets, business records Based on value of property insured Can vary significantly
    Workers’ Compensation Work-related injuries or illnesses Set by state regulations Often not applicable

    When choosing insurance coverage, it’s essential to consider the specific risks and exposures of your business. Consulting with an experienced insurance agent can help you tailor a coverage plan that meets your unique needs and provides comprehensive protection.

    Industry Expertise and Specialization

    Small business insurance agents near me

    When choosing a small business insurance agent, consider their expertise and specialization in specific industries. Agents who have a deep understanding of your industry’s unique risks and needs can provide tailored solutions that protect your business effectively.

    For example, if you own a healthcare practice, an agent specializing in healthcare insurance can guide you through the complexities of medical malpractice coverage, HIPAA compliance, and patient privacy regulations.

    Construction Industry

    • Agents specializing in construction insurance understand the risks associated with construction projects, including property damage, liability, and workers’ compensation.
    • They can help you navigate the complex insurance requirements for different types of construction projects, such as residential, commercial, and infrastructure.

    Retail Industry

    • Agents specializing in retail insurance understand the risks faced by businesses operating in the retail sector, such as theft, property damage, and product liability.
    • They can help you develop a comprehensive insurance program that protects your inventory, equipment, and employees.

    Benefits of Working with an Industry Specialist

    • Customized coverage: Agents with industry expertise can tailor insurance policies to meet the specific risks and needs of your business.
    • Proactive risk management: They can identify potential risks and develop strategies to mitigate them, reducing the likelihood of costly claims.
    • Efficient claims handling: Agents who understand your industry can help you navigate the claims process smoothly and efficiently, ensuring timely settlement.

    Technology and Innovation: Small Business Insurance Agents Near Me

    The small business insurance industry is embracing technology and innovation to improve efficiency, enhance customer service, and reduce costs. Agents are leveraging cutting-edge tools to streamline the quoting and policy management process, providing a seamless experience for their clients.

    Digital Quoting and Policy Management

    Digital quoting platforms enable agents to quickly and accurately generate quotes for small businesses. These platforms integrate with insurance carriers’ systems, allowing agents to access real-time data and provide tailored recommendations. Automated underwriting processes reduce the time and effort required to issue policies, ensuring a faster turnaround time for clients.

    Customer Relationship Management (CRM) Systems, Small business insurance agents near me

    CRM systems help agents manage customer relationships and provide personalized service. These systems store customer data, track interactions, and generate automated reminders for renewals and other important events. By leveraging CRM systems, agents can nurture relationships with their clients and provide proactive support.

    Data Analytics and Artificial Intelligence (AI)

    Data analytics and AI are transforming the insurance industry. Agents are using data to identify trends, predict risks, and develop customized insurance solutions for their clients. AI-powered chatbots and virtual assistants provide 24/7 support, answering customer questions and resolving issues quickly and efficiently.

    Last Point

    Partnering with a small business insurance agent near you provides invaluable peace of mind, allowing you to focus on growing your business while knowing that your assets and operations are protected. Embrace the insights and recommendations in this guide to secure the insurance coverage that empowers your business to succeed.

    Helpful Answers

    How can I find the best small business insurance agent near me?

    Our guide provides a comprehensive list of reputable agents in your area, along with their contact information and service offerings.

    What types of insurance coverage do small businesses need?

    Small businesses typically require general liability, property insurance, and workers’ compensation coverage. Our guide compares the coverage options, premiums, and deductibles offered by different agents.

    How can technology benefit my small business insurance experience?

    Agents are leveraging technology to streamline the quoting and policy management process, enhance customer service, and reduce costs. Our guide explores these advancements and their impact on the industry.

  • Small Business Professional Insurance: Protecting Your Livelihood and Legacy

    Small Business Professional Insurance: Protecting Your Livelihood and Legacy

    Small business professional insurance, a safety net for the visionaries and risk-takers who drive our economy, is an intricate tapestry of coverage options, risk management strategies, and legal compliance. Dive into this comprehensive guide to safeguard your business and dreams.

    Navigating the complexities of insurance can be daunting, but we’re here to break down the jargon and empower you with knowledge. From general liability to professional negligence, property protection to business interruption, we’ll explore the insurance landscape tailored specifically for small business professionals.

    Coverage Options

    Small business professional insurance

    Small business professionals face a wide range of risks that can impact their operations and financial well-being. Comprehensive insurance coverage is essential to mitigate these risks and protect their businesses.

    Various types of insurance coverage are available, each designed to address specific needs and provide protection against different types of losses. Understanding the different options and selecting the appropriate coverage is crucial for small business professionals.

    General Liability Insurance, Small business professional insurance

    General liability insurance protects businesses against claims of bodily injury, property damage, or personal injury caused by their operations, products, or services. It covers legal expenses, settlements, and judgments arising from third-party claims, such as:

    • Customer injuries on business premises
    • Product defects causing harm
    • Professional negligence

    Professional Liability Insurance

    Professional liability insurance, also known as errors and omissions (E&O) insurance, protects businesses against claims of negligence, errors, or omissions in their professional services. It covers legal expenses, settlements, and judgments arising from claims that the business failed to meet the expected standard of care in providing its services, such as:

    • Mistakes in professional advice
    • Breach of contract
    • Intellectual property infringement

    Property Insurance

    Property insurance protects businesses against physical damage or loss to their property, such as buildings, equipment, inventory, and other assets. It covers losses due to events like fire, theft, vandalism, natural disasters, and other covered perils, such as:

    • Building damage from a storm
    • Theft of office equipment
    • Fire damage to inventory

    Business Interruption Insurance

    Business interruption insurance provides coverage for lost income and expenses incurred when a business is unable to operate due to a covered event, such as a natural disaster, fire, or equipment failure. It helps businesses maintain financial stability during periods of disruption, such as:

    • Loss of revenue due to a hurricane
    • Closure due to a fire
    • Downtime caused by a cyberattack

    Risk Assessment and Mitigation

    Small business professional insurance

    Risk assessment is a crucial step for small businesses to identify and understand potential threats that can jeopardize their operations. By conducting a thorough risk assessment, businesses can proactively mitigate risks and safeguard their assets, reputation, and financial stability.

    Effective risk mitigation strategies involve implementing safety protocols, training employees, and maintaining proper documentation. These measures help businesses minimize the likelihood and impact of potential incidents, ensuring a safer and more secure work environment.

    Risk Assessment

    • Identify potential risks:Conduct a comprehensive review of operations, processes, and assets to pinpoint areas vulnerable to threats such as accidents, data breaches, or natural disasters.
    • Assess risk severity and likelihood:Evaluate the potential impact and probability of identified risks, prioritizing those that pose the greatest threat to the business.
    • Develop risk mitigation plans:Create specific plans outlining actions to reduce or eliminate identified risks, including emergency response protocols, cybersecurity measures, and employee safety training.

    Risk Mitigation

    • Implement safety protocols:Establish clear safety guidelines, conduct regular inspections, and provide necessary safety equipment to prevent accidents and protect employees.
    • Train employees:Educate employees on identified risks and their roles in risk mitigation, empowering them to make informed decisions and respond effectively to potential threats.
    • Maintain proper documentation:Keep accurate records of risk assessments, mitigation plans, and incident reports to demonstrate compliance and provide evidence for insurance claims if necessary.

    Claims Process

    Liability scenarios

    Filing an insurance claim for small business professionals is a crucial process that can help mitigate financial losses and ensure business continuity. Here’s a detailed overview of the steps involved:

    When a covered event occurs, it’s essential to promptly notify your insurance company. Most policies require you to report claims within a specific timeframe, usually within 30-60 days. You can initiate the claim process by calling your insurance provider or submitting a claim online.

    Documenting Your Claim

    To support your claim, you will need to provide comprehensive documentation. This may include:

    • A detailed description of the incident, including the date, time, and location
    • Photographs or videos of the damage or loss
    • Receipts and invoices for any expenses incurred due to the incident
    • Contact information for witnesses or other parties involved

    Timelines and Processing

    The claims processing timeline can vary depending on the complexity of the claim and the insurance company’s procedures. Generally, you can expect the following steps:

    1. Initial Review:The insurance company will review your claim and request any additional documentation needed.
    2. Investigation:An adjuster may be assigned to investigate the claim and assess the extent of the damage or loss.
    3. Settlement Offer:Once the investigation is complete, the insurance company will make a settlement offer based on the policy coverage and the evidence provided.
    4. Negotiation and Approval:You can negotiate the settlement offer with the insurance company if you believe it is inadequate. Once an agreement is reached, the claim will be approved.
    5. Payment:The insurance company will issue payment for the approved claim amount.

    Tips for Effective Communication

    To maximize your claim payout and ensure a smooth claims process, consider the following tips:

    • Be clear and concise:Provide accurate and detailed information about the incident and your losses.
    • Document everything:Gather all relevant documentation and keep it organized for easy reference.
    • Stay organized:Maintain a file or folder for all claim-related correspondence and documents.
    • Be patient:Claims processing can take time, so be patient and follow up regularly without being overly demanding.
    • Consider professional help:If you have a complex or high-value claim, consider seeking advice from an insurance attorney or claims adjuster.

    Choosing the Right Insurance Provider: Small Business Professional Insurance

    Selecting the right insurance provider is crucial for small business professionals. Consider these factors:

    Coverage Options:Ensure the provider offers comprehensive coverage tailored to your specific risks.

    Premiums:Compare premiums from multiple providers to find the best value for your budget.

    Customer Service:Look for a provider with a reputation for responsive and helpful customer support.

    Negotiating with Insurance Providers

    Negotiate effectively to secure the best coverage at a competitive price:

    • Shop around:Obtain quotes from several providers to compare coverage and premiums.
    • Bundle policies:Combine multiple policies, such as general liability and professional liability, with the same provider to save money.
    • Increase deductibles:Consider raising your deductibles to lower premiums, but ensure you can afford the higher out-of-pocket costs.
    • Ask for discounts:Inquire about any available discounts, such as those for good safety records or professional certifications.

    Legal and Regulatory Compliance

    Ensuring compliance with legal and regulatory requirements is essential for small business professionals. Maintaining adequate insurance coverage not only protects your business but also fulfills legal obligations and safeguards your financial interests.

    Consequences of Inadequate Insurance

    Failing to maintain adequate insurance can have severe consequences:

    • Financial losses due to uninsured events
    • Legal liability for accidents or injuries
    • Reputational damage
    • Difficulty obtaining financing or contracts

    Compliance with Industry Standards

    To stay compliant, small business professionals should:

    • Understand the specific insurance requirements for their industry
    • Review industry best practices and standards
    • Seek guidance from insurance professionals and legal counsel

    By adhering to these guidelines, small business professionals can ensure they meet their legal and regulatory obligations, protect their assets, and maintain their business’s reputation and financial stability.

    Final Wrap-Up

    As you navigate the ever-changing business landscape, small business professional insurance stands as a beacon of protection, ensuring your enterprise weathers the storms and seizes opportunities. By understanding your risks, selecting the right coverage, and staying compliant, you’re not just safeguarding your business; you’re investing in its future success.

    General Inquiries

    What types of coverage does small business professional insurance offer?

    Small business professional insurance typically includes coverage for general liability, professional liability, property damage, business interruption, and employee-related risks.

    How can I assess my business’s risks?

    Conduct a thorough risk assessment by identifying potential hazards, evaluating their likelihood and impact, and implementing measures to mitigate them.

    What are the key factors to consider when choosing an insurance provider?

    Compare coverage options, premiums, customer service, financial stability, and industry reputation to select the provider that best meets your needs.

  • Commercial General Liability Insurance: A Safeguard for Small Businesses

    Commercial General Liability Insurance: A Safeguard for Small Businesses

    Commercial general liability insurance for small business – In the realm of small businesses, commercial general liability insurance emerges as an indispensable safeguard, providing a robust shield against unforeseen risks that threaten the stability and reputation of these ventures. This comprehensive coverage extends its protective umbrella over a wide spectrum of potential perils, empowering small businesses to navigate the complexities of the business landscape with confidence.

    As we delve into the intricacies of commercial general liability insurance, we will uncover its multifaceted nature, exploring the types of risks it covers, the factors that influence its cost, and the strategies for managing claims effectively. By illuminating the path towards tailored insurance solutions, this discourse aims to empower small business owners with the knowledge and tools they need to protect their enterprises and thrive in an ever-evolving marketplace.

    Understanding Commercial General Liability Insurance (CGL) for Small Businesses

    Commercial General Liability (CGL) insurance is an essential coverage for small businesses. It provides protection against financial losses resulting from third-party claims of bodily injury, property damage, or advertising injury. By understanding the purpose, coverage, and risks covered by CGL insurance, small businesses can safeguard their operations and minimize potential liabilities.

    Types of Risks Covered by CGL Insurance

    CGL insurance covers a wide range of risks that can arise in the course of a small business’s operations. These risks include:

    • Bodily injury:Claims for injuries sustained by third parties due to the business’s negligence or products.
    • Property damage:Claims for damage to third-party property caused by the business’s operations or products.
    • Advertising injury:Claims for damages resulting from the business’s advertising, such as libel, slander, or copyright infringement.

    Common Claims Covered by CGL Insurance

    CGL insurance covers a variety of common claims that small businesses may face. These claims include:

    • Customer injuries on business premises
    • Damage to customer property during service or delivery
    • Accusations of false advertising or defamation
    • Legal expenses associated with defending against third-party claims

    Assessing Your Business’s CGL Insurance Needs

    Liability

    Assessing your business’s commercial general liability (CGL) insurance needs is crucial for protecting your company against potential risks and financial losses. Here’s a comprehensive guide to help you determine the appropriate coverage limits and identify potential gaps in your insurance plan.

    Factors to Consider

    • Size of the Business:Larger businesses with more employees and operations typically require higher coverage limits.
    • Industry:Different industries pose varying levels of risk. For example, businesses involved in construction or manufacturing may need more coverage than office-based businesses.
    • Location:The location of your business can influence insurance rates due to factors such as crime rates and natural disaster risks.
    • Potential Risks:Identify specific risks associated with your business operations, such as customer injuries, property damage, or professional negligence.
    • Existing Insurance Coverage:Review your current insurance policies to identify any overlaps or gaps in coverage.

    Tips for Identifying Potential Risks and Gaps in Coverage

    To ensure adequate protection, consider the following tips:

    • Conduct a Risk Assessment:Thoroughly evaluate your business operations to identify potential risks and vulnerabilities.
    • Review Industry Benchmarks:Compare your insurance coverage with industry standards to ensure you’re adequately protected.
    • Consult with an Insurance Broker:An experienced insurance broker can provide valuable insights and help you tailor your CGL insurance plan to meet your specific needs.

    Comparing and Selecting CGL Insurance Policies

    Commercial general liability insurance for small business

    Selecting the most appropriate CGL insurance policy for your small business is crucial. It entails a thorough evaluation of various policies, considering factors such as coverage limits, deductibles, and exclusions. The following table compares different CGL insurance policies from multiple providers to assist you in making an informed decision.

    Policy Comparison Table

    Provider Coverage Limits Deductibles Exclusions
    Provider A $1,000,000 per occurrence/$2,000,000 aggregate $500 Pollution, intentional acts, and workers’ compensation
    Provider B $2,000,000 per occurrence/$4,000,000 aggregate $1,000 Cybersecurity breaches, professional negligence, and contractual liability
    Provider C $500,000 per occurrence/$1,000,000 aggregate $250 Product liability, bodily injury to employees, and property damage to owned property

    Evaluating and Selecting a Policy

    To select the most suitable policy, consider the following:

    • Coverage Limits:Ensure the policy provides adequate coverage for potential liabilities.
    • Deductibles:Choose a deductible that balances affordability with financial protection.
    • Exclusions:Carefully review exclusions to identify potential gaps in coverage.
    • Reputation and Financial Stability:Select a reputable insurer with a strong financial track record.
    • Customer Service:Consider the insurer’s responsiveness and support in case of a claim.

    Managing CGL Insurance Costs

    Commercial general liability insurance for small business

    Managing the costs of commercial general liability (CGL) insurance is crucial for small businesses. Understanding the factors that influence premiums and implementing strategies to reduce expenses can help businesses maintain adequate coverage without breaking the bank.

    Several key factors impact CGL insurance costs:

    Deductibles

    • Deductibles represent the amount a business pays out-of-pocket before insurance coverage kicks in.
    • Higher deductibles generally result in lower premiums.
    • Businesses should consider their financial capabilities and risk tolerance when selecting a deductible.

    Policy Limits

    • Policy limits determine the maximum amount an insurer will pay for covered claims.
    • Higher policy limits increase premiums.
    • Businesses should carefully assess their potential risks and choose limits that provide adequate protection.

    Claims History

    • A business’s claims history can significantly affect its insurance premiums.
    • Businesses with a history of frequent or severe claims may face higher premiums.
    • Maintaining a good claims history can help keep premiums low.

    In addition to these factors, businesses can consider the following strategies to manage CGL insurance costs:

    Negotiating with Insurance Providers

    • Negotiating with insurance providers can help secure better rates and terms.
    • Businesses should compare quotes from multiple insurers and be prepared to provide supporting documentation to justify their request for lower premiums.
    • Building a strong relationship with an insurance broker can also facilitate negotiations.

    Exploring Discounts, Commercial general liability insurance for small business

    • Many insurance providers offer discounts for certain safety measures or risk management practices.
    • Businesses should inquire about available discounts and implement measures to qualify for them.
    • Common discounts include those for installing security systems, conducting safety training, and maintaining good credit.

    By understanding the factors that influence CGL insurance costs and implementing strategies to manage them, small businesses can effectively protect their operations while minimizing expenses.

    Filing and Managing CGL Insurance Claims

    Filing and managing a CGL insurance claim can be a complex process, but it’s essential to understand the steps involved to ensure your claim is processed efficiently and fairly. This section will guide you through the process, including the documentation required, the steps for submitting a claim, and tips for managing the claims process.

    Documenting Your Claim

    When you file a CGL insurance claim, you will need to provide detailed documentation to support your request. This documentation may include:

    • A copy of your CGL insurance policy
    • A description of the incident that led to the claim
    • Documentation of the damages or injuries sustained
    • Contact information for any witnesses or other parties involved
    • Medical records or other documentation of expenses incurred as a result of the incident

    Submitting Your Claim

    Once you have gathered the necessary documentation, you can submit your claim to your insurance company. You can typically do this online, by mail, or over the phone. Be sure to provide all of the required information and documentation, and keep a copy of your claim for your records.

    Managing the Claims Process

    Once you have submitted your claim, the insurance company will begin investigating the incident. This may involve contacting you for additional information, reviewing your documentation, and conducting an inspection of the damaged property. It’s important to cooperate with the insurance company throughout the claims process and provide them with any information they request.

    If the insurance company approves your claim, they will issue a payment to cover the damages or injuries sustained. However, it’s important to note that the insurance company may also negotiate with you to settle the claim for a lower amount.

    It’s important to carefully consider any settlement offers and to consult with an attorney if you have any questions about the settlement process.

    Summary: Commercial General Liability Insurance For Small Business

    In conclusion, commercial general liability insurance serves as a cornerstone of risk management for small businesses, safeguarding them from a multitude of potential liabilities. By understanding the coverage it provides, assessing their unique needs, and selecting a policy that aligns with their specific requirements, small business owners can mitigate risks, protect their assets, and foster a climate of growth and prosperity.

    As they navigate the complexities of the business world, this invaluable insurance tool empowers them to operate with confidence, knowing that they are shielded from unforeseen events that could jeopardize their endeavors.

    Q&A

    What are the key types of risks covered by commercial general liability insurance?

    Commercial general liability insurance typically covers three main types of risks: bodily injury, property damage, and advertising injury. Bodily injury coverage protects against claims arising from physical harm to others, while property damage coverage provides protection against claims for damage to the property of others.

    Advertising injury coverage, on the other hand, safeguards against claims for libel, slander, or copyright infringement.

    How can small businesses determine the appropriate coverage limits for their commercial general liability insurance?

    To determine the appropriate coverage limits for commercial general liability insurance, small businesses should consider factors such as the size of their business, the industry they operate in, and their location. The potential risks associated with their operations and the value of their assets should also be taken into account.

    It is advisable to consult with an insurance professional to assess individual needs and tailor the coverage accordingly.

    What are some strategies for managing the costs of commercial general liability insurance?

    There are several strategies that small businesses can employ to manage the costs of commercial general liability insurance. These include increasing their deductible, bundling their insurance policies, and maintaining a good claims history. Additionally, exploring discounts and negotiating with insurance providers can also help reduce premiums.

  • Small Business Indemnity Insurance: A Lifeline for Entrepreneurs

    Small Business Indemnity Insurance: A Lifeline for Entrepreneurs

    Small business indemnity insurance stands as a guardian angel for entrepreneurs, safeguarding them against financial pitfalls and legal woes. It’s a safety net that provides peace of mind, allowing businesses to thrive amidst unforeseen circumstances.

    This insurance policy extends its protective shield over a wide spectrum of risks, including bodily injury, property damage, and financial losses. It empowers businesses to navigate the complexities of liability claims, ensuring they can continue their operations without facing financial ruin.

    Coverage Overview

    Small business indemnity insurance serves as a protective shield for your enterprise, safeguarding it against a spectrum of financial liabilities and risks. It encompasses coverage for bodily injuries sustained by individuals on your premises, damage to property belonging to others, and financial losses incurred due to negligence or errors.

    This insurance policy acts as a safety net, ensuring that your business remains financially stable even in the face of unforeseen events. It empowers you to focus on growing your venture without the burden of excessive financial concerns.

    Covered Risks

    • Bodily Injury:Coverage extends to injuries suffered by individuals on your business premises, regardless of whether they are customers, employees, or visitors.
    • Property Damage:This aspect covers damage caused to the property of others due to your business operations or negligence.
    • Financial Loss:The policy provides protection against financial losses arising from legal liability, such as claims for defamation or copyright infringement.

    Key Features and Benefits

    Small business indemnity insurance

    Small business indemnity insurance is designed to protect businesses from financial liability and legal costs arising from claims made against them. It offers a range of key features and benefits that can provide peace of mind and financial security.

    Indemnity insurance policies typically cover the following:

    Claims Coverage, Small business indemnity insurance

    • Bodily injury or property damage to third parties
    • Legal expenses, including court costs and attorney fees
    • Judgments and settlements awarded against the business

    These policies can also provide:

    Additional Coverage

    • Coverage for employee injuries, even if the business is not at fault
    • Protection against claims arising from products or services provided by the business
    • Coverage for claims made by contractors or subcontractors

    By obtaining small business indemnity insurance, businesses can safeguard their financial well-being and protect themselves from the potentially devastating consequences of lawsuits.

    Eligibility and Exclusions: Small Business Indemnity Insurance

    To qualify for small business indemnity insurance, businesses must meet certain eligibility criteria, including:

    • Being a legally registered business entity.
    • Operating within the policy’s defined business activities.
    • Having a proven track record of financial stability.

    Despite providing broad coverage, indemnity insurance policies typically exclude certain types of claims, such as:

    Common Exclusions

    • Intentional Acts:Damages or injuries caused by deliberate or malicious actions of the business or its employees.
    • Contractual Liabilities:Claims arising from breach of contracts or agreements.
    • Employee Injuries:Injuries sustained by employees while performing their job duties, which are typically covered by workers’ compensation insurance.
    • Property Damage:Physical damage to property owned or leased by the business.
    • Environmental Liability:Claims related to environmental damage or pollution caused by the business’s operations.

    Cost and Premiums

    The cost of small business indemnity insurance premiums is influenced by several factors, including the size of the business, the industry in which it operates, the number of employees, the coverage limits, and the deductible.

    Businesses can minimize their insurance costs by:

    Risk Management

    • Implementing strong risk management practices, such as regular safety inspections and employee training.
    • Maintaining a good claims history.
    • Working with an insurance broker to find the best coverage at the most competitive price.

    Claims Process and Dispute Resolution

    Small business indemnity insurance

    Filing a claim under a small business indemnity insurance policy typically involves the following steps:

    The policyholder must notify the insurer promptly after an incident occurs. This can usually be done by phone, email, or through the insurer’s online portal.

    The insurer will assign a claims adjuster to investigate the claim. The adjuster will gather evidence, interview witnesses, and determine the extent of the loss.

    Once the investigation is complete, the insurer will issue a settlement offer to the policyholder. The policyholder can accept or reject the offer.

    If the policyholder accepts the offer, the insurer will issue payment for the claim.

    If the policyholder rejects the offer, they can appeal the decision through the insurer’s internal dispute resolution process.

    Dispute Resolution

    If the policyholder is not satisfied with the insurer’s decision, they can appeal the decision through the insurer’s internal dispute resolution process.

    The internal dispute resolution process typically involves the following steps:

    1. The policyholder must submit a written appeal to the insurer.
    2. The insurer will review the appeal and make a decision.
    3. If the policyholder is still not satisfied with the decision, they can file a complaint with the state insurance commissioner.

    Concluding Remarks

    Business indemnity insurance

    In the ever-evolving business landscape, small business indemnity insurance emerges as a beacon of stability. It empowers entrepreneurs to take calculated risks, knowing that they have a financial cushion to fall back on. As businesses grow and expand, this insurance policy remains a steadfast companion, providing unwavering support and protection.

    FAQ Insights

    What types of businesses need small business indemnity insurance?

    Any small business that interacts with customers, clients, or the public can benefit from indemnity insurance. It’s particularly crucial for businesses that provide services or products that could potentially lead to bodily injury or property damage.

    How much does small business indemnity insurance cost?

    The cost of indemnity insurance varies depending on factors such as the size of the business, the industry, and the level of coverage required. It’s advisable to obtain quotes from multiple insurance providers to compare rates and find the most cost-effective option.

    What are the exclusions under a small business indemnity insurance policy?

    Common exclusions include intentional acts, criminal activities, and damage caused by pollution. It’s important to carefully review the policy to understand what is and isn’t covered.

  • Professional Liability Insurance Quotes for Small Businesses: A Guide to Coverage, Costs, and Comparison

    Professional Liability Insurance Quotes for Small Businesses: A Guide to Coverage, Costs, and Comparison

    Professional liability insurance quotes small business – Navigating the realm of professional liability insurance quotes for small businesses can be a daunting task, but it’s a crucial step in safeguarding your company’s reputation and financial well-being. Dive into this comprehensive guide to gain insights into the types of coverage available, factors influencing quotes, and strategies for obtaining the best possible rates.

    Understanding professional liability insurance is paramount for small businesses. It acts as a protective shield against claims alleging negligence, errors, or omissions in the services you provide. By investing in this coverage, you mitigate risks, enhance customer trust, and secure your business’s future.

    Coverage and Benefits

    Professional liability insurance quotes small business

    Professional liability insurance, also known as errors and omissions (E&O) insurance, protects small businesses from financial losses resulting from alleged or actual mistakes, errors, or omissions in the performance of their professional services. It provides coverage for claims of negligence, breach of contract, misrepresentation, and other professional liabilities.Having

    professional liability insurance offers numerous benefits for small businesses. It provides peace of mind, knowing that they are financially protected against costly lawsuits. It also enhances their credibility and reputation, demonstrating to clients that they take their professional responsibilities seriously.

    Furthermore, it can help attract and retain clients who are seeking businesses that prioritize professionalism and risk management.Common claims covered by professional liability insurance include:

    • Negligence in the performance of professional services
    • Errors or omissions in advice or recommendations
    • Breach of contract
    • Misrepresentation or misstatement of facts
    • Defamation or libel
    • Intellectual property infringement

    Factors Affecting Quotes

    Professional liability insurance quotes for small businesses are not one-size-fits-all. Several factors influence the cost of coverage, including:

    Business Size

    The larger the business, the higher the potential for claims. Therefore, larger businesses typically pay higher premiums.

    Industry

    Certain industries, such as healthcare and construction, pose higher risks for professional liability claims. As a result, businesses in these industries can expect to pay higher premiums.

    Claims History, Professional liability insurance quotes small business

    Businesses with a history of claims are considered higher risks and will likely pay higher premiums. Even a single claim can significantly increase the cost of coverage.

    Importance of Understanding Your Risk Profile

    Before getting quotes, it’s essential to understand your business’s risk profile. This includes identifying potential risks and taking steps to mitigate them. By understanding your risk profile, you can provide insurers with a clearer picture of your business and potentially secure lower premiums.

    Obtaining Quotes

    Professional liability insurance quotes small business

    Obtaining professional liability insurance quotes for small businesses is a crucial step in securing the right coverage for your business. Here’s a step-by-step guide to help you get started:

    There are several methods available for obtaining quotes, including online platforms and insurance brokers. Each method has its own advantages and disadvantages:

    Online Platforms

    • Convenience:Online platforms offer a quick and easy way to compare quotes from multiple insurers.
    • Limited Options:Online platforms may not offer quotes from all insurers, which could limit your options.
    • Less Personalization:Online platforms typically provide less personalized advice compared to insurance brokers.

    Insurance Brokers

    • Personalized Advice:Insurance brokers can provide personalized advice and help you understand the coverage options available.
    • Access to Multiple Insurers:Brokers have access to a wider range of insurers, which can increase your chances of finding the best coverage for your business.
    • Higher Cost:Brokers may charge a fee for their services, which can increase the overall cost of your insurance.

    Once you have chosen a method for obtaining quotes, you can follow these steps to compare quotes and choose the best coverage for your business:

    Compare Coverage and Benefits

    Carefully review the coverage and benefits offered by each insurer. Make sure that the policy meets your specific needs and provides adequate protection for your business.

    Consider Premiums and Deductibles

    Premiums are the annual cost of your insurance, while deductibles are the amount you pay out of pocket before your insurance coverage kicks in. Consider your budget and risk tolerance when comparing premiums and deductibles.

    Check the Insurer’s Financial Stability

    It’s important to choose an insurer with a strong financial rating. This ensures that the insurer will be able to pay out claims in the event of a lawsuit.

    Read the Policy Carefully

    Before purchasing a policy, read the policy carefully to understand the terms and conditions. Make sure that you understand what is covered and what is not.

    Negotiating Premiums

    Negotiating professional liability insurance premiums is crucial for small businesses seeking optimal coverage without breaking the bank. Several strategies can enhance your bargaining position.

    Role of Deductibles, Limits of Liability, and Payment Plans

    Deductibles, limits of liability, and payment plans directly impact premiums. Higher deductibles lower premiums, while increased limits of liability lead to higher premiums. Flexible payment plans may offer discounts for upfront payments.

    Tips for Negotiating with Insurance Companies

    *

    -*Research and Compare Quotes

    Obtain quotes from multiple insurers to compare coverage and rates.

    • -*Provide Detailed Information

      Accurately disclose your business activities, claims history, and risk management measures.

    • -*Emphasize Risk Mitigation

      Highlight implemented risk management protocols to demonstrate your commitment to minimizing potential claims.

    • -*Negotiate Deductibles and Limits

      Discuss adjustments to deductibles and limits of liability to optimize coverage and premiums.

    • -*Explore Discounts and Credits

      Inquire about potential discounts for loyalty, multiple policies, or safety initiatives.

    Importance of Regular Reviews

    Liability pmcaonline

    Maintaining adequate professional liability insurance coverage is crucial for small businesses. Regular reviews ensure that your coverage remains aligned with evolving risks and business needs. Neglecting to review your policy can lead to gaps in coverage, leaving you exposed to financial and reputational risks.

    Checklist for Coverage Reviews

    • Review Coverage Limits:Assess if your coverage limits are sufficient to protect against potential claims. Consider the size of your business, the industry you operate in, and the nature of the services you provide.
    • Examine Exclusions:Identify any exclusions or limitations in your policy that may restrict coverage. Ensure you understand the specific circumstances under which your insurance will not provide protection.
    • Consider Additional Coverages:Explore additional coverage options that may be relevant to your business, such as cyber liability, errors and omissions, or directors and officers insurance.
    • Review Policy Terms:Carefully review the terms and conditions of your policy, including the deductible, reporting requirements, and defense costs.
    • Assess Financial Stability:Verify the financial stability of your insurance provider to ensure they have the resources to cover potential claims.

    Closing Summary

    In conclusion, obtaining professional liability insurance quotes for small businesses is an essential step towards protecting your enterprise. By carefully considering coverage options, understanding factors affecting premiums, and negotiating effectively, you can secure the optimal coverage at the most competitive rates.

    Regular reviews of your policy ensure that your business remains adequately protected as it evolves.

    User Queries: Professional Liability Insurance Quotes Small Business

    What are the common types of professional liability insurance coverage for small businesses?

    Professional liability insurance policies typically cover claims alleging errors, omissions, or negligence in the services provided by your business. These policies can be tailored to specific industries and professions, ensuring that your unique risks are addressed.

    How do I obtain professional liability insurance quotes for my small business?

    There are several ways to obtain quotes for professional liability insurance. You can contact insurance companies directly, use online platforms that compare quotes from multiple providers, or work with an insurance broker who can guide you through the process and negotiate on your behalf.

    What factors influence the cost of professional liability insurance for small businesses?

    The cost of professional liability insurance for small businesses is influenced by several factors, including the size of your business, your industry, your claims history, and your desired coverage limits. Understanding your risk profile and tailoring your policy accordingly can help you secure the best possible rates.

  • Unlock the Best New Business Insurance Quotes for Peace of Mind

    Unlock the Best New Business Insurance Quotes for Peace of Mind

    New business insurance quotes – Embark on a journey to secure the perfect insurance quotes for your burgeoning business. Discover the intricacies of coverage options, risk assessment, and premium factors. Dive into the world of insurance providers, comparing quotes, and deciphering policy terms. Prepare for renewal negotiations and navigate the insurance landscape with confidence.

    Understanding your insurance needs is paramount. Assess your risks, determine coverage levels, and explore the factors that shape your premiums. With this knowledge, you’ll be equipped to compare quotes from reputable providers and negotiate the best deal for your business.

    Understanding New Business Insurance Quotes

    New business insurance quotes

    Understanding the intricacies of new business insurance quotes is paramount for business owners seeking financial protection. This guide will delve into the various coverage options, risk assessment strategies, and factors influencing premium calculations, empowering you to make informed decisions.

    Types of Insurance Coverage for New Businesses

    New businesses require a comprehensive insurance portfolio to mitigate potential risks. Common coverage options include:

    • General Liability Insurance:Protects against claims of bodily injury, property damage, or personal injury caused by your business operations.
    • Commercial Property Insurance:Covers your physical assets, such as buildings, equipment, and inventory, against damage or loss due to events like fire, theft, or vandalism.
    • Business Interruption Insurance:Provides coverage for lost income and expenses incurred if your business is forced to close temporarily due to a covered event.
    • li> Professional Liability Insurance:Protects against claims of negligence or errors in professional services rendered.

    Obtaining Quotes from Multiple Providers: New Business Insurance Quotes

    Acquiring insurance quotes from various providers is crucial to ensure you secure the most suitable and cost-effective coverage for your business. Comparing multiple quotes allows you to evaluate the offerings of different insurers, identify the most competitive rates, and determine the extent of coverage provided.

    Finding Reputable Insurance Companies, New business insurance quotes

    To obtain accurate and reliable quotes, it’s essential to seek quotes from reputable insurance companies with a proven track record. Research the companies’ financial stability, customer service ratings, and industry reputation. You can consult independent rating agencies like AM Best or Standard & Poor’s for insights into the insurers’ financial strength and claims-paying ability.

    Tips for Obtaining Accurate Quotes

    When requesting quotes, provide detailed and accurate information about your business, including its size, industry, revenue, and specific insurance needs. Be transparent about any potential risks or claims history. This information will enable insurers to provide tailored quotes that accurately reflect your business’s unique requirements.

    Key Elements to Consider When Comparing Quotes

    • Coverage:Carefully review the extent of coverage offered by each quote. Ensure it aligns with your business’s specific needs and risk profile.
    • Premium:Compare the premiums quoted by different providers. Consider both the upfront cost and any potential long-term savings or discounts.
    • Deductible:Pay attention to the deductible amount, which represents the portion of any claim you’ll be responsible for paying before the insurance coverage kicks in.
    • Exclusions and Limitations:Understand any exclusions or limitations in the policies, as they can impact the coverage you receive.
    • Customer Service:Consider the reputation of each insurer for providing prompt and helpful customer service in the event of a claim.

    Evaluating Insurance Policies

    Insurance business quotes

    Understanding the intricacies of insurance policies is crucial to making informed decisions. These policies contain specific terms and conditions that define the coverage provided, the exclusions and limitations, and the responsibilities of both the insurer and the policyholder. A thorough evaluation of these policies ensures that you fully comprehend the protection you’re purchasing and the potential gaps that may exist.

    Identifying and Evaluating Coverage Exclusions and Limitations

    Insurance policies often contain exclusions and limitations that specify situations or events that are not covered under the policy. It’s essential to carefully review these exclusions and limitations to determine their potential impact on your coverage. Some common exclusions include:

    • Acts of war or terrorism
    • Pre-existing medical conditions
    • Intentional acts or criminal behavior

    Understanding these exclusions and limitations allows you to identify any potential gaps in your coverage and consider additional measures to mitigate risks that may not be covered by the policy.

    Negotiating Premiums and Coverage

    New business insurance quotes

    Negotiating insurance premiums and coverage involves a dialogue between you and insurance providers to reach mutually agreeable terms. Effective communication and strategic planning are key to securing the best possible deal while maintaining adequate coverage.

    To initiate negotiations, gather relevant information about your business, including financial statements, loss history, and industry-specific risks. This data will help you justify your requests and demonstrate your understanding of the insurance landscape.

    Communicating with Insurance Agents

    When communicating with insurance agents, clarity and assertiveness are essential. Clearly articulate your coverage needs, budget constraints, and expectations. Be prepared to provide supporting documentation and ask questions to ensure a thorough understanding of the policies being offered.

    • Be specific:Artikel your desired coverage levels and any specific exclusions or endorsements you require.
    • Be realistic:Understand the market value of your coverage and avoid unrealistic expectations.
    • Be confident:Express your knowledge and understanding of the insurance process, but be open to suggestions and negotiations.

    Strategies for Reducing Insurance Costs

    While negotiating coverage, consider strategies to reduce insurance costs without sacrificing protection. These include:

    • Increase deductibles:Raising your deductibles can lower your premiums, but ensure you can afford the higher out-of-pocket expenses in case of a claim.
    • Bundle policies:Combining multiple insurance policies with the same provider can often result in discounts.
    • Implement risk management measures:Proactively reducing risks within your business, such as installing security systems or implementing safety protocols, can make you a more attractive insurance prospect.

    Securing the Best Deal

    To secure the best possible deal, consider the following:

    • Obtain quotes from multiple providers:Compare premiums and coverage options from several insurance companies to ensure you’re getting the most competitive rates.
    • Negotiate coverage limits:Adjust coverage limits to meet your specific needs and budget, ensuring you have adequate protection without overpaying.
    • Review policy terms carefully:Before signing any contracts, thoroughly review the policy terms and conditions to ensure they align with your expectations.

    Managing Insurance Renewals

    Maintaining up-to-date insurance coverage is crucial for businesses of all sizes. Failing to renew insurance policies promptly can result in coverage gaps, leaving businesses vulnerable to financial losses. This section provides guidance on the significance of timely insurance policy renewals, how to prepare for renewal negotiations, and steps to take if you are not satisfied with your current insurance coverage.

    Preparing for Insurance Renewal Negotiations

    Prior to insurance renewal, it is essential to assess your current coverage and identify any areas that need adjustment. Consider the following steps:

    1. Review your existing policy: Examine the terms, limits, and deductibles to determine if they still meet your business needs.
    2. Evaluate your risk profile: Assess any changes in your business operations or industry that may impact your insurance requirements.
    3. Shop around for quotes: Obtain quotes from multiple insurance providers to compare coverage options and premiums.
    4. Negotiate with your current provider: Discuss your renewal terms with your current insurer, presenting your research and justification for any requested changes.
    5. Consider alternative options: If you are not satisfied with your current insurer’s renewal offer, explore other insurance providers or consider self-insurance options.

    Steps to Take if Dissatisfied with Current Coverage

    If you are not satisfied with your current insurance coverage, you have several options:

    • Negotiate with your current insurer: Communicate your concerns and request changes to the policy terms or premiums.
    • Switch to a different insurer: Obtain quotes from other insurance providers and compare coverage options and premiums before making a decision.
    • Consider self-insurance: Evaluate the feasibility of self-insuring certain risks, assuming the financial responsibility yourself.

    Last Recap

    Securing the right insurance coverage is a cornerstone of business success. By following these steps, you’ll gain a comprehensive understanding of new business insurance quotes and make informed decisions. Remember, the journey to protecting your business starts with a thorough evaluation of your needs and ends with a policy that provides peace of mind.

    Detailed FAQs

    What are the key types of insurance coverage for new businesses?

    General liability, property insurance, business interruption insurance, and workers’ compensation insurance are essential for protecting your business.

    How do I determine the appropriate coverage levels for my business?

    Assess your potential risks, consider the value of your assets, and consult with an insurance professional to determine the optimal coverage levels.

    What factors influence insurance premiums for new businesses?

    Industry, location, claims history, and business size are among the factors that impact your premiums.

  • Secure Your Business: Small Business Liability Insurance Quote

    Secure Your Business: Small Business Liability Insurance Quote

    In the dynamic realm of entrepreneurship, safeguarding your small business against unforeseen risks is paramount. Liability insurance serves as a financial shield, protecting you from the potentially devastating consequences of property damage, bodily injury, and legal claims. Embark on this journey to explore the intricacies of small business liability insurance quotes, ensuring your venture remains resilient and protected.

    Liability insurance empowers small businesses to navigate the challenges of modern commerce with confidence. General liability insurance provides a safety net against claims of bodily injury or property damage, while professional liability insurance safeguards against errors and omissions in the provision of services.

    Errors and omissions insurance, tailored for specific industries, offers an additional layer of protection against financial losses resulting from mistakes or oversights.

    Business Liability Risks: Small Business Liability Insurance Quote

    Small businesses are subject to various liabilities that can lead to financial losses, legal disputes, and reputational damage. Understanding these risks and obtaining appropriate insurance coverage is crucial for safeguarding the business and its owners.

    The potential liabilities faced by small businesses fall into three primary categories: property damage, bodily injury, and legal claims.

    Property Damage

    Property damage refers to damage caused to property owned by others, including buildings, equipment, and inventory. This can occur due to various factors, such as fires, floods, storms, or accidents caused by employees or customers.

    The financial consequences of property damage can be significant, especially for small businesses with limited resources. The costs associated with repairs, replacements, and business interruptions can severely impact operations and profitability.

    Bodily Injury

    Bodily injury refers to physical harm caused to individuals, such as customers, employees, or members of the public, as a result of business operations or premises.

    Bodily injury claims can be particularly costly and can lead to lawsuits, settlements, and legal expenses. The severity of the injury, the extent of medical treatment required, and the potential for long-term disabilities can have a significant financial impact on the business.

    Legal Claims

    Legal claims cover a wide range of disputes that can arise in the course of business, such as breach of contract, negligence, defamation, and employment-related issues.

    Defending against legal claims can be time-consuming and expensive, even if the business is ultimately successful in the lawsuit. The reputational damage associated with legal disputes can also harm the business’s customer base and future prospects.

    Coverage Options for Small Businesses

    Insurance liability

    Liability insurance provides financial protection for small businesses against claims of legal liability. Different types of liability insurance offer varying levels of coverage to suit specific business needs.

    General Liability Insurance

    • Covers bodily injury, property damage, and personal injury claims caused by the business or its employees during business operations.
    • Protects against common risks such as customer slips and falls, product defects, and advertising injuries.
    • Provides a broad range of coverage, making it essential for most small businesses.

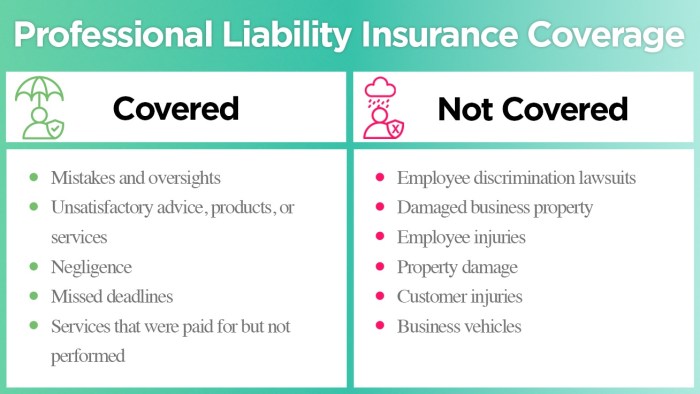
    Professional Liability Insurance

    • Protects professionals and service providers against claims of negligence, errors, or omissions in the performance of their professional duties.
    • Covers a wide range of professionals, including accountants, lawyers, engineers, and consultants.
    • Provides peace of mind by safeguarding against financial losses resulting from professional mistakes or oversights.

    Errors and Omissions Insurance

    • Similar to professional liability insurance, but specifically designed for businesses that provide advice or guidance.
    • Covers claims of financial loss or damages resulting from errors or omissions in the advice or services provided.
    • Protects businesses against financial consequences arising from inaccurate information or recommendations.

    Factors Affecting Liability Insurance Quotes

    Small business liability insurance quote

    When determining liability insurance quotes for small businesses, insurance companies carefully consider several key factors that can significantly impact the cost and coverage of the policies.

    These factors include:

    Industry

    The type of industry in which a small business operates plays a crucial role in determining its liability risks. Businesses in high-risk industries, such as construction, manufacturing, or healthcare, typically face higher liability insurance premiums due to the increased potential for accidents, injuries, or property damage.

    Revenue

    The annual revenue generated by a small business is another important factor that insurance companies consider when determining liability insurance quotes. Higher revenue often translates to increased exposure to liability risks, as businesses with larger operations typically have more employees, customers, and assets that could potentially be affected by an incident.

    Number of Employees

    The number of employees a small business has can also impact its liability insurance quotes. Businesses with a larger workforce have a higher probability of experiencing employee-related incidents, such as workplace accidents, discrimination claims, or harassment allegations. These factors can increase the potential for liability claims and, consequently, the cost of insurance premiums.

    Claims History, Small business liability insurance quote

    Insurance companies review a small business’s claims history to assess its past liability risks. Businesses with a history of frequent or severe claims may be considered higher risk and face higher insurance premiums. Conversely, businesses with a clean claims history may qualify for lower premiums.

    Getting a Liability Insurance Quote

    Small business liability insurance quote

    Obtaining a liability insurance quote is a crucial step for small businesses to protect themselves financially against potential legal claims and liabilities. The process involves providing information about the business and its operations, and there are several ways to obtain a quote.

    Online Quotes:Many insurance companies offer online quote systems that allow businesses to enter their information and receive an instant quote. This is a convenient and efficient way to compare quotes from different providers.

    Through an Agent:Insurance agents can help businesses navigate the insurance market and find the best coverage for their needs. They can provide personalized advice and assist with the application process.

    Over the Phone:Businesses can also contact insurance companies directly over the phone to request a quote. This option allows for direct interaction with a representative who can answer questions and provide guidance.

    Tips for Comparing Quotes

    When comparing liability insurance quotes, it’s essential to consider the following factors:

    • Coverage Limits:Ensure that the coverage limits are adequate to protect the business from potential claims.
    • Deductibles:The deductible is the amount the business will pay out-of-pocket before the insurance coverage kicks in.
    • Premiums:Compare the premium costs from different providers to find the most affordable option.
    • Company Reputation:Research the reputation of the insurance company to ensure they are financially stable and have a good track record of customer service.

    By carefully comparing quotes and considering the factors mentioned above, small businesses can make informed decisions and choose the best liability insurance coverage for their specific needs.

    Additional Considerations for Small Businesses

    Small businesses often face a range of risks beyond liability. Additional insurance considerations can provide comprehensive protection and mitigate potential losses.Workers’ compensation insurance protects businesses from financial liability in case an employee suffers a work-related injury or illness. It covers medical expenses, lost wages, and disability benefits.Property

    insurance protects a business’s physical assets, such as buildings, equipment, and inventory, from damage or loss due to events like fire, theft, or natural disasters.Business interruption insurance provides coverage for lost income and expenses incurred when a business is forced to suspend operations due to an insured event, such as a natural disaster or a fire.

    Final Wrap-Up

    Securing a liability insurance quote for your small business is a crucial step towards comprehensive risk management. By understanding the factors that influence insurance quotes, such as industry, revenue, and claims history, you can make informed decisions about the coverage that best suits your needs.

    With the right liability insurance in place, you can focus on growing your business, knowing that you have a financial safety net to protect you from unforeseen events.

    Top FAQs

    What factors influence liability insurance quotes?

    Insurance companies consider factors such as industry, revenue, number of employees, and claims history when determining liability insurance quotes.

    How do I get a liability insurance quote?

    You can obtain a liability insurance quote online, through an insurance agent, or by contacting insurance companies directly. Be prepared to provide information about your business, including its industry, revenue, and claims history.

    What types of liability insurance are available for small businesses?

    Common types of liability insurance for small businesses include general liability insurance, professional liability insurance, and errors and omissions insurance.