Tag: coverage options

  • Finding the Best Homeowners Car Insurance: A Comprehensive Guide

    Finding the Best Homeowners Car Insurance: A Comprehensive Guide

    Comparative Analysis of Homeowners Car Insurance Providers

    Finding best homeowners car insurance – Navigating the homeowners car insurance market can be overwhelming, with numerous providers offering a range of coverage options and pricing. To simplify your search, we’ve compiled a comprehensive comparison of leading providers, analyzing their coverage, premiums, deductibles, and customer service ratings.

    Our analysis reveals that several factors contribute to the overall value of a homeowners car insurance policy. These include the level of coverage provided, the premium charged, the deductible amount, and the quality of customer service. By comparing these aspects across multiple providers, you can make an informed decision that meets your specific needs and budget.

    Coverage Options

    Homeowners car insurance policies typically offer a variety of coverage options, including liability, collision, comprehensive, and uninsured/underinsured motorist protection. Liability coverage protects you from financial responsibility if you cause an accident, while collision and comprehensive coverage protect your vehicle from damage or loss.

    Uninsured/underinsured motorist protection provides coverage if you’re involved in an accident with a driver who doesn’t have insurance or has insufficient coverage.

    Provider Liability Coverage Collision Coverage Comprehensive Coverage Uninsured/Underinsured Motorist Protection
    Provider A $100,000/$300,000/$50,000 Actual Cash Value Actual Cash Value $100,000/$300,000
    Provider B $250,000/$500,000/$100,000 Replacement Cost Replacement Cost $250,000/$500,000
    Provider C $500,000/$1,000,000/$250,000 Stated Amount Stated Amount $500,000/$1,000,000
    Provider D $1,000,000/$2,000,000/$500,000 Agreed Value Agreed Value $1,000,000/$2,000,000

    Premiums

    Premiums are the monthly or annual payments you make for your homeowners car insurance policy. The amount of your premium is determined by several factors, including your driving record, the type of vehicle you drive, the amount of coverage you choose, and your deductible.

    Generally, higher coverage limits and lower deductibles result in higher premiums.

    Deductibles, Finding best homeowners car insurance

    A deductible is the amount you pay out of pocket before your insurance coverage kicks in. Higher deductibles typically lower your premiums, but they also mean you’ll have to pay more if you file a claim. It’s important to choose a deductible that you can comfortably afford to pay.

    Customer Service Ratings

    Customer service is an important factor to consider when choosing a homeowners car insurance provider. You want to be sure that you can get help when you need it, whether you’re filing a claim or simply have a question about your policy.

    Look for providers with high customer satisfaction ratings and positive reviews.

    Factors to Consider When Choosing Homeowners Car Insurance

    When selecting homeowners car insurance, several key factors come into play. These include coverage types, policy limits, deductibles, and available discounts. Understanding these factors and their implications will help you make an informed decision and secure the most suitable coverage for your needs.

    Coverage Types

    Homeowners car insurance typically offers a range of coverage options, including:

    • Liability coverage: Covers damages or injuries caused to others due to your negligence while driving.
    • Collision coverage: Protects your vehicle from damages sustained in an accident with another vehicle or object.
    • Comprehensive coverage: Covers non-collision-related damages, such as theft, vandalism, or natural disasters.

    The coverage types you choose will depend on your individual circumstances and risk tolerance.

    Policy Limits

    Policy limits refer to the maximum amount your insurance company will pay for covered losses. It’s crucial to choose limits that are sufficient to cover potential expenses. Liability limits are typically expressed in terms of per-person and per-accident amounts. For example, a policy with limits of 100/300 means it will cover up to $100,000 per person injured in an accident and up to $300,000 for all injuries resulting from the same accident.

    Deductibles, Finding best homeowners car insurance

    A deductible is the amount you pay out-of-pocket before your insurance coverage kicks in. Higher deductibles typically result in lower premiums, while lower deductibles come with higher premiums. When selecting a deductible, consider your financial situation and risk tolerance.

    Discounts

    Many insurance companies offer discounts for certain factors, such as:

    • Multi-policy discounts: Discounts for bundling homeowners and car insurance with the same provider.
    • Good driver discounts: Discounts for maintaining a clean driving record.
    • Safety feature discounts: Discounts for vehicles equipped with anti-theft devices or other safety features.

    These discounts can help you save money on your premiums.

    Tips for Finding Affordable Homeowners Car Insurance
    Finding best homeowners car insurance

    Finding affordable homeowners car insurance can be a challenge, but it’s possible with the right strategies. Here are some tips to help you save money on your premiums:

    Negotiate with your insurance company. If you’re a loyal customer, you may be able to get a discount on your premiums. You can also try negotiating a lower deductible or a payment plan that works for you.

    Compare Quotes

    Get quotes from multiple insurance companies before you buy a policy. This will help you find the best rate for your needs. When comparing quotes, be sure to compare the coverage limits, deductibles, and premiums.

    Take Advantage of Discounts

    Many insurance companies offer discounts for things like bundling your home and auto insurance, having a good driving record, or taking a defensive driving course. Be sure to ask your insurance company about any discounts you may be eligible for.

    • Bundle your home and auto insurance with the same company.
    • Maintain a good driving record.
    • Take a defensive driving course.
    • Install anti-theft devices on your car.
    • Drive less than the average number of miles per year.
    • Park your car in a garage.
    • Raise your deductible.
    • Shop around for the best rates.

    Coverage Options for Homeowners Car Insurance
    Finding best homeowners car insurance

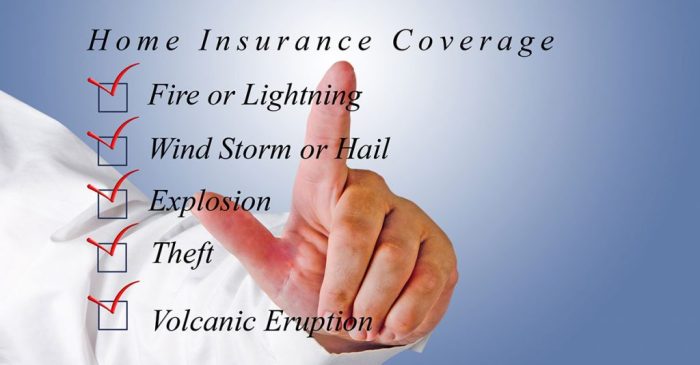
    Homeowners car insurance offers a range of coverage options to protect your vehicle and finances in various scenarios. Understanding the different types of coverage and their benefits is crucial to selecting the best policy for your needs.

    Comprehensive Coverage

    Comprehensive coverage provides protection against non-collision-related incidents, such as theft, vandalism, natural disasters (e.g., hail, flooding), and animal collisions. It covers the cost of repairs or replacement of your vehicle up to the policy limit.

    Collision Coverage

    Collision coverage protects your vehicle in case of a collision with another object, regardless of fault. It covers the cost of repairs or replacement up to the policy limit.

    Liability Coverage

    Liability coverage is mandatory in most states and protects you from financial responsibility if you cause injury or damage to others or their property in a car accident. It includes:

    • Bodily Injury Liability:Covers medical expenses and lost wages for individuals injured in an accident caused by you.
    • Property Damage Liability:Covers damage to other vehicles or property resulting from an accident caused by you.

    Other Optional Coverage Options

    In addition to the essential coverage options, homeowners car insurance policies may offer additional coverage, such as:

    • Uninsured/Underinsured Motorist Coverage:Protects you in case of an accident with a driver who is uninsured or underinsured.
    • Medical Payments Coverage:Covers medical expenses for you and your passengers, regardless of fault.
    • Rental Reimbursement Coverage:Reimburses you for rental car expenses while your vehicle is being repaired or replaced.
    Coverage Type Protection Provided Benefits Limitations
    Comprehensive Non-collision-related incidents (e.g., theft, vandalism, natural disasters) Protects against a wide range of events Higher premiums than other coverage options
    Collision Collisions with other objects Covers repairs or replacement of your vehicle Does not cover non-collision-related incidents
    Liability Injury or damage caused to others Mandatory in most states Does not cover your own injuries or vehicle damage

    Understanding Deductibles and Premiums in Homeowners Car Insurance
    Surfky homeowners

    Deductibles and premiums are two important factors to consider when choosing homeowners car insurance. A deductible is the amount you pay out of pocket before your insurance coverage kicks in. Premiums are the regular payments you make to your insurance company to maintain your coverage.

    There is an inverse relationship between deductibles and premiums. Choosing a higher deductible will lower your premiums, and vice versa. This is because the insurance company takes on less risk when you have a higher deductible, so they can charge you less for coverage.

    Example

    For example, if you have a $500 deductible, you will pay more in premiums than if you have a $1,000 deductible. However, if you file a claim, you will only have to pay the first $500 out of pocket with a $500 deductible, while you would have to pay the first $1,000 out of pocket with a $1,000 deductible.

    Essential Questionnaire: Finding Best Homeowners Car Insurance

    What factors should I consider when choosing homeowners car insurance?

    Coverage types, policy limits, deductibles, discounts, and your individual driving history.

    How can I find affordable homeowners car insurance?

    Negotiate premiums, compare quotes, take advantage of discounts, and maintain a good driving record.

    What are the different coverage options available for homeowners car insurance?

    Comprehensive, collision, liability, uninsured/underinsured motorist, and personal injury protection.
  • 25 Ways to Find the Best Automobile Insurance Companies

    25 Ways to Find the Best Automobile Insurance Companies

    Identify Reputable Sources

    25 ways to Find best automobile insurance companies

    25 ways to Find best automobile insurance companies – Identifying reputable sources is crucial for evaluating automobile insurance companies. By consulting independent rating agencies and consumer protection organizations, you can gather unbiased information and make informed decisions.

    Rating Agencies

    Reputable rating agencies provide comprehensive evaluations of insurance companies based on financial strength, claims handling, and customer satisfaction. Consider agencies like J.D. Power, A.M. Best, and Moody’s for reliable ratings.

    Consumer Protection Organizations

    Consumer protection organizations, such as the National Association of Insurance Commissioners (NAIC) and the Better Business Bureau (BBB), offer valuable insights into insurance companies’ practices. They investigate complaints, monitor industry trends, and provide consumer alerts.

    Consider Company Reputation

    When evaluating insurance companies, their reputation should be a key consideration. This includes researching customer reviews and testimonials on platforms like Trustpilot, Consumer Reports, and Yelp. These platforms provide valuable insights into the experiences and satisfaction levels of previous customers.

    Additionally, checking social media channels can provide further feedback and engagement. Social media allows customers to share their experiences and opinions in real-time, offering a more candid and up-to-date perspective on the company’s service and responsiveness.

    Researching Customer Reviews

    • Read reviews on multiple platforms to get a comprehensive view.
    • Pay attention to the overall rating and the specific feedback provided.
    • Look for reviews that are detailed and provide specific examples.
    • Consider the date of the reviews to ensure they are up-to-date.

    Checking Social Media Channels

    • Follow the company’s social media pages to stay updated on their activities.
    • Monitor customer interactions and comments on social media posts.
    • Engage with customers who have positive or negative experiences.
    • Use social media to ask questions and gather feedback from current customers.

    Analyze Financial Stability

    Assessing a company’s financial stability is crucial to ensure its ability to fulfill its obligations and pay claims promptly. Accessing financial reports can provide insights into the company’s financial health.

    Key metrics to examine include:

    • Assets:The total value of the company’s holdings, including cash, investments, and real estate.
    • Liabilities:The total amount the company owes to others, such as policyholders and creditors.
    • Surplus:The difference between assets and liabilities, representing the company’s financial cushion.

    Understanding Key Metrics

    A high surplus indicates the company’s ability to absorb losses and fulfill its obligations. Conversely, a low surplus may raise concerns about the company’s financial stability.

    Additionally, examining the company’s financial ratios can provide further insights:

    • Current Ratio:Assets divided by liabilities, indicating the company’s ability to meet short-term obligations.
    • Debt-to-Equity Ratio:Liabilities divided by equity, indicating the company’s reliance on debt financing.
    • Return on Equity (ROE):Net income divided by equity, indicating the company’s profitability.

    Strong financial ratios suggest a stable and well-managed company, while weak ratios may warrant further investigation.

    Compare Coverage Options

    25 ways to Find best automobile insurance companies

    When comparing automobile insurance companies, it’s crucial to evaluate the coverage options they offer. Different policies provide varying levels of protection, and it’s important to tailor your coverage to your individual needs and risk tolerance.

    Types of Coverage

    There are three main types of automobile insurance coverage:

    • Liability Coverage:Covers damages to others and their property caused by your negligence while driving.
    • Collision Coverage:Covers damages to your vehicle if it collides with another vehicle or object.
    • Comprehensive Coverage:Covers damages to your vehicle from events other than collisions, such as theft, vandalism, or natural disasters.

    Tailoring Coverage

    The optimal coverage for you depends on your circumstances. Consider factors such as:

    • Your driving history and risk tolerance
    • The value of your vehicle
    • Your financial situation

    For example, if you have a history of accidents or drive in a high-risk area, you may want to consider higher liability coverage. If your vehicle is expensive or you have limited financial resources, comprehensive coverage may be a wise choice.By

    comparing coverage options and tailoring your policy to your specific needs, you can ensure you have the right level of protection for your automobile.

    Evaluate Customer Service: 25 Ways To Find Best Automobile Insurance Companies

    25 ways to Find best automobile insurance companies

    Customer service is crucial when choosing an auto insurance company. Assess its quality through online reviews, phone inquiries, and social media interactions. Positive feedback, prompt responses, and helpful support indicate a company that values its customers.

    Online Reviews

    Read reviews on platforms like Trustpilot and Google My Business. Look for feedback on the responsiveness, professionalism, and resolution time of customer service.

    Phone Inquiries

    Call the company’s customer service line and ask questions about coverage options, claims handling, and policy details. Evaluate the politeness, knowledge, and efficiency of the representative.

    Social Media Interactions, 25 ways to Find best automobile insurance companies

    Engage with the company on social media. Check their posts, comments, and direct messages to observe how they handle customer inquiries and resolve complaints.

    FAQ Summary

    What factors should I consider when choosing an automobile insurance company?

    Reputation, financial stability, coverage options, customer service, and affordability are key factors to evaluate.

    How can I compare coverage options from different insurance companies?

    Carefully review the types of coverage offered, including liability, collision, and comprehensive, and tailor them to your specific needs and risk tolerance.

    What are some ways to assess the financial stability of an insurance company?

    Access financial reports and analyze key metrics such as assets, liabilities, and surplus to understand the company’s ability to pay claims and fulfill its obligations.

  • 17 Tips to Secure the Best Car Insurance Companies

    17 Tips to Secure the Best Car Insurance Companies

    Identifying the Best Insurance Companies

    17 tips how to get good car insurance companies – Choosing the right car insurance company is crucial for securing the best coverage and value for your money. Consider the following factors when selecting an insurer:

    Financial Stability

    Check the insurer’s financial strength ratings from independent agencies like AM Best, Moody’s, and Standard & Poor’s. A strong financial rating indicates the company’s ability to meet its financial obligations, including paying claims.

    Customer Service

    Read reviews and testimonials to gauge the company’s customer service record. Look for insurers with a reputation for prompt and courteous assistance, especially during claims processing.

    Coverage Options

    Compare the coverage options offered by different insurers. Ensure the company provides the specific coverages you need, such as liability, collision, and comprehensive coverage.

    Table: Comparing Insurance Companies

    Use the following table to compare the key features and offerings of different insurance companies:

    Company Financial Rating Customer Service Rating Coverage Options Rates
    Company A A+ 9/10 Comprehensive coverage $1,200/year
    Company B A 8/10 Standard coverage $1,000/year
    Company C B+ 7/10 Basic coverage $800/year

    Benefits of Using Insurance Brokers

    Insurance brokers can assist you in finding the best deals on car insurance. They have access to multiple insurance companies and can compare quotes to find the most competitive rates and coverage options that meet your specific needs.

    Understanding Insurance Coverage

    17 tips how to get good car insurance companies

    Understanding car insurance coverage is crucial to make informed decisions and protect yourself financially in case of an accident. Various types of coverage are available, each serving a specific purpose. Let’s delve into the details to help you customize your policy and ensure adequate protection.

    Types of Car Insurance Coverage

    • Liability Coverage:This covers damages or injuries caused to others (third parties) in an accident where you are at fault. It includes bodily injury liability (covers medical expenses and lost wages for injured parties) and property damage liability (covers damage to property belonging to others).

    • Collision Coverage:This covers damages to your own vehicle in the event of a collision with another vehicle or object, regardless of who is at fault. It typically has a deductible, which is the amount you pay out of pocket before insurance coverage kicks in.

    • Comprehensive Coverage:This covers damages to your vehicle caused by events other than collisions, such as theft, vandalism, fire, or natural disasters. Like collision coverage, it also has a deductible.

    Saving Money on Insurance Premiums

    Saving money on car insurance premiums is essential for any driver. Here are some tips to help you lower your costs:

    Maintain a good driving record: One of the most important factors that insurance companies consider when setting rates is your driving record. If you have a clean driving record, you will likely be eligible for lower premiums. You can keep your record clean by avoiding accidents and traffic violations.

    Take defensive driving courses: Defensive driving courses can help you improve your driving skills and make you a safer driver. Insurance companies often offer discounts to drivers who complete these courses.

    Bundle policies: If you have multiple insurance policies, such as car insurance and homeowners insurance, you may be able to save money by bundling them together. Many insurance companies offer discounts for bundling policies.

    Negotiate with your insurance company: If you are not satisfied with your current insurance rates, you can try negotiating with your insurance company. You may be able to get a better rate by shopping around for quotes from other insurance companies.

    Telematics Devices

    Telematics devices are devices that track your driving behavior. Insurance companies may offer discounts to drivers who use these devices. The discounts are based on the data collected by the devices, which can include information such as your driving speed, braking habits, and mileage.

    There are both pros and cons to using telematics devices. On the one hand, they can help you save money on your insurance premiums. On the other hand, they can also be used to track your location and driving habits.

    If you are concerned about your privacy, you may want to consider opting out of using a telematics device.

    Filing and Managing Claims: 17 Tips How To Get Good Car Insurance Companies

    17 tips how to get good car insurance companies

    In the unfortunate event of a car accident, filing a claim with your insurance company is essential to recover compensation for damages and expenses. Understanding the process and following the proper steps can ensure a smooth and successful claim experience.

    To initiate a claim, gather all necessary documentation, including police reports, medical records, witness statements, and photos of the damage. Contact your insurance company promptly to report the accident and provide them with the collected information.

    Communicating with Insurance Adjusters

    An insurance adjuster will be assigned to your claim to assess the damage and determine the settlement amount. It’s crucial to communicate effectively with the adjuster by providing clear and accurate information. Stay organized, keep track of all correspondence, and be prepared to answer their questions thoroughly.

    Special Considerations

    17 tips how to get good car insurance companies

    Drivers with specific circumstances may require tailored insurance coverage. This section explores the unique needs of high-risk drivers, young drivers, drivers with poor credit, and owners of classic and exotic cars.

    Regularly reviewing insurance policies is crucial to ensure adequate coverage and cost-effectiveness.

    High-Risk Drivers

    • Individuals with a history of traffic violations, accidents, or DUIs may be considered high-risk drivers.
    • They typically face higher insurance premiums due to the increased risk they pose to insurance companies.
    • High-risk drivers can improve their insurance rates by maintaining a clean driving record, taking defensive driving courses, and installing safety devices in their vehicles.

    Young Drivers

    • Young drivers often pay higher insurance premiums due to their limited driving experience and higher accident rates.
    • Parents or guardians can add young drivers to their own policies to save on insurance costs.
    • Young drivers can also qualify for discounts by maintaining good grades, taking driver safety courses, and avoiding traffic violations.

    Drivers with Poor Credit

    • Insurance companies may use credit scores to assess risk and determine insurance premiums.
    • Drivers with poor credit may be seen as higher risks and charged higher premiums.
    • Improving credit scores can help drivers lower their insurance rates.

    Classic and Exotic Cars, 17 tips how to get good car insurance companies

    • Classic and exotic cars require specialized insurance coverage due to their rarity and value.
    • Owners should seek insurance companies that specialize in insuring collector cars.
    • Agreed-value policies are recommended to ensure the car is insured for its full value.

    Regular Policy Review

    Insurance policies should be reviewed regularly to ensure they still meet the driver’s needs.

    • Changes in lifestyle, driving habits, or vehicle ownership may necessitate adjustments to coverage.
    • Insurance premiums can fluctuate over time, so it’s important to compare quotes from multiple companies to find the best rates.
    • Drivers should also consider increasing coverage limits as the value of their vehicle or assets increases.

    Commonly Asked Questions

    What factors should I consider when choosing a car insurance company?

    When selecting an insurance company, it’s essential to consider their financial stability, customer service reputation, and the coverage options they offer.

    How can I save money on my car insurance premiums?

    Maintaining a good driving record, taking defensive driving courses, and bundling policies are effective ways to lower your insurance premiums.

    What steps should I take if I need to file a car insurance claim?

    Gather necessary documentation, such as a police report and photos of the damage, and contact your insurance company promptly to initiate the claims process.

  • Small Business Insurance Contractors: A Guide to Coverage and Protection

    Small Business Insurance Contractors: A Guide to Coverage and Protection

    Small business insurance contractors play a vital role in safeguarding businesses from unexpected risks and financial losses. This comprehensive guide delves into the intricacies of insurance coverage options, empowering contractors to tailor policies that align with their specific needs and ensure their business’s resilience.

    Navigating the insurance landscape can be daunting, but this guide provides a clear roadmap for assessing coverage limits, comparing providers, and understanding policy language. By embracing the insights and strategies Artikeld here, small business insurance contractors can confidently manage risks and secure their path to success.

    Insurance Coverage Options

    Small business insurance contractor

    Small business contractors face unique risks that require specialized insurance coverage. Understanding the various types of insurance available is crucial to protect your business and mitigate potential financial losses.

    Tailoring your insurance coverage to your specific business needs is essential. Consider the size of your business, the types of projects you undertake, and the potential risks involved. A comprehensive insurance plan should provide peace of mind and ensure your business can continue to operate smoothly in the event of an unforeseen incident.

    General Liability Insurance

    Protects against claims of bodily injury, property damage, or personal injury caused by your business operations. Common risks covered include:

    • Customer slips and falls on your premises
    • Damage to a client’s property during a project
    • Libel or slander claims

    Property Insurance

    Covers damage or loss to your business property, including buildings, equipment, inventory, and tools. Common risks covered include:

    • Fire or explosion
    • Theft or vandalism
    • Natural disasters

    Workers’ Compensation Insurance, Small business insurance contractor

    Provides coverage for employees who suffer injuries or illnesses on the job. Common risks covered include:

    • Medical expenses
    • Lost wages
    • Disability benefits

    Commercial Auto Insurance

    Protects against liability and damages caused by vehicles used for business purposes. Common risks covered include:

    • Collisions
    • Bodily injury to others
    • Property damage

    Professional Liability Insurance

    Covers claims against professionals for errors or omissions in their work. Common risks covered include:

    • Malpractice
    • Negligence
    • Breach of contract

    Determining Coverage Limits and Deductibles

    Small business insurance contractor

    Determining appropriate coverage limits and deductibles is crucial for small business insurance contractors. By carefully assessing your insurance needs, you can tailor a policy that provides optimal protection without breaking the bank.

    Insurance coverage limits define the maximum amount your insurer will pay for covered losses. Higher limits offer more comprehensive coverage, but they also come with higher premiums. Conversely, lower limits may result in insufficient coverage in the event of a major loss.

    Setting Coverage Limits

    Consider the following factors when setting coverage limits:

    • Business Value:Determine the replacement cost of your equipment, inventory, and property.
    • Potential Liability:Assess the potential financial impact of lawsuits or claims against your business.
    • Industry Standards:Research industry benchmarks and consult with your insurance agent to determine recommended coverage limits.

    Selecting Deductibles

    Deductibles represent the amount you pay out-of-pocket before your insurance coverage kicks in. Higher deductibles lower your premiums, but they also increase your financial risk in the event of a claim.

    • Balancing Affordability and Coverage:Determine a deductible that strikes a balance between affordability and adequate coverage. Consider your financial situation and the likelihood of filing claims.
    • Consider Multiple Deductibles:Some policies allow you to set different deductibles for different coverages, providing flexibility and cost savings.
    • Remember Out-of-Pocket Expenses:In addition to the deductible, you may also be responsible for other out-of-pocket expenses, such as attorney fees or appraisal costs.

    Comparing Insurance Providers

    Selecting the right insurance provider for your small business is crucial to ensure adequate protection and financial stability. Comparing different providers empowers you to find the best fit for your coverage needs, premiums, and customer service.

    Consider these key factors when comparing providers:

    Coverage

    • Review the coverage options provided by each insurer and ensure they align with your business’s specific risks.
    • Check for any exclusions or limitations that may restrict coverage.
    • Consider the financial strength and reputation of the insurer to ensure they can fulfill their obligations in the event of a claim.

    Premiums

    • Compare the premiums charged by different providers for similar coverage levels.
    • Inquire about discounts and incentives that may reduce your premiums, such as bundling policies or implementing safety measures.
    • Consider the long-term cost of insurance, including potential premium increases and deductibles.

    Customer Service

    • Research the reputation of each insurer for providing responsive and helpful customer service.
    • Check for online reviews or testimonials from other businesses.
    • Contact the insurers directly to inquire about their claims process and availability of support.

    To obtain quotes and evaluate proposals, follow these tips:

    • Provide accurate and complete information about your business to ensure accurate quotes.
    • Compare multiple quotes from different providers to get a comprehensive view of the market.
    • Review the proposals carefully, paying attention to the coverage details, premiums, and deductibles.
    • Consider seeking professional advice from an insurance broker or agent to guide you through the process.

    Understanding Insurance Policy Language

    Seguros sector assurances vertalingen traducciones traductions

    Insurance policies are legal contracts that Artikel the coverage provided by the insurer. Understanding the language used in these policies is crucial to ensure you have the proper coverage for your business.Key terms and concepts used in insurance policies include:

    • Policyholder:The individual or business that purchases the insurance policy.
    • Insurer:The insurance company that provides the coverage.
    • Premium:The amount paid by the policyholder to the insurer for the coverage.
    • Deductible:The amount the policyholder must pay out-of-pocket before the insurer begins to pay for covered losses.
    • Coverage limits:The maximum amount the insurer will pay for covered losses.

    Common policy provisions include:

    • Exclusions:Specific types of losses or situations that are not covered by the policy.
    • Conditions:Requirements that must be met by the policyholder to maintain coverage.
    • Endorsements:Amendments to the policy that add or modify coverage.

    It is important to understand the policy language to ensure proper coverage. If you have any questions about your policy, consult with your insurance agent or an attorney.

    Managing Insurance Claims: Small Business Insurance Contractor

    Filing and managing insurance claims can be a complex process, but it’s essential for contractors to understand their rights and responsibilities. By following these steps, contractors can ensure that their claims are processed efficiently and that they receive the compensation they deserve.

    Documentation Required

    When filing a claim, contractors will need to provide the insurance company with the following documentation:

    • A detailed description of the loss or damage.
    • Photographs or videos of the damage.
    • Estimates for repairs or replacements.
    • Proof of ownership of the damaged property.
    • Any other documentation that may be relevant to the claim.

    Steps to Follow

    Once the necessary documentation has been gathered, contractors should follow these steps to file a claim:

    1. Contact the insurance company and report the loss or damage.
    2. Provide the insurance company with the required documentation.
    3. Cooperate with the insurance company’s investigation.
    4. Review the insurance company’s settlement offer.
    5. Negotiate with the insurance company if necessary.
    6. Accept the settlement offer or file a lawsuit if necessary.

    Common Challenges

    Contractors may face a number of challenges when filing and managing insurance claims. Some of the most common challenges include:

    • Denial of coverage.
    • Underpayment of claims.
    • Delays in processing claims.
    • Fraudulent claims.

    Contractors can overcome these challenges by:

    • Understanding their insurance policies.
    • Working with a reputable insurance company.
    • Documenting their losses carefully.
    • Being prepared to negotiate with the insurance company.

    By following these tips, contractors can increase their chances of getting their insurance claims approved and receiving the compensation they deserve.

    Wrap-Up

    In the ever-changing business environment, having a solid understanding of insurance coverage is paramount for small business insurance contractors. This guide has provided a comprehensive overview of the key aspects to consider when selecting and managing insurance policies. By leveraging the information presented here, contractors can make informed decisions that protect their businesses and foster their growth.

    Question & Answer Hub

    What types of insurance coverage are essential for small business contractors?

    General liability insurance, property insurance, and workers’ compensation insurance are fundamental coverage options for small business contractors.

    How can I determine the appropriate coverage limits for my business?

    Assess your business’s potential risks, consider industry standards, and consult with an insurance professional to establish suitable coverage limits.

    What factors should I consider when comparing insurance providers?

    Coverage options, premiums, customer service, and financial stability are key factors to evaluate when comparing insurance providers.

    Why is it important to understand insurance policy language?

    Understanding policy language ensures that you fully comprehend the coverage provided, exclusions, and your obligations as the policyholder.