Tag: financial planning

  • Discover the Best Life Insurance Policies Without Medical Exams: A Guide to Peace of Mind

    Discover the Best Life Insurance Policies Without Medical Exams: A Guide to Peace of Mind

    In the realm of financial planning, securing life insurance is paramount. And for those seeking a hassle-free and time-saving option, best life insurance policies without medical exam emerge as a beacon of convenience. Dive into this comprehensive guide to unravel the intricacies of these policies, ensuring you make an informed decision to safeguard your loved ones’ future.

    Delve into the different types of no-exam life insurance policies, their coverage options, and limitations. Understand the eligibility criteria and the simplified application process, which eliminates the need for intrusive medical exams. Explore the reputable providers offering these policies and compare quotes to find the best fit for your needs.

    Policy Types and Features

    Life insurance policies without medical exams offer a convenient and accessible way to protect your loved ones financially in the event of your passing. These policies come in various types, each with its own set of features and benefits.

    The most common type of life insurance policy without a medical exam is term life insurance. Term life insurance provides coverage for a specific period, such as 10, 20, or 30 years. If you pass away during the policy term, your beneficiaries will receive a death benefit.

    Term life insurance premiums are typically lower than other types of life insurance, making it an affordable option for many people.

    Another type of life insurance policy without a medical exam is whole life insurance. Whole life insurance provides coverage for your entire life, as long as you continue to pay the premiums. Whole life insurance premiums are typically higher than term life insurance premiums, but the policy also includes a cash value component that grows over time.

    You can borrow against the cash value or withdraw it for any reason.

    Finally, there is also universal life insurance. Universal life insurance is a type of permanent life insurance that offers flexible premiums and death benefits. You can increase or decrease your coverage amount and premiums as your needs change. Universal life insurance premiums are typically higher than term life insurance premiums, but they are also more flexible.

    Comparison Table

    The following table compares the key features of the different types of life insurance policies without medical exams:

    Feature Term Life Insurance Whole Life Insurance Universal Life Insurance
    Coverage Period Specific period (e.g., 10, 20, 30 years) Entire life Flexible
    Premiums Typically lower Typically higher Flexible
    Death Benefit Fixed Fixed Flexible
    Cash Value Component No Yes Yes

    Eligibility and Application Process

    Best life insurance policies without medical exam

    No-exam life insurance policies offer a simplified application process that eliminates the need for medical examinations. To be eligible for these policies, applicants typically need to meet certain criteria, such as age, health status, and occupation.

    The application process for no-exam life insurance is generally straightforward. Applicants can usually complete the application online or over the phone in a matter of minutes. They will be asked to provide basic information about themselves, such as their name, address, and date of birth.

    They will also be asked to answer a series of health questions. These questions are designed to help the insurance company assess the applicant’s risk level.

    Alternative Underwriting Methods

    Since no medical exam is required, insurance companies use alternative underwriting methods to assess risk. These methods may include:

    • Medical Information Bureau (MIB) Reports:These reports contain information about an applicant’s past medical history, including any claims they have filed.
    • Prescription Drug Monitoring Programs (PDMPs):These programs track prescriptions for controlled substances, which can provide insights into an applicant’s health status.
    • Social Media Screening:Insurance companies may review an applicant’s social media profiles to gather information about their lifestyle and health habits.
    • Motor Vehicle Records (MVRs):These records can provide information about an applicant’s driving history, which can be an indicator of risk.

    Coverage Options and Limitations

    Insurance exam life medical term aaa bestow 2021 vs

    No-exam life insurance policies typically offer a range of coverage options to meet different needs. These options include:

    • Death benefits:The primary coverage provided by life insurance, which pays out a lump sum to beneficiaries upon the insured person’s death.
    • Riders:Additional coverage options that can be added to a policy for an additional premium, such as coverage for accidental death, dismemberment, or terminal illness.
    • Exclusions:Certain events or conditions that are not covered by the policy, such as death due to suicide, war, or high-risk activities.

    It’s important to carefully review the policy details to understand the specific coverage options, limitations, and exclusions that apply to your policy.

    Coverage Amounts and Premiums

    No-exam life insurance policies typically offer lower coverage amounts compared to policies with medical exams. This is because the insurer takes on more risk by not requiring a medical exam, so they limit the amount of coverage they are willing to provide.

    Premiums for no-exam life insurance policies are also generally higher than for policies with medical exams, as the insurer is charging for the additional risk they are taking.

    It’s important to compare the coverage amounts and premiums of no-exam life insurance policies to similar policies with medical exams to make sure you are getting the best value for your money.

    Reputable Providers and Quotes: Best Life Insurance Policies Without Medical Exam

    When selecting a no-exam life insurance provider, it’s crucial to choose a reputable company with a strong financial standing and a history of providing excellent customer service.

    Here are some of the leading providers in the industry:

    • Haven Life: Known for its user-friendly online application process and competitive rates.
    • Ladder: Offers customizable policies with no medical exam or blood test required.
    • Bestow: Provides instant coverage decisions and a simple application process.
    • Fidelity Life: A well-established provider with a wide range of coverage options.
    • Ethos: Known for its fast and easy application process and competitive rates.

    Quote Comparison, Best life insurance policies without medical exam

    To help you compare quotes from different providers, consider factors such as your age, health, and desired coverage amount. Here’s a sample comparison table:

    Provider Age Health Status Coverage Amount Monthly Premium
    Haven Life 30 Excellent $500,000 $25
    Ladder 40 Good $750,000 $40
    Bestow 50 Fair $1,000,000 $60
    Fidelity Life 60 Poor $250,000 $80
    Ethos 35 Excellent $500,000 $28

    Remember, these are just sample quotes, and your actual premium may vary based on your specific circumstances.

    Factors to Consider

    When choosing a no-exam life insurance provider, consider the following factors:

    • Financial Stability: Ensure the provider has a strong financial rating from reputable agencies like AM Best or Standard & Poor’s.
    • Customer Service: Look for companies with positive customer reviews and a history of resolving claims promptly and efficiently.
    • Coverage Options: Choose a provider that offers a range of coverage options to meet your specific needs.
    • Application Process: Consider the simplicity and speed of the application process, especially if you prefer a hassle-free experience.

    Tips for Choosing the Best Policy
    Best life insurance policies without medical exam

    Understanding your individual needs and financial situation is paramount when selecting a no-exam life insurance policy. It’s essential to assess your current and future financial obligations, such as mortgage payments, family support, and end-of-life expenses. This will help you determine the appropriate coverage amount and policy term.

    Checklist for Evaluating No-Exam Life Insurance Policies

    • Coverage Amount:Determine the amount of coverage you need to meet your financial obligations.
    • Policy Term:Choose a policy term that aligns with your financial goals and the length of time you need coverage.
    • Premium Rates:Compare premium rates from different providers to find the most affordable option that meets your needs.
    • Exclusions and Limitations:Review the policy’s exclusions and limitations to ensure they align with your expectations.
    • Company Reputation:Research the reputation and financial stability of the insurance provider.
    • Customer Service:Consider the provider’s customer service record and availability of support.

    Comparing Policies and Making an Informed Decision

    Once you have a shortlist of potential policies, it’s important to compare them carefully. Consider the following factors:

    • Coverage Features:Compare the coverage amounts, policy terms, and exclusions of each policy.
    • Premium Rates:Calculate the annual premium cost for each policy to determine the most affordable option.
    • Financial Stability:Research the financial strength and stability of the insurance providers to ensure they can fulfill their obligations.
    • Customer Reviews:Read customer reviews and testimonials to gain insights into the provider’s service and claims handling.

    By carefully evaluating and comparing no-exam life insurance policies, you can make an informed decision that meets your specific needs and financial situation.

    Last Recap

    Remember, choosing the best life insurance policy without a medical exam requires careful consideration of your personal circumstances and financial goals. By following the expert guidance provided in this guide, you can navigate the complexities of these policies with confidence.

    Secure your peace of mind today and ensure your loved ones are protected in the face of life’s uncertainties.

    FAQ Insights

    What are the eligibility criteria for no-exam life insurance policies?

    Eligibility criteria vary among providers, but generally include factors such as age, health, and lifestyle habits.

    How does the application process differ for no-exam life insurance policies?

    The application process is simplified, eliminating the need for medical exams. Instead, you may be asked to provide basic health information and answer lifestyle questions.

    What are the coverage options available for no-exam life insurance policies?

    Coverage options include death benefits, riders for additional coverage, and exclusions for specific circumstances.

  • Cash App Early Direct Deposit: Get Your Money Sooner

    Cash App Early Direct Deposit: Get Your Money Sooner

    Cash app early direct deposit – With Cash App’s early direct deposit feature, you can bid farewell to the agonizing wait for payday. This revolutionary service puts your hard-earned money in your pocket up to two days faster, empowering you with unparalleled financial flexibility and peace of mind.

    Prepare to dive into a comprehensive exploration of Cash App’s early direct deposit, where we’ll unravel its benefits, eligibility criteria, and potential risks. We’ll also guide you through the seamless setup process and compare it to other early direct deposit services.

    Get ready to unlock the secrets of financial freedom with Cash App.

    Benefits of Cash App Early Direct Deposit

    Cash app early direct deposit

    Cash App’s Early Direct Deposit feature offers a host of benefits that can significantly enhance your financial experience.

    One of the most notable advantages is the convenience it provides. With Early Direct Deposit, you can receive your paycheck or government benefits up to two days earlier than the standard processing time. This means no more waiting around for funds to clear, allowing you to access your money sooner.

    Time-Saving Advantages

    • Eliminates the need to wait for standard processing times, saving you valuable time.
    • Provides immediate access to funds, enabling you to make purchases or pay bills promptly.
    • Reduces the stress associated with waiting for funds to become available.

    Financial Benefits

    • Provides access to funds sooner, allowing you to manage your finances more effectively.
    • Reduces the risk of overdraft fees by ensuring timely access to funds.
    • Provides a buffer for unexpected expenses or emergencies.

    Eligibility and Requirements for Early Direct Deposit: Cash App Early Direct Deposit

    Cash app early direct deposit

    Cash App’s early direct deposit feature is available to eligible Cash App users who meet certain requirements. To qualify, you must have a qualifying bank account linked to your Cash App account and meet specific income thresholds.

    Eligibility Criteria

    To be eligible for early direct deposit, you must:

    • Have a qualifying bank account linked to your Cash App account.
    • Meet specific income thresholds set by Cash App.

    Activation Process

    Once you meet the eligibility criteria, you can activate the early direct deposit feature by following these steps:

    1. Open the Cash App on your mobile device.
    2. Tap the “Banking” tab.
    3. Tap the “Direct Deposit” option.
    4. Follow the on-screen instructions to link your bank account and activate the early direct deposit feature.

    Comparison with Other Early Direct Deposit Services

    Cash App’s early direct deposit service stands out in the market, offering competitive advantages over similar services from other providers. Let’s delve into a detailed comparison to highlight the key differences and help you make an informed decision.

    Eligibility Requirements

    Cash App boasts a straightforward eligibility process. With a valid bank account and Social Security number, you can easily sign up for the service. In contrast, some other providers may impose additional requirements, such as a minimum account balance or direct deposit frequency.

    Deposit Times

    Cash App delivers funds up to two days earlier than your scheduled payday. This feature provides a significant advantage, allowing you to access your hard-earned money sooner. Other services may offer varying deposit times, ranging from a few hours to a day earlier.

    Fees, Cash app early direct deposit

    Cash App’s early direct deposit service is absolutely free. You can enjoy the convenience of receiving your paycheck early without incurring any additional charges. However, some other providers may charge a fee for this service, typically ranging from a few dollars to a percentage of the deposited amount.

    Advantages of Cash App

    • No fees for early direct deposit
    • Fast and reliable deposit times
    • Easy eligibility requirements

    Disadvantages of Cash App

    • Limited availability to certain banks
    • No physical branches for in-person support

    Advantages of Other Services

    • May offer earlier deposit times (within hours)
    • Wider availability across various banks
    • Some services provide additional financial services, such as budgeting tools or savings accounts

    Disadvantages of Other Services

    • May charge fees for early direct deposit
    • Slower deposit times compared to Cash App
    • Stricter eligibility requirements

    Potential Risks and Considerations

    While early direct deposit offers convenience and flexibility, it also comes with potential risks that users should be aware of.

    One of the primary concerns is the risk of overdraft fees. If the funds from your direct deposit are not available immediately, you may incur overdraft fees if you attempt to make purchases or withdrawals that exceed your current balance.

    It is essential to carefully manage your finances and plan accordingly to avoid this pitfall.

    Financial Planning and Managing Expectations

    To minimize risks associated with early direct deposit, financial planning and managing expectations are crucial. By understanding the potential delays in fund availability and budgeting accordingly, you can avoid overdraft fees and other financial setbacks.

    It is also important to note that early direct deposit services may have specific terms and conditions that can vary between providers. Carefully reviewing these terms and conditions before enrolling in an early direct deposit service is essential to ensure that you are aware of any potential risks or limitations.

    Tips for Avoiding Financial Pitfalls

    • Monitor your account balance regularly:Keep track of your account balance to avoid overdrafts.
    • Set up overdraft protection:Consider setting up overdraft protection with your bank to minimize the risk of overdraft fees.
    • Use budgeting tools:Utilize budgeting tools or apps to track your income and expenses, ensuring that you have sufficient funds available before making purchases.
    • Plan for potential delays:Be aware of the potential delays in fund availability and plan accordingly to avoid financial disruptions.
    • Consider alternative early direct deposit options:Explore alternative early direct deposit services that offer more flexible terms or faster fund availability.

    How to Use Cash App for Early Direct Deposit

    Cash App makes it easy to receive your paycheck up to two days earlier with its Early Direct Deposit feature. Here’s a step-by-step guide to help you get started:

    Linking Your Bank Account

    Before you can set up Early Direct Deposit, you’ll need to link your bank account to your Cash App account. To do this:

    • Open the Cash App and tap the “Banking” tab.
    • Select “Add Bank” and follow the prompts to connect your bank account.

    Setting Up Early Direct Deposit

    Once your bank account is linked, you can set up Early Direct Deposit by following these steps:

    • Tap the “Banking” tab again.
    • Scroll down and select “Early Direct Deposit.”
    • Follow the on-screen instructions to set up the feature.

    Receiving Early Deposits

    Once you’ve set up Early Direct Deposit, you’ll start receiving your paycheck up to two days earlier. The funds will be deposited directly into your Cash App balance, and you can access them immediately.

    Troubleshooting Tips

    If you’re having issues with Early Direct Deposit, try the following troubleshooting tips:

    • Ensure that your bank account is linked correctly.
    • Check that your employer supports Early Direct Deposit.
    • Contact Cash App support for assistance.

    Conclusion

    Cash deposit

    Cash App’s early direct deposit is a game-changer for those seeking financial agility. Whether you’re planning ahead or simply want to avoid the stress of late payments, this service empowers you to take control of your finances and live life on your terms.

    Embrace the convenience, save time, and experience the financial freedom that comes with getting your money sooner.

    Question & Answer Hub

    Is there a fee for using Cash App’s early direct deposit feature?

    No, Cash App does not charge any fees for using its early direct deposit service.

    How long does it take to set up early direct deposit with Cash App?

    Setting up early direct deposit with Cash App is quick and easy. Once you link your qualifying bank account, you can typically receive your deposits up to two days sooner.

    What are the eligibility requirements for early direct deposit with Cash App?

    To be eligible for early direct deposit with Cash App, you must have a qualifying bank account and meet certain income thresholds. Check Cash App’s website for specific requirements.

  • Best Rated Whole Life Insurance for Seniors: A Comprehensive Guide

    Best Rated Whole Life Insurance for Seniors: A Comprehensive Guide

    Embark on a journey to discover the best rated whole life insurance for seniors, a financial lifeline that provides peace of mind and enduring protection. As you navigate the complexities of aging, secure your future with a policy tailored to your unique needs, offering comprehensive coverage and exceptional financial strength.

    Our in-depth guide unveils the secrets of whole life insurance, empowering you to make informed decisions. Dive into the nuances of coverage options, premiums, customer service, and policy provisions, ensuring you choose a plan that aligns perfectly with your aspirations.

    Company Rankings and Financial Strength

    Best rated whole life insurance for seniors

    When selecting a whole life insurance policy for seniors, it is crucial to consider the company’s financial strength and rankings. These factors provide insights into the insurer’s ability to meet its obligations and provide long-term financial security for policyholders.

    Top-Rated Whole Life Insurance Companies for Seniors

    The following table compares the top-rated whole life insurance companies for seniors based on financial strength ratings from leading independent agencies:

    Company Financial Strength Rating
    Northwestern Mutual A++ (Superior)
    MassMutual A++ (Superior)
    New York Life A++ (Superior)
    Guardian Life A+ (Excellent)
    Prudential A+ (Excellent)

    Companies with higher financial strength ratings are generally considered more stable and reliable, indicating a lower risk of default or financial distress.

    Coverage and Benefits: Best Rated Whole Life Insurance For Seniors

    Insurance seniors aarp

    Whole life insurance policies provide a range of coverage options and benefits that can meet the specific needs of seniors. These policies offer lifelong protection, with premiums and death benefits remaining constant throughout the policy term. Additionally, whole life insurance policies accumulate cash value, which can be borrowed against or withdrawn for various purposes.

    Some of the unique features and riders that may be beneficial for seniors include:

    Guaranteed Issue Whole Life Insurance

    • Guaranteed issue whole life insurance policies do not require a medical exam, making them accessible to seniors who may have pre-existing health conditions.
    • However, these policies typically have lower death benefits and higher premiums compared to medically underwritten policies.

    Simplified Issue Whole Life Insurance

    • Simplified issue whole life insurance policies require only a few basic health questions and no medical exam.
    • They offer higher death benefits and lower premiums compared to guaranteed issue policies, but still have lower coverage limits than medically underwritten policies.

    Chronic Illness Rider, Best rated whole life insurance for seniors

    • A chronic illness rider provides an accelerated death benefit if the insured is diagnosed with a qualifying chronic illness.
    • This benefit can be used to cover medical expenses, long-term care costs, or other expenses associated with a chronic illness.

    Terminal Illness Rider

    • A terminal illness rider provides an accelerated death benefit if the insured is diagnosed with a terminal illness with a life expectancy of less than 12 months.
    • This benefit can be used to cover end-of-life expenses, such as hospice care, funeral costs, or outstanding debts.

    Waiver of Premium Rider

    • A waiver of premium rider waives the policy premiums if the insured becomes totally disabled.
    • This benefit ensures that the policy remains in force even if the insured is unable to work and pay the premiums.

    Comparison of Coverage Options and Benefits

    Coverage Options and Benefits of Top-Rated Whole Life Insurance Policies
    Policy Death Benefit Cash Value Guaranteed Issue Simplified Issue Chronic Illness Rider Terminal Illness Rider Waiver of Premium Rider
    Policy A Up to $500,000 Accumulates at a fixed rate No Yes Yes Yes Yes
    Policy B Up to $1,000,000 Accumulates at a variable rate No Yes No Yes No
    Policy C Up to $2,000,000 Accumulates at a variable rate Yes No Yes Yes Yes

    Cost and Premiums

    The cost of whole life insurance premiums for seniors is influenced by several factors, including age, health, and the amount of coverage desired. As you age, your premiums will typically increase due to the higher risk of mortality. Similarly, if you have a history of health problems, your premiums may be higher than someone with a clean bill of health.

    The amount of coverage you choose will also impact your premiums, with higher coverage amounts leading to higher premiums.

    To give you a better idea of the costs involved, we’ve compared the premium rates of the top-rated whole life insurance policies for seniors. The table below summarizes the premium costs and payment options for each policy.

    Premium Rates and Payment Options

    Company Premium Rate (Monthly) Payment Options
    AIG $150 Monthly, Quarterly, Semi-Annually, Annually
    Mutual of Omaha $175 Monthly, Quarterly, Semi-Annually, Annually
    Northwestern Mutual $200 Monthly, Quarterly, Semi-Annually, Annually
    Pacific Life $225 Monthly, Quarterly, Semi-Annually, Annually
    Transamerica $250 Monthly, Quarterly, Semi-Annually, Annually

    Customer Service and Reviews

    Best rated whole life insurance for seniors

    Exceptional customer service is paramount in choosing a whole life insurance provider. It ensures that your queries and concerns are addressed promptly and efficiently. Positive policyholder reviews indicate a company’s commitment to customer satisfaction.

    Customer Reviews and Testimonials

    Reputable sources like J.D. Power and Consumer Reports provide valuable insights into customer experiences. These organizations conduct surveys and gather feedback from policyholders, evaluating their satisfaction levels with various aspects of service, such as responsiveness, claim handling, and overall experience.

    Top-Rated Whole Life Insurance Companies: Customer Service Ratings
    Company J.D. Power Rating Consumer Reports Rating
    Northwestern Mutual 880 85
    MassMutual 875 83
    New York Life 870 82

    Policy Details and Provisions

    Whole life insurance policies come with a variety of provisions and terms that determine the coverage, benefits, and costs. Understanding these provisions is crucial for making informed decisions about your policy.

    Whole life insurance policies typically include the following provisions:

    Death Benefit

    The death benefit is the amount of money that will be paid to your beneficiaries upon your death. The death benefit is usually a fixed amount, but it can be increased or decreased over time through policy riders.

    Cash Value

    The cash value is a savings component that grows over time on a tax-deferred basis. You can borrow against the cash value or withdraw it for any reason, but doing so will reduce the death benefit.

    Premiums

    Premiums are the payments you make to keep your policy in force. Premiums are typically fixed for the life of the policy, but they can increase if you add riders or change the coverage amount.

    Policy Options and Riders

    In addition to the basic provisions, whole life insurance policies can also include a variety of policy options and riders. These options and riders can provide additional coverage or benefits, such as:

    • Guaranteed insurability riders: These riders allow you to increase your coverage amount without having to undergo a medical exam.
    • Accidental death and dismemberment riders: These riders provide additional coverage if you die or are dismembered in an accident.
    • Waiver of premium riders: These riders waive your premium payments if you become disabled.

    Table of Policy Details and Provisions

    The following table Artikels the policy details and provisions of the top-rated whole life insurance policies for seniors:

    Company Death Benefit Cash Value Premiums
    Company A Up to $1 million Up to $500,000 Starting at $100 per month
    Company B Up to $2 million Up to $750,000 Starting at $125 per month
    Company C Up to $3 million Up to $1 million Starting at $150 per month

    Closing Summary

    In the twilight of your years, secure your legacy with the best rated whole life insurance for seniors. With a policy that stands the test of time, you can rest assured that your loved ones will be protected and your financial future is in safe hands.

    Embrace the peace of mind that comes with knowing you’ve made a wise investment in your well-being and the well-being of those who matter most.

    FAQ Section

    What factors should I consider when choosing a whole life insurance policy?

    Consider your age, health, lifestyle, financial situation, and long-term goals. A policy with adequate coverage, affordable premiums, and favorable policy provisions is crucial.

    How do I compare different whole life insurance policies?

    Compare coverage options, premiums, financial strength ratings, customer service, and policy provisions. Our guide provides a detailed comparison table to assist you.

    What are the benefits of whole life insurance for seniors?

    Whole life insurance offers lifelong coverage, guaranteed cash value growth, and tax-deferred earnings, providing financial security and peace of mind during your retirement years.

  • Uncover the Secrets to Affordable Life Insurance: A Guide to Cheap Life Insurance Quotes

    Uncover the Secrets to Affordable Life Insurance: A Guide to Cheap Life Insurance Quotes

    Embark on a journey to discover the world of cheap life insurance quotes, where affordability meets peace of mind. Dive into a comprehensive exploration of life insurance options, empowering you to make informed decisions that safeguard your loved ones without breaking the bank.

    From comparing quotes across multiple insurers to understanding the nuances of life insurance riders, this guide will equip you with the knowledge to navigate the complexities of life insurance and secure the best coverage for your unique needs.

    Affordable Life Insurance Coverage

    Cheap life insurance quotes

    In today’s uncertain world, securing your family’s financial future is paramount. Affordable life insurance provides peace of mind, knowing that your loved ones will be protected in the event of your untimely demise. With a wide range of options available, finding cheap life insurance that meets your specific needs is within reach.

    The cost of life insurance premiums is influenced by several factors, including your age, health, lifestyle habits, and the amount of coverage you need. Understanding these factors can help you make informed decisions and potentially reduce your costs.

    Factors Influencing Life Insurance Premiums

    • Age:As you age, your risk of health issues increases, leading to higher premiums.
    • Health:Your overall health and medical history play a significant role in determining your premiums. Pre-existing conditions can increase your risk and, consequently, your costs.
    • Lifestyle Habits:Engaging in risky behaviors, such as smoking or excessive alcohol consumption, can raise your premiums.
    • Amount of Coverage:The higher the coverage amount you need, the more you’ll pay in premiums.

    Tips to Reduce Life Insurance Costs

    • Compare Quotes:Obtain quotes from multiple insurers to compare rates and find the best deal.
    • Consider Term Life Insurance:Term life insurance provides coverage for a specific period, often at a lower cost than whole life insurance.
    • Improve Your Health:Maintaining a healthy lifestyle, including regular exercise and a balanced diet, can improve your health rating and reduce premiums.
    • Quit Smoking:Smoking significantly increases your risk of health problems, leading to higher premiums. Quitting can save you money on insurance.
    • Increase Your Deductible:Choosing a higher deductible on your policy can lower your premiums.

    By understanding the factors that influence life insurance premiums and implementing cost-saving strategies, you can secure affordable coverage that meets your needs without breaking the bank.

    Comparing Quotes from Multiple Insurers

    Securing affordable life insurance coverage is a crucial step in safeguarding your loved ones’ financial future. To ensure you make an informed decision, it’s essential to compare quotes from various insurance providers. This comprehensive guide will empower you with the knowledge and strategies to gather, compare, and select the most suitable life insurance policy that meets your unique needs and budget.

    Gathering Life Insurance Quotes

    The first step in comparing quotes is to gather them from multiple insurance providers. You can do this by:

    • Online Quote Comparison Tools:Utilize online platforms that allow you to compare quotes from several insurers simultaneously.
    • Insurance Brokers:Consult with an independent insurance broker who represents multiple insurers and can provide unbiased advice.
    • Direct Contact:Reach out to individual insurance companies directly to request quotes.

    Comparing Life Insurance Quotes

    Once you have gathered quotes from different insurers, it’s time to compare them carefully. Consider the following factors:

    • Coverage Amount:Ensure the coverage amount is sufficient to meet your family’s financial needs in the event of your untimely demise.
    • Premiums:Compare the monthly or annual premiums charged by each insurer. Remember, lower premiums don’t always indicate a better deal.
    • Policy Terms:Understand the policy terms, including the length of the coverage, the waiting period, and any exclusions or limitations.
    • Riders and Benefits:Consider additional riders or benefits, such as accidental death benefits or disability income riders, that may enhance the coverage.
    • Financial Strength of the Insurer:Research the financial stability and reputation of each insurance provider to ensure they have the ability to fulfill their obligations.

    Advantages and Disadvantages of Different Insurers

    Each insurance provider offers unique advantages and disadvantages. Some insurers may specialize in certain types of life insurance policies, while others may offer competitive premiums or comprehensive coverage options. By understanding the strengths and weaknesses of different insurers, you can make an informed decision that aligns with your specific requirements.

    Understanding Life Insurance Riders and Benefits

    Seniors affordable

    Life insurance riders are optional add-ons that can enhance the coverage of your policy and provide additional benefits. They offer a range of options to tailor your policy to your specific needs and circumstances.

    Types of Life Insurance Riders

    There are several types of life insurance riders available, each providing unique benefits. Some common riders include:

    • Accidental Death Benefit:Provides an additional payout if the insured person dies as a result of an accident.
    • Critical Illness Coverage:Provides a lump sum payment if the insured person is diagnosed with a covered critical illness, such as cancer or heart disease.
    • Waiver of Premium:Exempts the insured person from paying premiums if they become disabled and unable to work.
    • Return of Premium:Refunds a portion or all of the premiums paid if the insured person outlives the policy term.
    • Child Rider:Provides coverage for the insured person’s children.

    Benefits and Drawbacks of Riders

    Adding riders to your life insurance policy can provide valuable benefits. However, it is important to consider the potential drawbacks as well:

    Benefits:

    • Increased coverage and financial protection
    • Tailored coverage to meet specific needs
    • Peace of mind knowing that loved ones are protected

    Drawbacks:

    • Increased premiums
    • Potential restrictions or limitations on coverage
    • May not be necessary for all individuals

    Table of Common Riders and Impact on Premiums

    The following table Artikels some of the common riders offered by insurers and their impact on premiums:

    Rider Benefit Impact on Premium
    Accidental Death Benefit Additional payout for accidental death Increases premium by 10-20%
    Critical Illness Coverage Lump sum payment for covered critical illness Increases premium by 15-25%
    Waiver of Premium Exemption from premium payments if disabled Increases premium by 5-10%
    Return of Premium Refund of premiums if insured outlives policy term Increases premium by 10-15%
    Child Rider Coverage for insured person’s children Increases premium by 5-10% per child

    Applying for Cheap Life Insurance

    Cheap life insurance quotes

    Obtaining affordable life insurance is crucial for safeguarding your loved ones’ financial well-being. Applying for cheap life insurance involves a straightforward process, but meticulous preparation can enhance your chances of securing favorable rates.

    Required Information and Documentation

    • Personal information: Name, address, date of birth, Social Security number
    • Health history: Medical conditions, medications, surgeries, lifestyle habits
    • Financial information: Income, assets, debts
    • Beneficiary information: Name, relationship, percentage of coverage
    • Proof of insurability: Medical exam, doctor’s report, prescription records

    Steps to Apply

    1. Gather information:Collect the necessary information and documentation Artikeld above.
    2. Compare quotes:Obtain quotes from multiple insurers to find the most affordable options.
    3. Choose a policy:Select the policy that best meets your needs and budget.
    4. Complete the application:Provide accurate and complete information on the application form.
    5. Submit the application:Send the completed application along with supporting documentation to the insurer.
    6. Underwriting process:The insurer will review your application and determine your risk level.
    7. Approval and policy issuance:If approved, the insurer will issue your life insurance policy.

Tips for Securing Affordable Rates

  • Maintain a healthy lifestyle: Non-smokers and individuals with good health habits typically qualify for lower rates.
  • Compare multiple quotes: Shopping around can help you find the most competitive rates.
  • Consider a smaller policy: A lower death benefit amount can result in lower premiums.
  • Increase your coverage gradually: Starting with a smaller policy and gradually increasing coverage as your financial situation improves can help keep costs manageable.

Additional Considerations for Cheap Life Insurance

To secure cheap life insurance quotes, it’s crucial to consider factors that influence premium costs. Medical exams and health screenings play a significant role in assessing your health profile, impacting the insurer’s risk assessment. Age, lifestyle habits, and family history also come into play.

Medical Exams and Health Screenings

Life insurance companies often require medical exams and health screenings to evaluate your overall health. These tests provide valuable insights into your medical history, current health status, and potential risk factors. Based on the results, insurers determine your health classification, which significantly influences your premium rates.

Age

Age is a primary factor in life insurance pricing. Younger individuals typically qualify for lower premiums due to their lower perceived risk of mortality. As you age, the risk of health issues increases, leading to higher premium costs.

Lifestyle Habits, Cheap life insurance quotes

Your lifestyle choices can have a profound impact on your life insurance rates. Smoking, excessive alcohol consumption, and poor dietary habits can increase your health risks, resulting in higher premiums. Conversely, maintaining a healthy lifestyle, including regular exercise and a balanced diet, can qualify you for lower rates.

Family History

Your family’s medical history can also influence your life insurance premiums. If you have a strong family history of chronic diseases, such as heart disease or cancer, you may face higher premium costs. This is because insurers may perceive you as having a higher risk of developing similar conditions.

Maintaining a Healthy Lifestyle

To qualify for cheap life insurance rates, it’s essential to maintain a healthy lifestyle. Regular exercise, a balanced diet, and avoiding harmful habits like smoking and excessive alcohol consumption can significantly improve your health and reduce your risk factors. This, in turn, can lead to lower life insurance premiums.

Final Wrap-Up: Cheap Life Insurance Quotes

As you delve into the realm of cheap life insurance quotes, remember that affordability is not just about finding the lowest premium. It’s about finding the right balance between coverage, cost, and your personal circumstances. By understanding the factors that influence premiums, comparing quotes diligently, and exploring the benefits of riders, you can unlock the secrets to securing cheap life insurance that truly protects your financial future.
Answers to Common Questions

What factors influence the cost of life insurance premiums?

Age, health, lifestyle habits, occupation, and family history all play a role in determining life insurance premiums.

How can I reduce life insurance costs without compromising coverage?

Consider term life insurance over whole life insurance, opt for higher deductibles, and improve your overall health and lifestyle.

What are the advantages of adding riders to a life insurance policy?

Riders can provide additional coverage for specific events, such as accidental death, critical illness, or disability, enhancing the protection provided by your policy.

  • Best Online Term Insurance: A Comprehensive Guide to Affordable Protection

    Best Online Term Insurance: A Comprehensive Guide to Affordable Protection

    In the realm of financial security, best online term insurance stands as a beacon of protection, offering a lifeline of peace of mind in the face of life’s uncertainties. With its unparalleled convenience, tailored coverage, and competitive premiums, online term insurance has revolutionized the way we safeguard our loved ones and ensure their well-being.

    From understanding the intricacies of term insurance to navigating the complexities of choosing the right provider, this comprehensive guide will illuminate the path to finding the best online term insurance that meets your unique needs and budget.

    Overview of Best Online Term Insurance

    Term insurance is a type of life insurance that provides coverage for a specific period, such as 10, 20, or 30 years. If the insured person dies during the term, the beneficiaries will receive a death benefit. Term insurance is typically less expensive than other types of life insurance, such as whole life insurance, because it does not have a cash value component.

    Online term insurance has become increasingly popular in recent years. This is because it is convenient, affordable, and easy to compare quotes from different insurers. However, there are also some disadvantages to purchasing term insurance online, such as the lack of personal interaction with an agent and the potential for fraud.

    Advantages of Purchasing Term Insurance Online

    • Convenience: You can purchase term insurance online from the comfort of your own home.
    • Affordability: Online term insurance is typically less expensive than term insurance purchased through an agent.
    • Easy to compare quotes: You can easily compare quotes from different insurers online.
    • No need for a medical exam: Some online insurers offer term insurance without requiring a medical exam.

    Disadvantages of Purchasing Term Insurance Online

    • Lack of personal interaction: You will not have the opportunity to meet with an agent in person when you purchase term insurance online.
    • Potential for fraud: There is a potential for fraud when you purchase term insurance online, as you are not dealing with an agent face-to-face.
    • Limited coverage options: Online term insurance providers may not offer as many coverage options as traditional insurers.
    • May not be suitable for everyone: Online term insurance may not be suitable for everyone, such as those with complex financial needs or those who are not comfortable purchasing insurance online.

    Factors to Consider When Choosing an Online Term Insurance Provider

    Best online term insurance

    Selecting the right online term insurance provider is crucial for securing financial protection for your loved ones. Several key factors must be considered to ensure you make an informed decision that meets your specific needs.

    Financial Stability

    The financial stability of an insurance provider is paramount. Look for companies with a strong track record of paying claims and a high financial strength rating from reputable agencies like AM Best or Standard & Poor’s. This rating indicates the insurer’s ability to meet its financial obligations, ensuring that your beneficiaries will receive the promised death benefit.

    Customer Service

    Excellent customer service is essential for a smooth and hassle-free experience. Choose providers with a responsive and knowledgeable support team available through multiple channels, such as phone, email, and online chat. Read reviews from other policyholders to gauge the provider’s customer service quality.

    Policy Options

    Consider the range of policy options offered by the provider. This includes coverage amounts, policy terms, and riders. Ensure that the provider offers options that align with your financial goals and risk tolerance. Some providers may offer additional benefits, such as accelerated death benefits or guaranteed insurability options, which can enhance your coverage.

    Underwriting and Medical Exams

    Underwriting is the process by which an insurance company assesses your risk and determines your premium. Some providers use simplified underwriting, which involves answering a few health questions without requiring a medical exam. Others may require a full medical exam to assess your health and lifestyle factors more accurately.

    Understand the underwriting process and medical exam requirements of each provider to choose one that suits your circumstances.
    Top-Rated Online Term Insurance Providers

    When choosing an online term insurance provider, it’s important to consider factors such as coverage options, premiums, customer service, and financial strength. To help you make an informed decision, we’ve compiled a table comparing the top-rated online term insurance providers.

    Coverage Options

    The coverage options offered by online term insurance providers vary widely. Some providers offer basic coverage that includes death benefits only, while others offer more comprehensive coverage that includes additional benefits such as disability income protection and long-term care coverage.

    Premiums

    The premiums you pay for online term insurance will depend on a number of factors, including your age, health, and the amount of coverage you purchase. It’s important to compare quotes from multiple providers to find the best rate.

    Customer Service

    The quality of customer service you receive from an online term insurance provider is important. You want to make sure that you can easily get in touch with a customer service representative if you have any questions or need to file a claim.

    Financial Strength

    The financial strength of an online term insurance provider is important because it indicates the provider’s ability to pay claims. You want to make sure that you choose a provider that has a strong financial track record.

    Table of Top-Rated Online Term Insurance Providers

    Provider Coverage Options Premiums Customer Ratings
    Bestow Death benefits only Low Excellent
    Haven Life Death benefits only Low Excellent
    Ladder Death benefits, disability income protection, long-term care coverage Moderate Good
    Lemonade Death benefits, critical illness coverage, accidental death coverage Low Good
    Policygenius Death benefits, disability income protection, long-term care coverage Moderate Good

    Strengths and Weaknesses of Each Provider

    Bestow:Strengths: Low premiums, excellent customer service. Weaknesses: Limited coverage options.

    Haven Life:Strengths: Low premiums, excellent customer service. Weaknesses: Limited coverage options.

    Ladder:Strengths: Comprehensive coverage options, moderate premiums. Weaknesses: Customer service can be slow at times.

    Lemonade:Strengths: Low premiums, innovative coverage options. Weaknesses: Customer service can be slow at times.

    Policygenius:Strengths: Comprehensive coverage options, moderate premiums. Weaknesses: Customer service can be slow at times.

    Tips for Getting the Best Term Insurance Quotes

    Obtaining the most competitive term insurance quotes online requires careful consideration and a strategic approach. Here are some valuable tips to guide you in securing the best possible coverage at an affordable price:

    Importance of Comparing Quotes:

    • Never settle for the first quote you receive. It’s crucial to compare quotes from multiple providers to ensure you’re getting the best deal. Different insurers may offer varying premiums based on their underwriting criteria and risk assessment models.
    • Use online comparison tools or work with an independent insurance agent who represents multiple carriers. This allows you to quickly and easily compare coverage options and premiums from various providers.

    Factors Influencing Premiums:

    The cost of your term insurance premium is largely determined by three key factors:

    • Age:Generally, younger individuals pay lower premiums due to a lower perceived risk of mortality. As you age, the likelihood of health issues increases, leading to higher premiums.
    • Health:Your overall health and medical history play a significant role in determining your premium. Insurers assess your health through medical exams, blood tests, and questionnaires. A healthy lifestyle, including regular exercise and a balanced diet, can positively impact your insurability and premium rates.

    • Lifestyle:Certain risky behaviors, such as smoking or participating in dangerous hobbies, can increase your premium. Insurers view these activities as potential risk factors that may affect your life expectancy.

    Online Term Insurance Policy Features

    Best online term insurance

    Online term insurance policies offer various features and benefits that enhance their value. Understanding these features is crucial for making informed decisions about your coverage.

    Coverage Amounts

    Coverage amounts refer to the maximum payout your beneficiaries will receive upon your death. Selecting the right coverage amount is essential to ensure your loved ones are financially protected. Consider your income, expenses, debts, and future financial goals when determining the appropriate coverage.

    Policy Terms

    Policy terms specify the duration of your coverage. Common policy terms range from 10 to 30 years. Choose a policy term that aligns with your financial obligations and life stage. Longer policy terms provide more extended coverage but may come with higher premiums.

    Riders

    Riders are optional add-ons that can enhance your policy’s coverage. Common riders include:

    • Accidental Death Benefit: Provides an additional payout if your death results from an accident.
    • Waiver of Premium Rider: Waives your premium payments if you become disabled and unable to work.
    • Guaranteed Insurability Rider: Allows you to purchase additional coverage without undergoing a medical exam at predetermined intervals.

    Accelerated Death Benefits

    Accelerated death benefits allow you to access a portion of your death benefit while you are still living if you are diagnosed with a terminal illness or experience a critical health event. This benefit provides financial assistance for medical expenses or other needs during a difficult time.

    Living Benefits, Best online term insurance

    Living benefits provide access to a portion of your death benefit while you are still alive. These benefits can be used for long-term care expenses, chronic illnesses, or other qualifying events. Living benefits offer flexibility and financial security in the face of unexpected life circumstances.
    Concluding Remarks: Best Online Term Insurance

    Term insurance plan max life plus plans thus protected concept based community family

    As we conclude our exploration of best online term insurance, it is evident that this innovative solution has transformed the landscape of financial planning. By embracing the advantages of online insurance, you empower yourself to make informed decisions, optimize coverage, and secure the future of those who matter most.

    Remember, the best term insurance is the one that aligns seamlessly with your financial goals and provides unwavering protection against life’s unforeseen events.

    Answers to Common Questions

    What is the difference between term insurance and whole life insurance?

    Term insurance provides coverage for a specific period, while whole life insurance offers lifelong coverage and has a cash value component.

    How do I choose the right term insurance amount?

    Consider your income, expenses, debts, and family situation to determine the appropriate coverage amount.

    What factors affect term insurance premiums?

    Age, health, lifestyle, and coverage amount are key factors that influence premiums.

  • Working Capital Line of Credit: A Lifeline for Business Growth

    Working Capital Line of Credit: A Lifeline for Business Growth

    The working capital line of credit, a financial lifeline for businesses, empowers them to navigate cash flow challenges and seize growth opportunities. This flexible financing solution offers a revolving credit line that can be drawn upon as needed, providing businesses with the liquidity they need to thrive.

    Understanding the ins and outs of a working capital line of credit is crucial for businesses seeking to optimize their financial health. From eligibility criteria to repayment terms, this guide delves into the intricacies of this financing option, empowering businesses to make informed decisions and unlock their growth potential.

    Working Capital Line of Credit Overview

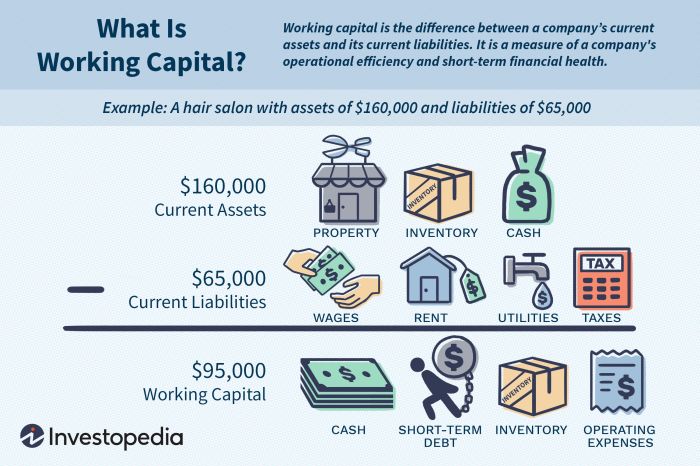
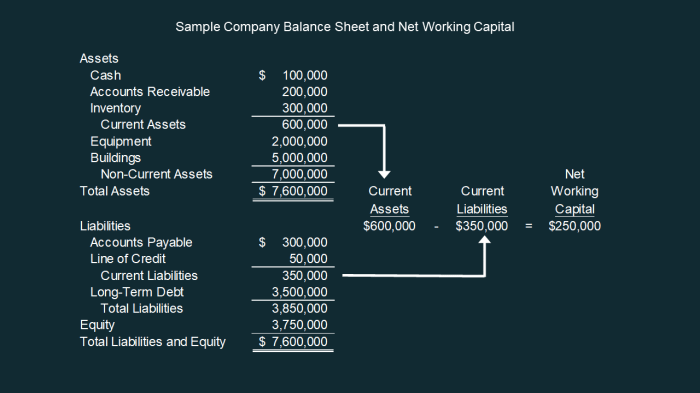
    A working capital line of credit (WCL) is a flexible source of financing that allows businesses to borrow funds to meet their short-term working capital needs. Working capital refers to the difference between a company’s current assets and current liabilities.

    A WCL provides businesses with access to additional funds to cover expenses such as inventory, accounts receivable, and operating costs.

    Businesses of all sizes and industries can benefit from a working capital line of credit. However, it is particularly useful for businesses that experience seasonal fluctuations in their cash flow, have high inventory levels, or are expanding rapidly. A WCL can provide a safety net for businesses to cover unexpected expenses or bridge gaps in cash flow.

    Advantages of Using a Working Capital Line of Credit

    • Flexibility:A WCL offers businesses flexibility in terms of the amount and timing of their borrowing. Businesses can draw on the line of credit as needed, and they only pay interest on the amount they borrow.
    • Quick Access to Funds:A WCL can provide businesses with quick access to funds, which can be crucial in meeting unexpected expenses or taking advantage of opportunities.
    • Improved Cash Flow:A WCL can help businesses improve their cash flow by providing them with additional funds to cover expenses and avoid late payments.
    • Reduced Borrowing Costs:A WCL can be a more cost-effective way to borrow money than other forms of financing, such as a term loan or invoice factoring.

    Disadvantages of Using a Working Capital Line of Credit

    • Interest Costs:Businesses will have to pay interest on the amount of money they borrow under a WCL. Interest rates can vary depending on the lender and the business’s creditworthiness.
    • Covenants and Restrictions:Lenders may impose covenants and restrictions on businesses that use a WCL. These covenants may limit the business’s ability to take on additional debt or make certain investments.
    • Personal Guarantees:In some cases, lenders may require personal guarantees from the business’s owners or directors as a condition of obtaining a WCL.

    Eligibility and Application Process

    Working capital line of credit

    Obtaining a working capital line of credit requires meeting specific criteria and following a defined application process. Lenders carefully evaluate applicants based on various factors to determine their eligibility and creditworthiness.

    Eligibility Criteria

    To qualify for a working capital line of credit, businesses typically need to:

    • Have a strong financial history with consistent revenue and profitability.
    • Maintain a healthy credit score and a low debt-to-income ratio.
    • Provide collateral or a personal guarantee to secure the loan.
    • Demonstrate a clear need for additional working capital.
    • Have a well-defined business plan outlining how the line of credit will be used.

    Application Process

    The application process for a working capital line of credit typically involves the following steps:

    1. Contacting a lender and submitting a formal application.
    2. Providing detailed financial information, including income statements, balance sheets, and cash flow projections.
    3. Submitting business plans, tax returns, and other supporting documents.
    4. Undergoing a credit check and financial analysis by the lender.
    5. Receiving a decision from the lender and negotiating loan terms if approved.

    Factors Considered by Lenders

    When evaluating an application for a working capital line of credit, lenders consider several factors, including:

    • The business’s financial performance and stability.
    • The experience and track record of the business owners.
    • The industry and market in which the business operates.
    • The purpose and intended use of the working capital.
    • The collateral or personal guarantee offered as security.

    Terms and Conditions

    Working capital lines of credit come with specific terms and conditions that borrowers must adhere to. These conditions Artikel the interest rates, repayment schedules, collateral requirements, and potential fees associated with the financing.

    Interest Rates

    Interest rates on working capital lines of credit vary depending on the lender, the borrower’s creditworthiness, and the current market conditions. Rates are typically floating, meaning they fluctuate with changes in the prime rate or other benchmark interest rates. Borrowers with strong credit histories and financial performance generally qualify for lower interest rates.

    Repayment Schedules

    Repayment schedules for working capital lines of credit can be structured to meet the borrower’s specific needs. Common repayment options include monthly installments, quarterly payments, or interest-only payments during the draw period, followed by principal and interest payments during the repayment period.

    Collateral Requirements

    Lenders may require collateral to secure working capital lines of credit, especially for larger loan amounts or borrowers with weaker credit profiles. Common forms of collateral include accounts receivable, inventory, and real estate. Providing collateral can help reduce the lender’s risk and potentially qualify the borrower for more favorable terms.

    Fees and Charges

    Working capital lines of credit may be subject to various fees and charges, including origination fees, commitment fees, and late payment fees. Origination fees are one-time charges assessed at the time the loan is established. Commitment fees are ongoing charges paid to the lender for maintaining the line of credit, even if it is not drawn upon.

    Late payment fees are charged if the borrower fails to make payments on time.

    Alternatives to Working Capital Lines of Credit

    Businesses seeking working capital have various financing options beyond working capital lines of credit. These alternatives offer distinct advantages and disadvantages, making it crucial to understand their nuances and select the most suitable option based on specific business needs.

    Key alternative financing options include term loans, invoice financing, and equity financing. Let’s explore each option in detail.

    Term Loans

    Term loans are traditional financing options where businesses borrow a lump sum of money from a lender and repay it over a fixed term, typically with monthly installments. Term loans often require collateral and can have longer application and approval processes compared to other alternatives.

    Advantages:

    • Fixed interest rates, providing predictable repayment costs.
    • Longer repayment terms, allowing for manageable monthly payments.
    • Can be used for a wide range of business purposes, including capital expenditures and working capital.

    Disadvantages:

    • Collateral requirements may limit accessibility for some businesses.
    • Longer application and approval processes compared to other alternatives.
    • Repayment schedules may not align with seasonal or fluctuating cash flows.

    Invoice Financing

    Invoice financing involves selling unpaid invoices to a financing company at a discount. The financing company advances a percentage of the invoice amount, providing businesses with immediate access to cash while waiting for customers to pay. Invoice financing is typically short-term and can be particularly useful for businesses with a high volume of accounts receivable.

    Advantages:

    • Provides quick access to cash, improving cash flow.
    • No collateral requirements, making it accessible to a wider range of businesses.
    • Flexible repayment terms that align with invoice payment schedules.

    Disadvantages:

    • Can be more expensive than other financing options, due to fees and discounts.
    • May require businesses to factor a significant portion of their invoices, limiting flexibility.
    • Can impact customer relationships if the financing company contacts customers directly for payment.

    Equity Financing

    Equity financing involves selling a portion of the business to investors in exchange for cash. This option can provide substantial funding but also dilutes ownership and may involve giving up some control of the business. Equity financing is typically considered a long-term financing solution.

    Advantages:

    • Provides access to large amounts of capital, suitable for significant growth or expansion.
    • No repayment obligations, as funds are not borrowed but invested.
    • Can enhance the credibility and reputation of the business by attracting investors.

    Disadvantages:

    • Dilutes ownership and may lead to loss of control over business decisions.
    • Can be complex and time-consuming to arrange.
    • Investors may expect a share of profits and may have influence on business operations.

    Best Practices for Utilizing a Working Capital Line of Credit

    Formula formulas calculation

    Effectively managing a working capital line of credit requires a disciplined approach and a clear understanding of its purpose and limitations. By following these best practices, businesses can maximize the benefits of this financing tool while minimizing potential risks.

    To optimize the use of a working capital line of credit, businesses should focus on cash flow management, financial forecasting, and maintaining a strong financial position.

    Cash Flow Management, Working capital line of credit

    Managing cash flow is critical for any business, but it becomes even more important when using a working capital line of credit. Businesses should implement a system for tracking cash inflows and outflows to ensure that they have sufficient liquidity to meet their obligations.

    This system should include:

    • A cash flow budget that projects future cash flows
    • Regular monitoring of accounts receivable and accounts payable
    • Procedures for managing inventory levels
    • A plan for dealing with unexpected expenses

    Financial Forecasting

    Financial forecasting is essential for businesses that want to use a working capital line of credit responsibly. By forecasting their financial needs, businesses can avoid overborrowing and ensure that they have sufficient funds to meet their obligations.

    Financial forecasting should include:

    • Preparing a detailed income statement
    • Projecting future cash flows
    • Identifying potential risks and opportunities
    • Developing contingency plans

    Maintaining a Strong Financial Position

    Maintaining a strong financial position is important for any business, but it is especially important for businesses that are using a working capital line of credit. Lenders will be more likely to approve a loan to a business with a strong financial position.

    Businesses can maintain a strong financial position by:

    • Managing their debt levels
    • Maintaining a healthy profit margin
    • Building up a cash reserve
    • Investing in their business

    Monitoring Financial Performance

    Monitoring financial performance is essential for any business, but it is especially important for businesses that are using a working capital line of credit. By monitoring their financial performance, businesses can identify potential problems early on and take corrective action.

    Financial performance should be monitored on a regular basis, and businesses should consider using financial ratios to track their progress. Financial ratios can help businesses identify trends and make informed decisions about their use of a working capital line of credit.

    Making Timely Adjustments

    Making timely adjustments to their use of a working capital line of credit is essential for businesses that want to use this financing tool responsibly. If a business’s financial situation changes, it should adjust its use of the line of credit accordingly.

    Businesses should consider making adjustments to their use of a working capital line of credit if they:

    • Experience a change in their cash flow
    • Need to make a large investment
    • Face unexpected expenses
    • Are experiencing financial difficulties

    Final Conclusion

    Working capital line of credit

    In the ever-changing business landscape, a working capital line of credit emerges as a valuable tool for businesses seeking financial agility. By understanding the eligibility requirements, terms and conditions, and best practices associated with this financing option, businesses can harness its power to overcome cash flow hurdles, invest in growth initiatives, and achieve long-term success.

    FAQ Compilation

    What is the primary purpose of a working capital line of credit?

    A working capital line of credit provides businesses with flexible access to funds to meet short-term operational expenses, such as inventory purchases, payroll, and marketing costs.

    What types of businesses typically utilize working capital lines of credit?

    Businesses of all sizes and industries can benefit from working capital lines of credit, particularly those experiencing seasonal fluctuations in cash flow or facing unexpected expenses.

    What are the advantages of using a working capital line of credit?

    Working capital lines of credit offer several advantages, including increased financial flexibility, improved cash flow management, and the ability to seize growth opportunities.

    What factors do lenders consider when evaluating a working capital line of credit application?

    Lenders typically assess an applicant’s creditworthiness, financial history, cash flow projections, and business plan when evaluating a working capital line of credit application.

    What are some best practices for managing a working capital line of credit?

    Effective management of a working capital line of credit involves careful monitoring of cash flow, regular financial forecasting, and maintaining a strong financial position.

  • Receive Paychecks Up to Two Days Early with Varo Early Direct Deposit

    Receive Paychecks Up to Two Days Early with Varo Early Direct Deposit

    Get ready to experience financial freedom with Varo Early Direct Deposit! This revolutionary feature allows you to access your hard-earned paychecks up to two days sooner, empowering you to take control of your finances like never before.

    Imagine the convenience of having your paycheck in your account before the weekend hits, giving you ample time to plan your expenses, pay your bills, and treat yourself to something special. Varo Early Direct Deposit is not just a service; it’s a game-changer that puts you in the driver’s seat of your financial journey.

    Varo Early Direct Deposit Overview

    Varo Bank offers an Early Direct Deposit feature that allows customers to access their paychecks up to two days earlier than the scheduled payment date. This feature is available to eligible customers who meet certain criteria and complete the setup process.

    Eligibility Criteria

    To be eligible for Varo Early Direct Deposit, customers must meet the following criteria:

    • Have an active Varo Bank account
    • Receive recurring direct deposits from an employer or government agency
    • Have a consistent deposit history
    • Meet Varo Bank’s other eligibility requirements

    Setup Process

    To set up Early Direct Deposit, eligible customers can follow these steps:

    1. Log in to their Varo Bank account
    2. Navigate to the “Direct Deposit” section
    3. Click on the “Early Direct Deposit” option
    4. Follow the on-screen instructions to complete the setup process

    Benefits of Using Varo Early Direct Deposit

    With Varo Early Direct Deposit, you can receive your paychecks up to two days earlier than your regular payday. This can be a major advantage, especially if you’re living paycheck to paycheck or have unexpected expenses. Here are some of the benefits of using Varo Early Direct Deposit:

    • More time to plan and budget.When you receive your paycheck early, you have more time to plan your budget and make sure your bills are paid on time. This can help you avoid overdraft fees and other financial penalties.
    • Less stress.Knowing that you have your paycheck in the bank early can give you peace of mind and reduce financial stress. This can be especially helpful if you have a lot of expenses or are worried about making ends meet.
    • More financial freedom.When you have your paycheck early, you can use it to take advantage of sales, discounts, and other opportunities that may not be available later in the month. This can help you save money and get ahead financially.

    Customer Testimonials

    Here are some testimonials from Varo customers who have benefited from using Early Direct Deposit:

    “I love Varo Early Direct Deposit! It’s so convenient to get my paycheck two days early. It gives me more time to plan my budget and make sure my bills are paid on time.”

    Sarah J.

    “I’m so grateful for Varo Early Direct Deposit. It’s helped me avoid overdraft fees and other financial penalties. I highly recommend it to anyone who wants to get ahead financially.”

    John D.

    Comparison with Other Early Direct Deposit Services: Varo Early Direct Deposit

    Varo’s early direct deposit service offers several advantages over similar offerings from other banks and financial institutions. One key advantage is that Varo does not charge any fees for early direct deposit, while some other providers may charge a monthly fee or a per-deposit fee.

    Another advantage of Varo’s early direct deposit service is that it is available to all Varo account holders, regardless of their account balance or direct deposit frequency. Some other providers may only offer early direct deposit to customers who meet certain criteria, such as maintaining a minimum account balance or receiving a certain number of direct deposits per month.

    However, one potential drawback of Varo’s early direct deposit service is that it may not be as widely accepted as early direct deposit services from larger banks. This means that some employers or government agencies may not be able to send early direct deposits to Varo accounts.

    Key Differences and Similarities between Varo and its Competitors

    Feature Varo Other Providers
    Fees No fees May charge a monthly fee or a per-deposit fee
    Availability Available to all Varo account holders May only be available to customers who meet certain criteria
    Acceptance May not be as widely accepted as early direct deposit services from larger banks Generally widely accepted

    Security and Reliability of Varo Early Direct Deposit

    Varo

    Varo is committed to the safety and reliability of its early direct deposit service. The company employs industry-leading security measures to protect customer funds, including encryption, fraud detection systems, and multi-factor authentication.

    Security Measures

    Varo uses bank-grade encryption to protect customer data and transactions. All information is encrypted both in transit and at rest, ensuring that it remains confidential and secure. Additionally, Varo has implemented robust fraud detection systems to monitor transactions for suspicious activity and prevent unauthorized access to accounts.

    Reliability

    Varo’s early direct deposit service has a proven track record of reliability. Customers consistently receive their funds on time, even before the scheduled payday. Varo partners with trusted financial institutions to ensure seamless and timely delivery of funds.

    Customer Testimonials

    Numerous customers have expressed their satisfaction with the security and dependability of Varo’s early direct deposit service:

    “I’ve been using Varo for over a year now and I’ve never had any problems with my direct deposit. The funds always arrive on time and I feel confident that my money is safe.”

    John Smith, Varo customer

    “I switched to Varo because I needed a reliable way to get my paycheck early. Varo has never let me down. I always receive my funds on time and the service is secure.”

    Mary Johnson, Varo customer

    Alternatives to Varo Early Direct Deposit

    Varo early direct deposit

    While Varo Early Direct Deposit is a convenient and reliable way to access your paycheck early, there are other options available. These alternatives may offer different benefits and drawbacks, so it’s important to consider which one is right for you.

    Payroll Advance Services

    Payroll advance services allow you to borrow against your future paycheck. You typically need to provide proof of employment and income, and the amount you can borrow is usually limited to a percentage of your paycheck. The fees associated with payroll advance services can vary, so it’s important to compare different providers before signing up.

    Negotiating with Your Employer

    If you have a good relationship with your employer, you may be able to negotiate an earlier payday. This can be a simple and effective way to get access to your money sooner, but it’s important to be aware that your employer may not be willing or able to accommodate your request.

    Comparison of Alternatives, Varo early direct deposit

    The following table summarizes the key differences and similarities between Varo Early Direct Deposit and other alternatives:

    Feature Varo Early Direct Deposit Payroll Advance Services Negotiating with Your Employer
    Availability Available to Varo bank account holders Available through third-party providers Depends on your employer’s policies
    Fees None May vary depending on the provider None
    Amount you can access Up to 100% of your paycheck Typically limited to a percentage of your paycheck Depends on your agreement with your employer
    Speed Receive your paycheck up to 2 days early Can receive funds within hours May take several days to receive your paycheck
    Convenience Easy to set up and use May require additional paperwork and verification May require negotiation with your employer

    Last Point

    Varo early direct deposit

    With Varo Early Direct Deposit, you’ll never have to worry about unexpected expenses or late fees again. Embrace financial flexibility and peace of mind today! Join the thousands of satisfied customers who have already experienced the transformative power of Varo Early Direct Deposit.

    It’s time to unlock a new level of financial freedom and start living life on your terms.

    Questions Often Asked

    How do I set up Varo Early Direct Deposit?

    Setting up Varo Early Direct Deposit is a breeze! Simply provide your employer with your Varo account and routing numbers, and they’ll take care of the rest. You’ll start receiving your paychecks up to two days earlier, without any hassle.

    Is Varo Early Direct Deposit secure?

    Absolutely! Varo employs industry-leading security measures to protect your funds. Your money is safe and secure, so you can rest easy knowing that your hard-earned paycheck is in good hands.

    Are there any fees associated with Varo Early Direct Deposit?

    No, Varo Early Direct Deposit is completely free to use. There are no hidden fees or charges, so you can enjoy the benefits of receiving your paycheck early without breaking the bank.

  • Capital One Hysa: An Expansive Guide to High-Yield Savings

    Capital One Hysa: An Expansive Guide to High-Yield Savings

    Capital One Hysa invites you on an enriching journey, revealing the intricacies of high-yield savings with vivid clarity and captivating detail. Embark on this exploration to unlock the secrets of financial growth and discover how Capital One Hysa empowers you to save more, earn more, and achieve your financial aspirations.

    Unravel the exceptional features of Capital One Hysa, meticulously compared to its peers in an illuminating table. Delve into the tangible benefits that await you, empowering you to make informed decisions and maximize your savings potential.

    Capital One Hysa Features

    Gobankingrates comerica bonuses coupons debit credit referral fnbo

    Capital One Hysa offers a range of features that make it a compelling option for savers looking to grow their money.

    One of the standout features of Capital One Hysa is its competitive interest rate. The account currently offers an APY of 3.30%, which is among the highest rates available for high-yield savings accounts. This means that your money can grow faster with Capital One Hysa than with many other savings accounts.

    Another key feature of Capital One Hysa is its lack of monthly maintenance fees. This means that you can keep your money in the account without having to worry about paying any fees, which can eat into your savings over time.

    Capital One Hysa also offers a variety of other features that can make it a convenient and user-friendly option for savers. These features include:

    • Online and mobile banking: You can access your account online or through the Capital One mobile app, making it easy to manage your money from anywhere.
    • Automatic deposits: You can set up automatic deposits from your checking account to your Hysa, making it easy to save money on a regular basis.
    • Customer support: Capital One offers 24/7 customer support, so you can get help with your account whenever you need it.

    Comparison of Capital One Hysa to Other High-Yield Savings Accounts

    The following table compares the features of Capital One Hysa to those of other popular high-yield savings accounts:

    Feature Capital One Hysa Ally Online Savings Account Marcus by Goldman Sachs High Yield Online Savings
    APY 3.30% 3.30% 3.30%
    Monthly maintenance fee $0 $0 $0
    Online and mobile banking Yes Yes Yes
    Automatic deposits Yes Yes Yes
    Customer support 24/7 24/7 24/7

    As you can see, Capital One Hysa compares favorably to other popular high-yield savings accounts in terms of its features and benefits.

    Capital One Hysa Benefits

    Capital one hysa

    Capital One Hysa offers several benefits to its customers, making it a valuable option for those looking to save money and earn interest.

    One of the primary benefits of Capital One Hysa is its competitive interest rates. The high-yield savings account consistently offers one of the highest interest rates in the market, allowing customers to maximize their earnings. The interest is compounded daily, which means that customers earn interest on their interest, leading to even greater returns over time.

    Flexibility and Convenience

    Capital One Hysa provides flexibility and convenience to its customers. There are no minimum balance requirements, so customers can open an account with any amount of money. Additionally, there are no monthly maintenance fees, making it a low-cost option for saving.

    Customers can access their accounts online, through the mobile app, or by phone, making it easy to manage their finances on the go.

    FDIC Insurance, Capital one hysa

    Capital One Hysa is FDIC-insured up to $250,000, providing peace of mind to customers. This means that their deposits are protected in the event of a bank failure, ensuring the safety of their savings.

    Capital One Hysa Requirements

    To open a Capital One Hysa, there are a few basic requirements that you need to meet.

    The first requirement is that you must be a US citizen or resident alien. You must also be at least 18 years of age.

    Minimum Deposit and Balance Requirements

    The minimum deposit to open a Capital One Hysa is $10. Once your account is open, you must maintain a minimum balance of $10.

    Capital One Hysa Fees

    Capital One Hysa offers a competitive interest rate with no monthly maintenance fees. However, there are a few potential fees to be aware of:

    The following table summarizes the fees associated with Capital One Hysa:

    Fee Amount
    Monthly maintenance fee $0
    Early withdrawal penalty Up to 3 months of interest
    Excessive withdrawal penalty Up to $10 per withdrawal after 6 withdrawals per month

    Early Withdrawal Penalty

    If you withdraw funds from your Capital One Hysa before the maturity date, you may be subject to an early withdrawal penalty. The penalty is equal to up to 3 months of interest earned on the withdrawn funds.

    Excessive Withdrawal Penalty

    Capital One Hysa allows up to 6 withdrawals per month without penalty. However, if you make more than 6 withdrawals in a month, you may be subject to an excessive withdrawal penalty of up to $10 per withdrawal.

    Capital One Hysa Alternatives

    Capital One Hysa is a competitive option in the market, but there are other high-yield savings accounts that may suit your specific needs.

    When comparing Capital One Hysa to other financial institutions, consider factors such as interest rates, minimum balance requirements, and fees.

    Interest Rates

    • Capital One Hysa offers a competitive interest rate, but other institutions may offer higher rates.
    • Compare interest rates from multiple institutions to find the highest yield for your savings.

    Minimum Balance Requirements

    • Capital One Hysa has a low minimum balance requirement, but some institutions may offer accounts with no minimum balance.
    • Consider your savings habits and choose an account that aligns with your financial situation.

    Fees

    • Capital One Hysa has no monthly maintenance fees, but other institutions may charge fees for certain transactions or services.
    • Review the fee schedule of each institution to avoid any unexpected charges.

    Final Thoughts: Capital One Hysa

    Capital one hysa

    As you reach the pinnacle of this enlightening discourse, you will emerge with a profound understanding of Capital One Hysa. Its requirements, fees, and alternatives have been laid bare, equipping you with the knowledge to make discerning choices and navigate the world of high-yield savings with confidence.

    Remember, Capital One Hysa stands as a beacon of financial empowerment, guiding you toward a brighter financial future. Embrace its transformative power and unlock the gateway to financial success.

    Query Resolution

    What sets Capital One Hysa apart from other high-yield savings accounts?

    Capital One Hysa distinguishes itself through its competitive interest rates, user-friendly platform, and commitment to customer satisfaction. Its tailored features cater to a wide range of financial needs, making it an exceptional choice for those seeking to maximize their savings.

    Are there any fees associated with Capital One Hysa?

    Capital One Hysa offers a straightforward fee structure with no monthly maintenance fees or minimum balance requirements. However, there is a one-time $10 closing fee if the account is closed within 180 days of opening.

    How do I open a Capital One Hysa?

    Opening a Capital One Hysa is a seamless process. You can apply online, through the Capital One mobile app, or by visiting a local branch. The minimum opening deposit is $0, making it accessible to individuals at all financial stages.

  • American Express Personal Savings: A Comprehensive Overview

    American Express Personal Savings: A Comprehensive Overview

    Step into the world of American Express Personal Savings, where financial freedom and convenience converge. With its unparalleled features and benefits, this account empowers you to manage your money with ease, grow your savings effortlessly, and unlock a world of financial possibilities.

    From its competitive interest rates to its user-friendly digital banking platform, American Express Personal Savings is designed to cater to your every financial need. Discover the ins and outs of this exceptional account and embark on a journey towards financial prosperity.

    American Express Personal Savings Features and Benefits

    American express personal savings

    American Express Personal Savings accounts offer a unique combination of features and benefits that set them apart from other savings accounts. These accounts provide competitive interest rates, flexible access to funds, and a range of additional perks and rewards.

    Competitive Interest Rates

    American Express Personal Savings accounts offer some of the highest interest rates in the industry. This means you can earn more money on your savings over time, helping you reach your financial goals faster.

    Flexible Access to Funds

    With American Express Personal Savings accounts, you have 24/7 access to your funds through online banking, mobile banking, or ATMs. You can also make withdrawals and transfers at any American Express branch.

    Additional Perks and Rewards

    In addition to competitive interest rates and flexible access to funds, American Express Personal Savings accounts also come with a range of additional perks and rewards. These include:

    • No monthly maintenance fees
    • Free online bill pay
    • Access to American Express rewards and benefits

    Eligibility and Application Process

    American express personal savings

    Opening an American Express Personal Savings account is a straightforward process with specific eligibility requirements and application steps.

    Eligibility Requirements

    To be eligible for an American Express Personal Savings account, you must meet the following criteria:

    • Be a U.S. citizen or permanent resident
    • Be at least 18 years of age
    • Have a valid Social Security number
    • Have a good credit history

    Application Process

    Applying for an American Express Personal Savings account can be done online or by phone. The application process typically involves the following steps:

    1. Provide your personal information, including your name, address, and Social Security number
    2. Provide your financial information, including your income and assets
    3. Review and accept the terms and conditions

    Potential Reasons for Ineligibility

    There are several reasons why an application for an American Express Personal Savings account may be denied. These include:

    • Insufficient credit history
    • Negative credit history, such as bankruptcies or foreclosures
    • Insufficient income or assets
    • Outstanding debts or liens

    Fees and Interest Rates

    American Express Personal Savings accounts come with minimal fees and competitive interest rates, making them a convenient and affordable option for managing your savings.

    Maintenance Fees

    There are no monthly maintenance fees associated with American Express Personal Savings accounts.

    Withdrawal Fees, American express personal savings

    You are allowed up to six withdrawals per statement cycle without incurring any fees. Additional withdrawals may result in a fee of $5 per withdrawal.

    Inactivity Fees

    American Express does not charge inactivity fees on Personal Savings accounts.

    Interest Rates

    Interest rates for American Express Personal Savings accounts are determined based on market conditions and the balance in your account. They are generally competitive with industry averages, offering a competitive return on your savings.

    American Express Personal Savings Account Fees and Interest Rates
    Fee/Rate Details
    Monthly Maintenance Fee $0
    Withdrawal Fees Up to 6 withdrawals per statement cycle free, then $5 per withdrawal
    Inactivity Fees None
    Interest Rates Competitive rates based on market conditions and account balance

    Access and Convenience: American Express Personal Savings

    Savings express american personal amex account high yield apy review

    American Express Personal Savings accounts offer convenient access through multiple channels, ensuring seamless management of your finances.

    You can conveniently access your account online through the American Express website or mobile banking app. These platforms provide real-time account information, transaction history, and the ability to make transfers and payments. Additionally, you can locate nearby ATMs using the app or website, enabling easy cash withdrawals and deposits.

    Customer Service and Support

    American Express provides dedicated customer service and support channels to assist account holders with any inquiries or issues. You can contact their support team via phone, email, or live chat during business hours. Additionally, the website and mobile app offer comprehensive FAQs and support articles for self-help.

    Security Measures

    American Express prioritizes the security of its customers’ accounts. They employ robust security measures, including multi-factor authentication, encryption, and fraud monitoring, to protect your personal and financial information. Regular security updates and patches are implemented to ensure the latest protection standards are maintained.

    Comparison to Other Savings Options

    American Express Personal Savings accounts offer a range of benefits and features that make them competitive with other savings options. However, it’s important to compare them to other savings options, such as high-yield savings accounts, money market accounts, and certificates of deposit (CDs), to determine which option best meets your financial needs.

    The following table summarizes the key differences between American Express Personal Savings accounts and other savings options:

    Feature American Express Personal Savings High-Yield Savings Accounts Money Market Accounts Certificates of Deposit (CDs)
    Interest rates 0.01% APY 0.50%

    1.00% APY

    0.25%

    0.50% APY

    1.00%

    2.00% APY

    Minimum balance $0 $0

    $2,500

    $0

    $10,000

    $500

    $1,000

    Fees None None May have monthly maintenance fees Early withdrawal penalties
    Accessibility Online and mobile banking Online and mobile banking Online and mobile banking Limited access to funds during the term
    FDIC insurance Up to $250,000 Up to $250,000 Up to $250,000 Up to $250,000

    High-Yield Savings Accounts

    High-yield savings accounts typically offer higher interest rates than American Express Personal Savings accounts, but they may also have higher minimum balance requirements.

    High-yield savings accounts are a good option for savers who want to earn a higher return on their money, but who also want the flexibility to access their funds at any time.

    Money Market Accounts

    Money market accounts offer interest rates that are typically higher than American Express Personal Savings accounts, but they may also have higher minimum balance requirements and monthly maintenance fees. Money market accounts are a good option for savers who want to earn a higher return on their money, but who also want the flexibility to access their funds at any time.

    Certificates of Deposit (CDs)

    Certificates of deposit (CDs) offer higher interest rates than American Express Personal Savings accounts, but they also have longer terms and early withdrawal penalties. CDs are a good option for savers who want to earn a higher return on their money, but who are willing to commit to a longer term.

    Final Wrap-Up

    In the realm of personal finance, American Express Personal Savings stands tall as a beacon of innovation and convenience. Its tailored features, competitive rates, and unwavering commitment to customer satisfaction make it an ideal choice for those seeking a seamless and rewarding banking experience.

    Embrace the power of American Express Personal Savings today and unlock the gateway to financial success.

    Question & Answer Hub

    What sets American Express Personal Savings apart from other savings accounts?

    American Express Personal Savings offers a unique combination of competitive interest rates, low fees, and exceptional digital banking tools, making it an attractive choice for savers.

    Is there a minimum balance requirement for American Express Personal Savings?

    No, American Express Personal Savings has no minimum balance requirement, making it accessible to individuals of all financial backgrounds.

    How can I access my American Express Personal Savings account?

    You can access your account through online banking, mobile banking, or a network of ATMs nationwide, ensuring convenient and secure access to your funds.

  • Savings Accounts: Your Gateway to Financial Stability

    Savings Accounts: Your Gateway to Financial Stability

    In the realm of personal finance, savings accounts reign supreme as a cornerstone of financial stability. As the bedrock of financial well-being, they offer a secure haven for your hard-earned funds while nurturing the growth of your wealth. Delve into this comprehensive guide as we unveil the intricacies of savings accounts, empowering you to harness their potential and achieve your financial aspirations.

    Account Basics

    A savings account is a type of deposit account held at a financial institution that provides a safe place to store and grow your money. Unlike checking accounts, which are designed for everyday transactions, savings accounts are intended for long-term savings goals.

    They typically offer higher interest rates than checking accounts, allowing your money to grow over time.

    Types of Savings Accounts

    There are several types of savings accounts available, each with its own features and benefits:

    • Traditional Savings Accounts:These are the most basic type of savings account, offering a fixed interest rate and no monthly fees.
    • High-Yield Savings Accounts:These accounts offer higher interest rates than traditional savings accounts, but may come with higher fees or restrictions.
    • Money Market Accounts:These accounts offer higher interest rates and more flexibility than traditional savings accounts, but may have higher minimum balance requirements.
    • Certificates of Deposit (CDs):These accounts offer fixed interest rates for a specified term, and penalties may apply for early withdrawal.

    Examples of Savings Accounts

    Various financial institutions offer different types of savings accounts, including:

    • Ally Bank:High-Yield Online Savings Account
    • Capital One 360:Performance Savings Account
    • Discover Bank:Money Market Account
    • Wells Fargo:Way2Save Savings Account

    Benefits of Savings Accounts

    Puting budgeting budget advantageccs jug piggy stack

    Savings accounts offer a safe and secure way to store and grow your money. They provide numerous advantages that can help you achieve your financial goals, whether it’s saving for a down payment on a house, a new car, or your child’s education.

    Earning Interest

    One of the primary benefits of a savings account is that it earns interest. Interest is a small amount of money paid by the bank on your savings balance. The interest rate varies depending on the type of savings account you have and the financial institution you choose.

    However, even small interest payments can add up over time, helping you grow your savings faster.

    Building an Emergency Fund

    Having a savings account is essential for building an emergency fund. An emergency fund is a stash of money you can tap into if you face unexpected expenses, such as medical bills, car repairs, or job loss. Having an emergency fund can provide you with peace of mind and prevent you from going into debt when unexpected expenses arise.

    Reaching Financial Goals, Savings account

    Savings accounts can help you reach your long-term financial goals. Whether you’re saving for a down payment on a house, a new car, or your child’s education, a savings account can help you put money aside regularly and track your progress towards your goals.

    Example: Saving for a Down Payment

    Imagine you’re saving for a down payment on a house. You set up a savings account and deposit $500 per month. After a year, you’ll have saved $6,000. If your savings account earns an interest rate of 2%, you’ll have earned an additional $120 in interest.

    This interest may not seem like much, but it can add up over time, helping you reach your down payment goal faster.

    Interest Rates and Fees

    Interest rates are the backbone of savings accounts, influencing the growth of your savings. Different financial institutions offer varying interest rates, impacting the potential earnings on your account.

    Interest is calculated based on the account balance and the annual percentage yield (APY) offered by the institution. APY takes into account the compounding frequency, typically monthly or quarterly, which adds interest to the principal, leading to exponential growth over time.

    Comparison of Interest Rates

    When comparing interest rates, it’s crucial to consider the following factors:

    • APY:The annual percentage yield reflects the effective interest rate earned on your savings, taking into account compounding.
    • Compounding frequency:More frequent compounding (e.g., monthly vs. annually) leads to higher returns in the long run.
    • Minimum balance requirements:Some institutions offer higher interest rates for accounts that maintain a minimum balance.

    Fees and Charges

    While savings accounts are generally low-cost, some institutions may impose fees or charges. These may include:

    • Monthly maintenance fees:A fixed fee charged each month for maintaining the account.
    • Transaction fees:Charges for withdrawals or transfers beyond a certain number per month.
    • Dormancy fees:Fees incurred if the account remains inactive for an extended period.

    Using Savings Accounts Effectively

    Savings account

    Savings accounts are a crucial tool for managing your finances. By following these tips, you can maximize their effectiveness and reach your financial goals faster.

    Setting Up Automatic Transfers

    One of the most effective ways to save money is to set up automatic transfers from your checking account to your savings account on a regular basis. This ensures that you’re saving consistently, even when you don’t have the time or willpower to do it manually.

    Tracking Savings Progress

    It’s important to track your savings progress regularly to stay motivated and make adjustments as needed. You can do this by reviewing your account statements or using online banking tools. Seeing your savings grow can provide a sense of accomplishment and encourage you to keep going.

    Other Tips

    • Set realistic savings goals and break them down into smaller, more manageable chunks.
    • Consider using a high-yield savings account to earn a higher interest rate on your savings.
    • Avoid dipping into your savings for non-essential expenses.
    • Make saving a priority in your budget.

    Alternatives to Savings Accounts

    While savings accounts are a popular option for saving money, they are not the only option. There are a number of other financial instruments that can serve as alternatives to savings accounts, each with its own unique features and benefits.

    Some of the most common alternatives to savings accounts include:

    Certificates of Deposit (CDs)

    • CDs are time deposits that offer a fixed interest rate for a specified period of time.
    • CDs typically offer higher interest rates than savings accounts, but they also have a longer lock-in period.
    • If you withdraw money from a CD before the maturity date, you will typically have to pay a penalty.

    Money Market Accounts (MMAs)

    • MMAs are interest-bearing accounts that offer check-writing privileges.
    • MMAs typically offer higher interest rates than savings accounts, but they also have a higher minimum balance requirement.
    • MMAs are a good option for people who need to access their money on a regular basis.

    High-Yield Savings Accounts

    • High-yield savings accounts are savings accounts that offer higher interest rates than traditional savings accounts.
    • High-yield savings accounts typically have a higher minimum balance requirement than traditional savings accounts.
    • High-yield savings accounts are a good option for people who have a large amount of money to save.

    The suitability of different alternatives to savings accounts will depend on your individual circumstances.

    • If you need to access your money on a regular basis, then an MMA may be a good option.
    • If you are looking for a higher interest rate, then a CD or a high-yield savings account may be a good option.
    • If you have a large amount of money to save, then a high-yield savings account may be a good option.

    Final Thoughts

    Savings account

    As we conclude our exploration of savings accounts, remember that they are not mere repositories for your funds; they are instruments of financial empowerment. By embracing the principles Artikeld in this guide, you can unlock the full potential of savings accounts, paving the way for a future brimming with financial security and prosperity.

    User Queries

    What is the minimum balance required to open a savings account?

    The minimum balance requirements vary depending on the financial institution. Some banks may have no minimum balance requirement, while others may require a minimum deposit of $25 or more.

    Can I withdraw money from my savings account at any time?

    Yes, you can generally withdraw money from your savings account at any time. However, some banks may limit the number of withdrawals you can make per month or charge a fee for excessive withdrawals.

    How often does my savings account earn interest?

    The frequency of interest payments varies depending on the financial institution. Some banks may pay interest monthly, while others may pay interest quarterly or annually.