Tag: financial security

  • Chase Cash Deposit: A Comprehensive Guide to Making Cash Deposits Safely and Conveniently

    Chase Cash Deposit: A Comprehensive Guide to Making Cash Deposits Safely and Conveniently

    Discover the world of Chase cash deposit, a secure and convenient way to manage your finances. Whether you’re a seasoned Chase customer or new to the banking experience, this comprehensive guide will empower you with the knowledge and insights to make cash deposits with ease and confidence.

    From understanding the various deposit methods to navigating fees and limits, we’ll delve into every aspect of Chase cash deposit. So, sit back, relax, and let’s embark on a journey to financial freedom.

    Types of Chase Cash Deposits

    Chase cash deposit

    Chase Bank offers several convenient methods for customers to make cash deposits, each with its own advantages and disadvantages. These methods include ATMs, branch locations, and mobile banking.

    ATMs, Chase cash deposit

    ATMs are widely available and offer a quick and easy way to deposit cash. Customers can simply insert their debit card or ATM card into the machine and follow the on-screen instructions. ATMs typically accept bills in denominations of $1, $5, $10, $20, $50, and $100. However, some ATMs may have limitations on the amount of cash that can be deposited per transaction or per day.

    Branches

    Customers can also make cash deposits at any Chase branch location during regular business hours. This method is ideal for larger deposits or for customers who prefer to interact with a bank representative in person. To make a deposit at a branch, customers will need to present their account number and a valid form of identification.

    Mobile Banking

    Chase customers can also deposit cash using the bank’s mobile banking app. This method is available 24/7 and allows customers to deposit checks and cash from anywhere with an internet connection. To use mobile banking for cash deposits, customers will need to have a compatible smartphone or tablet and the Chase mobile banking app installed.

    They will also need to have their account number and a valid form of identification on hand.

    Eligibility and Requirements

    To be eligible for making cash deposits at Chase Bank, you must meet certain criteria and provide necessary requirements.

    Firstly, you must have an active Chase Bank account. This can be a checking, savings, or money market account. Secondly, you must have a valid government-issued identification card, such as a driver’s license, passport, or military ID. Additionally, there are minimum and maximum deposit amounts that may vary depending on your account type and the specific Chase Bank branch you visit.

    Verifying Eligibility

    To verify your eligibility, you can visit your local Chase Bank branch and speak with a customer service representative. They will review your account information and identification to determine if you meet the eligibility criteria. You can also call Chase Bank’s customer service line at 1-800-935-9935 to inquire about eligibility and any additional requirements.

    Fees and Limits: Chase Cash Deposit

    Chase deposit bank direct set account wondering opened recently going ve re if

    When making cash deposits at Chase Bank, it’s important to be aware of the associated fees and limits. These can vary depending on the deposit method you choose.

    Deposit Fees

    • Over-the-counter deposits:Free for Chase customers. Non-customers may be charged a fee of up to $4.95 per deposit.
    • ATM deposits:Free for Chase customers using Chase ATMs. Non-customers may be charged a fee of up to $2.50 per deposit.
    • Mobile deposits:Free for all Chase customers using the Chase Mobile app.

    Deposit Limits

    Chase Bank also has limits on the amount of cash you can deposit per day, per month, and per year. These limits vary depending on your account type and banking history. For example, the daily deposit limit for basic checking accounts is $5,000, while the monthly limit is $10,000.

    If you need to deposit more than the allowed limit, you may be able to request a temporary increase from Chase Bank. However, this is not guaranteed and may be subject to additional fees.

    Security Measures

    Chase Bank employs robust security measures to protect cash deposits and prevent fraud and money laundering.

    These measures include:

    Anti-Fraud Protocols

    • Real-time fraud monitoring:Chase’s systems monitor all cash deposits for suspicious activity, such as large or unusual deposits.
    • Identity verification:Customers are required to provide identification when making a cash deposit, and their identity is verified against Chase’s records.
    • Secure deposit boxes:Chase branches have secure deposit boxes that customers can use to deposit cash without interacting with a teller.

    Anti-Money Laundering Protocols

    • Transaction reporting:Chase reports all cash deposits over a certain threshold to the government.
    • Know Your Customer (KYC) procedures:Chase collects information about its customers to help identify and prevent money laundering.
    • Employee training:Chase employees are trained to recognize and report suspicious activity.

    Tips for Customers

    Customers can help protect their cash deposits by following these tips:

    • Deposit cash promptly:Do not hold on to large amounts of cash for extended periods.
    • Be aware of your surroundings:When making a cash deposit, be aware of your surroundings and be cautious of anyone following you.
    • Use a secure deposit box:If available, use a secure deposit box to deposit cash without interacting with a teller.
    • Report any suspicious activity:If you notice any suspicious activity related to your cash deposits, report it to Chase immediately.

    Troubleshooting and Support

    Should you encounter any difficulties during cash deposits, this section provides troubleshooting guidance and contact information for assistance.

    If you are unable to resolve the issue independently, you can reach out to our dedicated customer support team for further assistance.

    Contact Information

    • Phone: 1-800-935-9935
    • Online Support: Visit our website’s support page for live chat or email assistance.
    • In-Branch Support: Visit your nearest Chase branch for personalized assistance.

    Troubleshooting Flowchart

    Follow these steps to resolve common deposit-related problems:

    1. Verify account information:Ensure you are depositing into the correct account and that the account is active.
    2. Check deposit amount:Confirm that the amount you are depositing matches the amount indicated on the deposit slip.
    3. Inspect cash quality:Ensure the bills are not torn, damaged, or excessively wrinkled.
    4. Follow deposit instructions:Carefully follow the instructions on the deposit slip and insert the cash securely into the ATM or teller.
    5. Obtain a receipt:Always keep the receipt as proof of your deposit.

    If the issue persists, please contact customer support for further assistance.

    Ultimate Conclusion

    Chase cash deposit

    As we conclude our exploration of Chase cash deposit, remember that financial security is paramount. By following the tips and guidelines Artikeld in this guide, you can safeguard your deposits and enjoy peace of mind. Embrace the convenience and efficiency of Chase cash deposit, and take control of your finances today.

    FAQ Guide

    Can I make cash deposits at any Chase branch?

    Yes, you can make cash deposits at any Chase branch during regular business hours.

    Are there any fees associated with Chase cash deposits?

    There may be fees associated with cash deposits, depending on the deposit method used. Please refer to the fee schedule provided by Chase Bank for more details.

    What are the security measures in place to protect my cash deposits?

    Chase Bank employs robust security measures, including anti-fraud and anti-money laundering protocols, to safeguard your cash deposits.

  • Discover the Best No-Exam Term Life Insurance: A Guide to Hassle-Free Coverage

    Discover the Best No-Exam Term Life Insurance: A Guide to Hassle-Free Coverage

    In the realm of financial security, best no exam term life insurance emerges as a beacon of simplicity and convenience. Dive into this comprehensive guide, where we unveil the intricacies of this insurance, empowering you to make informed decisions that safeguard your loved ones.

    No-exam term life insurance stands out as a game-changer, eliminating the need for intrusive medical examinations. Its benefits are undeniable, from expedited application processes to hassle-free underwriting. Yet, it’s crucial to weigh these advantages against potential drawbacks, ensuring you make the choice that aligns perfectly with your needs.

    Overview of Best No-Exam Term Life Insurance

    Term life insurance is a type of life insurance that provides coverage for a specific period of time, such as 10, 20, or 30 years. It is designed to provide financial protection for your loved ones in the event of your untimely death.

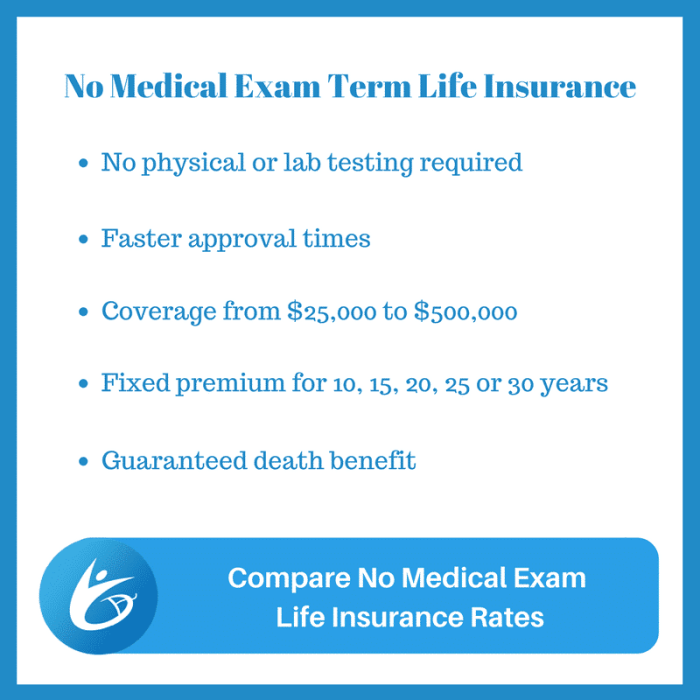
    No-exam life insurance is a type of term life insurance that does not require you to take a medical exam.

    There are a number of benefits to no-exam term life insurance, including:

    • Convenience:No-exam life insurance is quick and easy to apply for. You can typically complete the application online in a matter of minutes.
    • No medical exam:As the name suggests, no-exam life insurance does not require you to take a medical exam. This can be a major benefit for people who are in poor health or who have a history of medical problems.
    • Affordable:No-exam life insurance is typically more affordable than traditional term life insurance. This is because the insurance company does not have to pay for the cost of a medical exam.

    However, there are also some drawbacks to no-exam term life insurance, including:

    • Lower coverage limits:No-exam life insurance policies typically have lower coverage limits than traditional term life insurance policies.
    • Higher premiums:No-exam life insurance policies typically have higher premiums than traditional term life insurance policies.
    • Limited underwriting:No-exam life insurance policies typically have limited underwriting, which means that the insurance company may not be able to assess your risk as accurately as they would if you took a medical exam.

    Factors to Consider When Choosing a No-Exam Term Life Insurance Policy

    When selecting a no-exam term life insurance policy, several key factors should be carefully evaluated to ensure it meets your specific needs and financial situation. These factors include:

    Understanding Coverage Amounts and Policy Terms: Determine the appropriate coverage amount based on your income, debts, and financial obligations. Consider the policy term, which is the duration for which the coverage will be provided, and choose one that aligns with your financial goals and life stage.

    Comparing Premiums and Policy Features

    Compare premiums from different insurance companies to find the most competitive rates. Examine policy features such as the death benefit, riders (additional coverage options), and exclusions (situations where coverage may not apply). Choose a policy that offers the best combination of coverage, features, and affordability.

    Evaluating the Financial Stability of Insurance Companies

    Research the financial stability of insurance companies by checking their ratings from independent agencies such as AM Best, Standard & Poor’s, and Moody’s. A higher rating indicates a stronger financial position and lower risk of the company being unable to fulfill its obligations.

    Comparison of Top No-Exam Term Life Insurance Providers

    Life insurance exam companies history definitive update guide

    Comparing different no-exam term life insurance providers is crucial to find the best policy for your needs. Here’s a table summarizing key features of top providers:

    Provider Coverage Limits Policy Terms Premium Rates
    Haven Life Up to $1 million 10, 15, 20, or 30 years Competitive rates, especially for younger and healthier applicants
    Ladder Up to $8 million 10, 15, 20, 25, or 30 years Higher premiums but offers underwriting without a medical exam
    Bestow Up to $1.5 million 10, 15, 20, 25, or 30 years Simplified underwriting process, but higher premiums for smokers
    Fabric Up to $5 million 10, 15, 20, or 30 years Offers customizable coverage and riders, but may have higher premiums
    Fidelity Life Up to $1 million 10, 15, 20, or 30 years Lower premiums for older applicants, but limited coverage amounts

    Strengths and Weaknesses

    Each provider has its strengths and weaknesses:

    • Haven Life:Low premiums, easy application process, but lower coverage limits.
    • Ladder:High coverage limits, underwriting without a medical exam, but higher premiums.
    • Bestow:Simplified underwriting, no medical exam required, but higher premiums for smokers.
    • Fabric:Customizable coverage, additional riders, but potentially higher premiums.
    • Fidelity Life:Lower premiums for older applicants, but limited coverage amounts.

    Application Process for No-Exam Term Life Insurance

    Best no exam term life insurance

    Applying for no-exam term life insurance is designed to be simple and straightforward. Unlike traditional life insurance, which requires a medical exam, no-exam life insurance eliminates the need for invasive procedures and lengthy medical questionnaires.

    Simplified Application Process

    The application process typically involves completing an online form or speaking with an insurance agent over the phone. The form typically asks for basic information such as your name, age, health history, and lifestyle habits. You may also be asked about your occupation and financial situation.

    Underwriting Process, Best no exam term life insurance

    Once you submit your application, the insurance company will review your information to determine your risk level. This process is known as underwriting. For no-exam life insurance, underwriting relies on the information you provide in your application, as well as data from external sources such as medical records and prescription history.

    Tips for Maximizing Approval Chances

    To increase your chances of approval for no-exam term life insurance, consider the following tips:

    • Be honest and accurate when completing your application.
    • Disclose any pre-existing health conditions or lifestyle habits that may affect your risk level.
    • Consider your occupation and financial situation. High-risk occupations or unstable financial situations may impact your approval.
    • Shop around and compare quotes from multiple insurance providers to find the best coverage for your needs.

    Tips for Getting the Best No-Exam Term Life Insurance Policy: Best No Exam Term Life Insurance

    Securing the most favorable no-exam term life insurance policy requires a proactive approach. By implementing these strategies, you can maximize your coverage and minimize your financial burden.

    First and foremost, it’s essential to shop around and compare quotes from multiple providers. Utilizing online comparison tools and consulting with independent insurance agents can help you identify the most competitive rates that meet your specific needs and budget.

    Importance of Reading and Understanding Policy Details

    Before signing on the dotted line, thoroughly review and comprehend the terms and conditions of your policy. Pay close attention to the coverage amount, premium payments, and any exclusions or limitations that may affect your eligibility for benefits.

    Don’t hesitate to ask questions and seek clarification from the insurance provider to ensure you fully understand the scope of your coverage and any potential implications.

    Negotiating with Insurance Providers

    Negotiating with insurance providers can often yield favorable results. Consider bundling your no-exam term life insurance policy with other insurance products, such as homeowners or auto insurance, to potentially qualify for discounts.

    Additionally, maintaining a healthy lifestyle, including regular exercise and a balanced diet, can positively impact your insurance premiums. By demonstrating a commitment to your well-being, you may be eligible for preferred rates.

    Epilogue

    Best no exam term life insurance

    As you embark on the journey of securing the best no-exam term life insurance policy, remember to prioritize coverage amounts that align with your financial responsibilities and life goals. Embrace the power of comparison, evaluating premiums, policy features, and the financial stability of insurance providers.

    By following the expert tips Artikeld in this guide, you’ll navigate the application process with ease, maximizing your chances of approval.

    May this guide serve as your trusted companion, empowering you to secure peace of mind and financial protection for your loved ones. The world of no-exam term life insurance awaits your exploration, where convenience and security intertwine seamlessly.

    Frequently Asked Questions

    What sets no-exam term life insurance apart from traditional life insurance?

    No-exam term life insurance streamlines the application process by eliminating the need for medical examinations, providing a faster and more convenient path to coverage.

    Are there any drawbacks to consider with no-exam term life insurance?

    While no-exam term life insurance offers convenience, it may come with higher premiums compared to traditional life insurance due to the absence of medical information.

    How can I find the best no-exam term life insurance policy for my needs?

    Thoroughly compare coverage amounts, policy terms, and premium rates offered by different providers. Seek guidance from insurance professionals to ensure you make an informed decision.

  • Small Business Indemnity Insurance: A Lifeline for Entrepreneurs

    Small Business Indemnity Insurance: A Lifeline for Entrepreneurs

    Small business indemnity insurance stands as a guardian angel for entrepreneurs, safeguarding them against financial pitfalls and legal woes. It’s a safety net that provides peace of mind, allowing businesses to thrive amidst unforeseen circumstances.

    This insurance policy extends its protective shield over a wide spectrum of risks, including bodily injury, property damage, and financial losses. It empowers businesses to navigate the complexities of liability claims, ensuring they can continue their operations without facing financial ruin.

    Coverage Overview

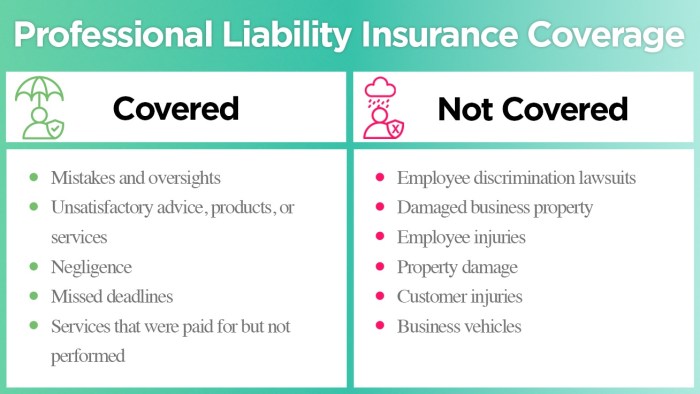
    Small business indemnity insurance serves as a protective shield for your enterprise, safeguarding it against a spectrum of financial liabilities and risks. It encompasses coverage for bodily injuries sustained by individuals on your premises, damage to property belonging to others, and financial losses incurred due to negligence or errors.

    This insurance policy acts as a safety net, ensuring that your business remains financially stable even in the face of unforeseen events. It empowers you to focus on growing your venture without the burden of excessive financial concerns.

    Covered Risks

    • Bodily Injury:Coverage extends to injuries suffered by individuals on your business premises, regardless of whether they are customers, employees, or visitors.
    • Property Damage:This aspect covers damage caused to the property of others due to your business operations or negligence.
    • Financial Loss:The policy provides protection against financial losses arising from legal liability, such as claims for defamation or copyright infringement.

    Key Features and Benefits

    Small business indemnity insurance

    Small business indemnity insurance is designed to protect businesses from financial liability and legal costs arising from claims made against them. It offers a range of key features and benefits that can provide peace of mind and financial security.

    Indemnity insurance policies typically cover the following:

    Claims Coverage, Small business indemnity insurance

    • Bodily injury or property damage to third parties
    • Legal expenses, including court costs and attorney fees
    • Judgments and settlements awarded against the business

    These policies can also provide:

    Additional Coverage

    • Coverage for employee injuries, even if the business is not at fault
    • Protection against claims arising from products or services provided by the business
    • Coverage for claims made by contractors or subcontractors

    By obtaining small business indemnity insurance, businesses can safeguard their financial well-being and protect themselves from the potentially devastating consequences of lawsuits.

    Eligibility and Exclusions: Small Business Indemnity Insurance

    To qualify for small business indemnity insurance, businesses must meet certain eligibility criteria, including:

    • Being a legally registered business entity.
    • Operating within the policy’s defined business activities.
    • Having a proven track record of financial stability.

    Despite providing broad coverage, indemnity insurance policies typically exclude certain types of claims, such as:

    Common Exclusions

    • Intentional Acts:Damages or injuries caused by deliberate or malicious actions of the business or its employees.
    • Contractual Liabilities:Claims arising from breach of contracts or agreements.
    • Employee Injuries:Injuries sustained by employees while performing their job duties, which are typically covered by workers’ compensation insurance.
    • Property Damage:Physical damage to property owned or leased by the business.
    • Environmental Liability:Claims related to environmental damage or pollution caused by the business’s operations.

    Cost and Premiums

    The cost of small business indemnity insurance premiums is influenced by several factors, including the size of the business, the industry in which it operates, the number of employees, the coverage limits, and the deductible.

    Businesses can minimize their insurance costs by:

    Risk Management

    • Implementing strong risk management practices, such as regular safety inspections and employee training.
    • Maintaining a good claims history.
    • Working with an insurance broker to find the best coverage at the most competitive price.

    Claims Process and Dispute Resolution

    Small business indemnity insurance

    Filing a claim under a small business indemnity insurance policy typically involves the following steps:

    The policyholder must notify the insurer promptly after an incident occurs. This can usually be done by phone, email, or through the insurer’s online portal.

    The insurer will assign a claims adjuster to investigate the claim. The adjuster will gather evidence, interview witnesses, and determine the extent of the loss.

    Once the investigation is complete, the insurer will issue a settlement offer to the policyholder. The policyholder can accept or reject the offer.

    If the policyholder accepts the offer, the insurer will issue payment for the claim.

    If the policyholder rejects the offer, they can appeal the decision through the insurer’s internal dispute resolution process.

    Dispute Resolution

    If the policyholder is not satisfied with the insurer’s decision, they can appeal the decision through the insurer’s internal dispute resolution process.

    The internal dispute resolution process typically involves the following steps:

    1. The policyholder must submit a written appeal to the insurer.
    2. The insurer will review the appeal and make a decision.
    3. If the policyholder is still not satisfied with the decision, they can file a complaint with the state insurance commissioner.

    Concluding Remarks

    Business indemnity insurance

    In the ever-evolving business landscape, small business indemnity insurance emerges as a beacon of stability. It empowers entrepreneurs to take calculated risks, knowing that they have a financial cushion to fall back on. As businesses grow and expand, this insurance policy remains a steadfast companion, providing unwavering support and protection.

    FAQ Insights

    What types of businesses need small business indemnity insurance?

    Any small business that interacts with customers, clients, or the public can benefit from indemnity insurance. It’s particularly crucial for businesses that provide services or products that could potentially lead to bodily injury or property damage.

    How much does small business indemnity insurance cost?

    The cost of indemnity insurance varies depending on factors such as the size of the business, the industry, and the level of coverage required. It’s advisable to obtain quotes from multiple insurance providers to compare rates and find the most cost-effective option.

    What are the exclusions under a small business indemnity insurance policy?

    Common exclusions include intentional acts, criminal activities, and damage caused by pollution. It’s important to carefully review the policy to understand what is and isn’t covered.