Blog

  • Workers’ Compensation for Small Businesses: A Comprehensive Guide

    Workers’ Compensation for Small Businesses: A Comprehensive Guide

    Workers compensation for small business – Workers’ compensation for small businesses is a critical aspect of safeguarding employees and ensuring a safe and compliant workplace. This guide provides a comprehensive overview of workers’ compensation, its legal requirements, and best practices for managing claims and preventing workplace accidents.

    As a small business owner, understanding workers’ compensation is essential to protect your employees and your business. This guide will empower you with the knowledge and tools you need to navigate the complexities of workers’ compensation and ensure a safe and productive work environment.

    Understanding Workers’ Compensation for Small Businesses
    Workers compensation for small business

    Workers’ compensation is a type of insurance that provides financial protection to employees who suffer work-related injuries or illnesses. It helps cover medical expenses, lost wages, and other costs associated with the injury or illness.

    Workers’ compensation insurance is essential for small businesses because it helps protect them from financial liability in the event of a workplace accident. It also provides employees with peace of mind, knowing that they will be taken care of if they are injured on the job.

    Benefits and Coverage of Workers’ Compensation Insurance

    Workers’ compensation insurance provides a wide range of benefits to employees, including:

    • Medical expenses: Workers’ compensation insurance covers all medical expenses related to a work-related injury or illness, including doctor’s visits, hospital stays, and rehabilitation.
    • Lost wages: Workers’ compensation insurance provides benefits to employees who are unable to work due to a work-related injury or illness. These benefits are typically paid at a rate of two-thirds of the employee’s average weekly wage.
    • Disability benefits: Workers’ compensation insurance provides benefits to employees who are permanently disabled as a result of a work-related injury or illness. These benefits are typically paid for the rest of the employee’s life.
    • Death benefits: Workers’ compensation insurance provides benefits to the family of an employee who dies as a result of a work-related injury or illness. These benefits are typically paid in a lump sum.

    Workers’ compensation insurance also provides coverage for employers, including:

    • Liability protection: Workers’ compensation insurance protects employers from financial liability in the event of a workplace accident. This protection extends to both employees and third parties.
    • Reduced costs: Workers’ compensation insurance can help employers reduce their costs by providing coverage for medical expenses, lost wages, and other costs associated with workplace accidents.
    • Improved employee morale: Workers’ compensation insurance can help improve employee morale by providing employees with peace of mind, knowing that they will be taken care of if they are injured on the job.

    Common Workplace Injuries and Illnesses Covered Under Workers’ Compensation

    Workers’ compensation insurance covers a wide range of workplace injuries and illnesses, including:

    • Back injuries
    • Neck injuries
    • Head injuries
    • Broken bones
    • Cuts and lacerations
    • Burns
    • Repetitive stress injuries
    • Occupational diseases

    If you are injured or become ill on the job, it is important to report the injury or illness to your employer as soon as possible. Your employer will then file a workers’ compensation claim with their insurance company. The insurance company will investigate the claim and determine whether you are eligible for benefits.

    Legal Requirements and Considerations

    Workers’ compensation laws mandate that employers provide financial and medical benefits to employees who suffer work-related injuries or illnesses. These laws vary by state, but all require employers to carry workers’ compensation insurance to protect their employees.

    The type of workers’ compensation law applicable to a small business depends on the number of employees and the industry in which the business operates. Some states have mandatory coverage for all businesses with employees, while others have exemptions for small businesses with a certain number of employees.

    Penalties for Non-Compliance

    Failure to comply with workers’ compensation laws can result in significant penalties, including fines, imprisonment, and civil lawsuits. In addition, non-compliant businesses may be denied government contracts and face higher insurance premiums.

    Obtaining Workers’ Compensation Insurance: Workers Compensation For Small Business

    Compensation insurance

    Securing workers’ compensation insurance is crucial for small businesses to protect themselves and their employees. Choosing the right provider, understanding the process, and considering the factors affecting premiums are essential steps to ensure adequate coverage.

    Choosing the Right Provider, Workers compensation for small business

    Select an insurer with a strong financial standing, a proven track record in workers’ compensation, and excellent customer service. Consider factors such as industry specialization, claim handling capabilities, and competitive rates.

    Obtaining Workers’ Compensation Insurance

    The process typically involves completing an application, providing payroll and employee information, and undergoing a risk assessment. Factors influencing premiums include industry, payroll, number of employees, and past claims history.

    Benefits of Using a Broker or Agent

    Brokers or agents can provide valuable assistance by:

    • Comparing quotes from multiple insurers
    • Negotiating competitive rates
    • Providing ongoing support and guidance
    • Managing claims and ensuring compliance

    Managing Workers’ Compensation Claims

    Managing workers’ compensation claims involves a series of steps that ensure the timely and appropriate resolution of employee injuries or illnesses sustained on the job. Understanding the process and roles involved is crucial for small businesses to navigate claims effectively.

    The first step in managing a workers’ compensation claim is reporting the incident. This should be done promptly to the employer and the insurance carrier. The report should include details such as the employee’s name, date and time of the injury or illness, a description of the incident, and any witnesses.

    Once the claim is reported, the insurance carrier will assign a claims adjuster to investigate the claim. The claims adjuster will review the report, interview the employee, witnesses, and employer, and gather medical records to determine the extent of the injury or illness and the appropriate benefits.

    The claims adjuster will then make a decision on the claim. This decision may include approving or denying the claim, determining the amount of benefits to be paid, and establishing a treatment plan. The claims adjuster will also work with the employee and employer to ensure that the employee receives the necessary medical care and returns to work as soon as possible.

    Effective communication is essential throughout the claims process. Employees should keep the claims adjuster informed of their condition and any changes in their treatment plan. Employers should provide the claims adjuster with any relevant information about the employee’s job duties and work environment.

    By following these steps and maintaining open communication, small businesses can effectively manage workers’ compensation claims and ensure that their employees receive the benefits they are entitled to.

    Preventing Workplace Accidents and Injuries

    Workplace safety is paramount for small businesses to protect employees, reduce operational costs, and maintain a positive work environment. Small businesses often have limited resources, making it crucial to prioritize workplace safety to avoid costly accidents and injuries.

    Common workplace hazards include:

    • Slips, trips, and falls due to poor housekeeping or inadequate lighting
    • Cuts and lacerations from sharp objects or machinery
    • Overexertion or repetitive motion injuries
    • li>Exposure to hazardous chemicals or fumes

    • Electrical hazards

    Mitigating these hazards involves:

    • Regularly inspecting the workplace for potential hazards
    • Implementing safety protocols and procedures
    • Providing personal protective equipment (PPE) to employees
    • Training employees on safety practices
    • Encouraging employee involvement in safety committees or initiatives

    Safety Training and Employee Involvement

    Safety training empowers employees with the knowledge and skills to identify and avoid workplace hazards. It also promotes a culture of safety and accountability.

    Employee involvement in safety initiatives, such as safety committees or regular safety meetings, fosters a sense of ownership and responsibility among employees, encouraging them to actively participate in maintaining a safe workplace.

    Ending Remarks
    Workers compensation for small business

    In conclusion, workers’ compensation for small businesses is a vital aspect of risk management and employee protection. By understanding the legal requirements, choosing the right insurance provider, and implementing effective safety measures, small businesses can minimize the impact of workplace accidents and injuries, protect their employees, and ensure a thriving and compliant workplace.

    Popular Questions

    What is workers’ compensation insurance?

    Workers’ compensation insurance provides financial protection to employees who suffer work-related injuries or illnesses. It covers medical expenses, lost wages, and other benefits as mandated by law.

    What are the benefits of having workers’ compensation insurance?

    Workers’ compensation insurance protects both employees and employers. It ensures that injured employees receive necessary medical care and financial support, while protecting employers from potential lawsuits and financial liability.

    How do I choose the right workers’ compensation insurance provider?

    Consider factors such as the provider’s reputation, financial stability, coverage options, and customer service. It’s advisable to compare quotes from multiple providers to find the best fit for your business.

  • Apply for Emergency Money: Navigating Financial Crises

    Apply for Emergency Money: Navigating Financial Crises

    In the face of unexpected financial emergencies, knowing where to turn for help can make all the difference. Apply for emergency money provides a comprehensive guide to accessing financial assistance during times of crisis, empowering individuals to navigate the complexities of financial hardship with confidence.

    This detailed guide delves into various programs, strategies, and resources available to those in need, providing practical advice and actionable steps to secure emergency funds and regain financial stability.

    Financial Assistance Programs

    Apply for emergency money

    During times of financial crisis, various government and non-profit organizations offer emergency financial assistance programs to individuals and families in need. These programs provide temporary financial relief to cover essential expenses such as rent, utilities, food, and medical care.

    Eligibility criteria and application procedures vary depending on the specific program and the organization offering it. Some programs may have income or asset limits, while others may prioritize certain categories of individuals, such as families with children, seniors, or individuals with disabilities.

    Government Assistance Programs

    The federal government provides emergency financial assistance through various programs administered by the Department of Health and Human Services (HHS) and the Department of Housing and Urban Development (HUD).

    • Temporary Assistance for Needy Families (TANF):A block grant program that provides cash assistance to low-income families with children.
    • Supplemental Nutrition Assistance Program (SNAP):Provides food assistance to low-income individuals and families.
    • Emergency Rental Assistance Program (ERAP):Offers rental assistance to individuals and families who have been financially impacted by the COVID-19 pandemic.

    Non-Profit Assistance Programs

    Numerous non-profit organizations also provide emergency financial assistance to individuals and families in need.

    • United Way:Offers a variety of programs, including financial assistance for rent, utilities, and other essential expenses.
    • Salvation Army:Provides financial assistance for food, rent, and other basic needs.
    • Catholic Charities:Offers financial assistance, housing support, and other services to low-income individuals and families.

    Crowdfunding and Online Platforms

    Apply for emergency money

    Crowdfunding websites and platforms offer a valuable avenue for raising emergency funds by connecting individuals in need with potential donors. These platforms allow individuals to create campaigns outlining their financial needs and personal stories, making it easier for donors to understand and support their cause.

    Creating Effective Campaigns

    To create effective crowdfunding campaigns, it’s crucial to provide clear and concise information about the emergency situation, the specific financial need, and how the funds will be used. Using compelling storytelling, emotional appeals, and personal anecdotes can resonate with donors and increase the likelihood of contributions.

    Setting realistic fundraising goals and offering incentives or rewards for different donation levels can also boost campaign success.

    Negotiating with Creditors and Utility Providers

    Emergency fund savings money retirement why security step road funds

    When facing financial emergencies, it’s crucial to reach out to creditors and utility providers to explore options for payment deferrals or assistance programs.

    Negotiating with Creditors

    • Contact creditors promptly:Inform them about your financial situation and request a payment deferral or reduction in interest rates.
    • Explain your situation clearly:Provide details about your income, expenses, and any unexpected circumstances that led to the emergency.
    • Offer a payment plan:Suggest a revised payment schedule that you can afford, even if it’s a smaller amount than before.
    • Consider debt consolidation:Explore options to consolidate multiple debts into a single loan with a lower interest rate.
    • Seek professional advice:If negotiations become difficult, consider consulting with a credit counselor or attorney.

    Negotiating with Utility Providers

    • Contact utility companies directly:Explain your situation and inquire about any assistance programs or payment extensions they may offer.
    • Provide proof of financial hardship:Submit documentation, such as pay stubs, bank statements, or medical bills, to demonstrate your financial need.
    • Negotiate a payment plan:Discuss a revised payment schedule that aligns with your current financial situation.
    • Explore government assistance:Research local and federal programs that provide financial assistance for utility bills, such as LIHEAP (Low Income Home Energy Assistance Program).

    Budgeting and Expense Management

    During financial emergencies, creating and adhering to a strict budget is paramount. It provides a roadmap for allocating limited resources wisely, reducing expenses, increasing income, and prioritizing essential payments.

    Effective budgeting involves understanding your income and expenses, setting realistic goals, and making necessary adjustments along the way. By following a comprehensive approach, you can regain control of your finances and navigate the challenges of a financial crisis.

    Creating a Comprehensive Budget, Apply for emergency money

    • Track your income:Record all sources of income, including wages, salaries, investments, and government assistance.
    • Categorize your expenses:Divide expenses into essential (e.g., housing, food, utilities) and non-essential (e.g., entertainment, dining out).
    • Identify areas for reduction:Analyze non-essential expenses and identify areas where you can cut back, such as subscriptions, dining out, or entertainment.
    • Set realistic goals:Aim to reduce expenses gradually rather than making drastic cuts that may be unsustainable.

    Increasing Income

    • Explore additional income streams:Consider part-time work, freelance projects, or online gigs to supplement your income.
    • Negotiate with employers:If possible, request a salary increase or explore opportunities for additional responsibilities and bonuses.
    • Sell unwanted items:Declutter your home and sell items you no longer need to generate extra cash.

    Prioritizing Essential Payments

    • Pay rent or mortgage on time:Avoiding eviction or foreclosure is crucial for maintaining stable housing.
    • Cover essential utilities:Ensure access to basic necessities like electricity, gas, and water.
    • Make minimum debt payments:Prioritize high-interest debts and avoid falling into default.
    • Consider debt consolidation or restructuring:Explore options to lower interest rates or extend repayment terms.

    Legal Considerations and Resources: Apply For Emergency Money

    Applying for emergency money involves legal considerations that need to be understood. These include potential debt or credit issues that can arise. It is crucial to be aware of these implications and seek legal guidance if necessary.

    There are legal resources and organizations available to provide free or low-cost legal assistance to individuals seeking emergency money. These resources can help you understand your rights and responsibilities, navigate the legal process, and protect your interests.

    Legal Resources

    • Legal Aid Societies:Non-profit organizations that provide free or low-cost legal services to low-income individuals and families.
    • Pro Bono Attorneys:Lawyers who volunteer their time to provide free legal assistance to those in need.
    • Law School Clinics:Law schools that offer legal services to the public, often at a reduced cost or for free.
    • Government Agencies:Some government agencies, such as the Consumer Financial Protection Bureau (CFPB), provide resources and assistance to consumers facing financial challenges.
    • Online Legal Resources:Websites and databases that provide information about legal rights and resources, including those related to emergency money.

    Last Point

    Whether facing job loss, medical emergencies, or unexpected expenses, this guide serves as an invaluable resource, offering a lifeline during challenging times. By understanding the options available and implementing effective strategies, individuals can overcome financial obstacles and emerge from crises with renewed resilience.

    User Queries

    What are the eligibility criteria for government emergency financial assistance programs?

    Eligibility criteria vary depending on the program, but generally include factors such as income, assets, and financial need.

    How can I negotiate with creditors to reduce interest rates?

    Contact creditors directly to explain your situation and request a reduction in interest rates. Be prepared to provide documentation of your financial hardship.

    What are some strategies for reducing expenses during a financial emergency?

    Consider cutting back on non-essential spending, negotiating lower bills with service providers, and exploring income-generating opportunities.

  • Unveiling Low Business Insurance: A Lifeline for Small Businesses

    Unveiling Low Business Insurance: A Lifeline for Small Businesses

    As low business insurance takes center stage, this opening passage beckons readers with vivid imagery into a world crafted with expertise, ensuring a reading experience that is both absorbing and distinctly original. Low business insurance, a beacon of protection for small businesses, empowers them to navigate the complexities of financial risks and liabilities, paving the way for sustainable growth and success.

    Delving deeper, this comprehensive guide unravels the intricate tapestry of low business insurance, exploring its diverse types, cost-influencing factors, and the myriad benefits it bestows upon small businesses. Through real-world case studies and practical advice, we illuminate the path towards securing affordable and effective insurance solutions, empowering businesses to thrive in an ever-evolving landscape.

    Types of Low Business Insurance

    Low business insurance

    For low-income businesses, safeguarding your operations and finances is crucial. Various types of insurance coverage are available to cater to your specific needs.

    Understanding the different insurance options empowers you to make informed decisions and protect your business effectively.

    General Liability Insurance

    • Protects against claims of bodily injury, property damage, or personal injury caused by your business operations.
    • Essential for all businesses, regardless of size or industry.

    Property Insurance

    • Covers physical assets such as buildings, equipment, and inventory against damage or loss due to events like fire, theft, or natural disasters.
    • Tailor your coverage to the specific risks your business faces.

    Business Interruption Insurance

    • Provides financial compensation if your business is forced to close temporarily due to a covered event.
    • Covers expenses like lost revenue, employee wages, and ongoing expenses.

    Tailored Insurance Solutions

    Low-income businesses often have unique needs that require customized insurance solutions. Working with an experienced insurance agent can help you:

    • Assess your specific risks and coverage gaps.
    • Identify cost-effective policies that meet your budget.
    • Tailor your coverage to protect your business’s unique operations.

    Factors Affecting Low Business Insurance Costs

    Insurance premiums for low-income businesses are influenced by several key factors, including industry, location, and business size. Understanding these factors can help businesses minimize their insurance costs while maintaining adequate coverage.

    Industry

    The type of industry a business operates in significantly impacts its insurance costs. Businesses in high-risk industries, such as construction or manufacturing, typically face higher premiums due to the increased likelihood of accidents or property damage.

    Location

    The location of a business also plays a role in determining insurance costs. Businesses located in areas with higher crime rates or natural disaster risks may pay more for insurance than those in safer areas.

    Business Size

    The size of a business can affect insurance costs, with larger businesses generally paying more than smaller businesses. This is because larger businesses have more employees, more property, and more potential liabilities.

    Businesses can implement various strategies to reduce their insurance expenses without compromising coverage. These strategies include:

    • Increase deductibles:Raising deductibles can lower premiums, but businesses should ensure they can afford the higher out-of-pocket costs in the event of a claim.
    • Bundle policies:Combining multiple insurance policies, such as property and liability coverage, can often result in discounts.
    • Improve safety measures:Implementing safety measures, such as installing security systems or providing employee training, can reduce the likelihood of accidents or losses, leading to lower premiums.
    • Shop around for quotes:Comparing quotes from different insurance companies can help businesses find the most competitive rates.

    Benefits of Low Business Insurance

    Low business insurance

    For low-income businesses, obtaining insurance coverage is a crucial step towards securing their financial well-being. Insurance acts as a protective shield, safeguarding businesses from unexpected events that could potentially cripple their operations and jeopardize their survival.

    Insurance provides businesses with peace of mind, knowing that they are protected against financial risks and liabilities. It ensures that businesses can continue to operate even in the face of adversity, without the fear of catastrophic financial losses.

    Protection from Financial Risks

    • Insurance policies cover a wide range of risks, such as property damage, liability claims, and business interruptions. By transferring these risks to an insurance company, businesses can avoid the financial burden of unexpected events.
    • For instance, if a fire destroys a business’s premises, insurance coverage can provide the necessary funds to rebuild or replace the damaged property, allowing the business to resume operations quickly.

    Protection from Liabilities, Low business insurance

    • Insurance policies also protect businesses from legal liabilities. If a customer or employee is injured on the business premises, insurance coverage can help cover the costs of medical expenses and legal fees.
    • For example, if a customer slips and falls in a store, liability insurance can provide coverage for the resulting medical expenses and any potential legal claims.

    Peace of Mind and Security

    • Having insurance coverage provides business owners with peace of mind, knowing that they are protected against unforeseen circumstances. This sense of security allows them to focus on growing their business without the constant worry of financial setbacks.
    • Insurance policies offer a safety net, giving businesses the confidence to take calculated risks and pursue new opportunities, knowing that they have a financial cushion to fall back on if things go wrong.

    Finding Affordable Low Business Insurance

    Navigating the complexities of insurance can be daunting for low-income businesses. However, with the right strategies, you can find affordable low business insurance that meets your needs without breaking the bank.

    To begin, it’s crucial to shop around and compare quotes from multiple insurance providers. Utilize online comparison tools or consult with insurance brokers who can provide you with a comprehensive overview of available options. They can help you understand the different types of coverage, identify potential discounts, and negotiate competitive rates on your behalf.

    Role of Brokers and Agents

    Insurance brokers and agents play a vital role in securing affordable low business insurance. They have established relationships with multiple insurance companies and can leverage their expertise to find you the best coverage at the lowest cost. Brokers typically work on a commission basis, so their services are often free to you.

    Agents, on the other hand, are employed by specific insurance companies and may have limited options.

    Government Programs and Initiatives

    Depending on your location and business type, you may be eligible for government programs or initiatives that offer assistance with insurance costs. These programs can provide subsidies, grants, or tax breaks that can significantly reduce your insurance premiums. Research available programs in your area and explore their eligibility criteria.

    Case Studies of Low Business Insurance

    Liability

    Low business insurance can provide a lifeline for low-income businesses, helping them mitigate financial risks and protect their operations. Here are some real-world examples of how such insurance has made a positive impact:

    A Coffee Shop’s Story

    A small coffee shop in a low-income neighborhood was hit by a fire that destroyed its equipment and inventory. The shop’s owner had purchased a low-cost business insurance policy that covered the cost of replacing the damaged items, allowing him to reopen his business within a few weeks.

    A Hair Salon’s Success

    A hair salon in a rural area was sued by a client who claimed to have suffered an allergic reaction to a hair product. The salon’s low business insurance policy covered the legal expenses and settlement costs, preventing the business from facing financial ruin.

    A Construction Company’s Growth

    A construction company in an economically depressed area was able to secure a low-cost liability insurance policy. This insurance gave the company the confidence to take on larger projects, which led to increased revenue and business growth.

    Closing Summary

    In closing, low business insurance emerges as an indispensable tool for small businesses, safeguarding their financial well-being and fostering their growth aspirations. By embracing the insights and strategies Artikeld in this guide, business owners can navigate the insurance landscape with confidence, ensuring that their ventures are shielded from unforeseen risks and poised for long-term success.

    User Queries

    What types of coverage are typically included in low business insurance policies?

    Low business insurance policies typically cover a range of essential risks, including property damage, liability, business interruption, and crime.

    How can I find the most affordable low business insurance options?

    To secure the most affordable low business insurance options, consider comparing quotes from multiple providers, negotiating premiums, and exploring government programs that offer assistance.

    What are the key factors that influence low business insurance costs?

    Key factors that impact low business insurance costs include industry type, location, business size, claims history, and safety measures implemented.

  • Urgent Cash Help: Navigating Financial Emergencies with Confidence

    Urgent Cash Help: Navigating Financial Emergencies with Confidence

    In the face of unexpected financial emergencies, urgent cash help can provide a lifeline, empowering individuals to overcome short-term cash flow challenges. This comprehensive guide explores a range of options, strategies, and resources to assist individuals in securing the financial support they need.

    Whether navigating government assistance programs, seeking support from non-profit organizations, or considering private lending options, this guide provides detailed insights into the eligibility criteria, application processes, and potential benefits of each approach.

    Budgeting and Expense Management

    Urgent cash help

    Effective cash flow management requires a well-structured budget and diligent expense tracking. Creating a budget involves allocating funds to various categories based on income and financial goals. By monitoring expenses, individuals can identify areas for optimization and reduce unnecessary spending.

    Prioritizing Expenses, Urgent cash help

    Categorizing expenses is crucial for prioritizing needs. Essential expenses, such as housing, food, and healthcare, should be prioritized. Non-essential expenses, like entertainment and dining out, can be adjusted or reduced to free up cash flow for more important obligations.

    Financial Advisors and Counselors

    Individuals struggling with budgeting and expense management may benefit from consulting financial advisors or counselors. These professionals provide personalized guidance, help create realistic budgets, and offer strategies for reducing expenses. Their expertise can be invaluable for improving financial stability and achieving long-term financial goals.

    Debt Consolidation and Credit Repair: Urgent Cash Help

    Cash need urgent

    Struggling with high-interest debt? Debt consolidation and credit repair can provide a lifeline, helping you manage your finances and improve your credit score.

    Debt Consolidation

    Debt consolidation involves combining multiple debts into a single loan with a lower interest rate. This can significantly reduce your monthly payments and save you money on interest.

    • Choose a lender:Research different lenders and compare interest rates, loan terms, and fees.
    • Negotiate terms:Discuss the loan amount, repayment period, and interest rate with the lender.
    • Consolidate your debts:Use the loan proceeds to pay off your existing debts, leaving you with a single monthly payment.

    Credit Repair

    Credit repair involves improving your credit score by correcting errors, disputing negative information, and building positive credit history.

    • Obtain your credit report:Review your credit report for inaccuracies and dispute any errors.
    • Pay bills on time:Payment history is a major factor in your credit score. Make all payments on time, every time.
    • Keep credit utilization low:Use less than 30% of your available credit to show lenders you’re managing your credit responsibly.

    Income Generation Strategies

    When faced with urgent cash needs, exploring additional income streams can be crucial. From side hustles to freelance work, various opportunities exist to supplement your earnings. This guide will delve into the pros and cons of different income generation strategies and provide practical tips for finding and applying for suitable opportunities.

    Side hustles offer flexibility and the potential to earn extra cash in your spare time. Whether it’s driving for a ride-sharing service, delivering groceries, or offering your skills as a virtual assistant, there are numerous options to choose from. However, it’s important to consider the time commitment and potential earnings before jumping in.

    Part-Time Jobs

    Part-time jobs provide a more structured approach to income generation. They offer a regular income and the opportunity to develop new skills and gain experience. However, they typically require a set schedule and may not be as flexible as side hustles.

    Freelance Work

    Freelance work allows you to leverage your skills and expertise to earn income on a project-by-project basis. It offers great flexibility and the potential for high earnings, but it can also be competitive and requires strong self-management skills.

    To find suitable income-generating opportunities, explore online job boards, social media groups, and networking events. Be clear about your skills and availability, and tailor your applications to each opportunity.

    Personal Finance Education and Resources

    Financial literacy empowers individuals to make informed financial decisions, enabling them to effectively manage their cash flow, avoid debt traps, and plan for the future. It plays a crucial role in navigating urgent cash needs by providing the knowledge and skills to identify financial challenges, explore available options, and make sound choices.

    To enhance financial literacy, numerous reputable resources are available:

    Websites

    • NerdWallet:Comprehensive financial advice, tools, and calculators.
    • The Balance:In-depth articles on personal finance, investing, and retirement planning.
    • Investopedia:A vast encyclopedia of financial terms, concepts, and strategies.

    Books

    • “The Psychology of Money” by Morgan Housel:Explores the psychological biases that influence financial decisions.
    • “The Total Money Makeover” by Dave Ramsey:A practical guide to debt elimination and financial freedom.
    • “Rich Dad Poor Dad” by Robert Kiyosaki:Challenges traditional financial beliefs and promotes financial independence.

    Courses

    • Coursera:Online courses from top universities on financial planning, investing, and more.
    • edX:Offers financial literacy courses from institutions like MIT and Harvard.
    • Udemy:Provides affordable online courses on various financial topics.

    Seeking professional financial advice can be invaluable when facing significant financial challenges. A qualified financial advisor can provide personalized guidance, analyze your financial situation, and develop a tailored plan to address your urgent cash needs and long-term financial goals.

    Final Wrap-Up

    Urgent cash help

    By understanding the financial assistance options available, implementing effective budgeting and expense management techniques, and exploring creative income generation strategies, individuals can proactively address urgent cash needs and achieve financial stability. Remember, financial literacy is a powerful tool that can empower you to make informed decisions and navigate financial challenges with confidence.

    Essential FAQs

    What are the eligibility requirements for government financial assistance programs?

    Eligibility requirements vary depending on the specific program. Generally, factors such as income level, household size, and financial need are considered.

    How can I improve my credit score?

    Making on-time payments, reducing debt utilization, and disputing any errors on your credit report can all contribute to improving your credit score.

    What are the benefits of debt consolidation?

    Debt consolidation can simplify debt repayment, potentially lower interest rates, and improve credit scores.

  • Cheap LLC Business Insurance: A Comprehensive Guide to Protect Your Business

    Cheap LLC Business Insurance: A Comprehensive Guide to Protect Your Business

    Cheap LLC business insurance is an essential investment for any business owner who wants to protect their company from financial ruin. This guide will provide you with everything you need to know about cheap LLC business insurance, from the different types of coverage available to the factors that affect the cost of insurance.

    We’ll also compare different insurance providers and discuss the benefits of using online insurance marketplaces.

    By the end of this guide, you’ll be able to make an informed decision about the best cheap LLC business insurance for your needs.

    Insurance Coverage Options

    Cheap llc business insurance

    Protecting your LLC business with comprehensive insurance coverage is essential for mitigating risks and safeguarding your financial well-being. Various coverage options are available, each tailored to specific business needs and potential liabilities. Understanding the benefits and limitations of each type is crucial for selecting the optimal coverage for your enterprise.

    When selecting the right coverage, consider the nature of your business operations, the potential risks involved, and your financial capacity. It’s advisable to consult with an insurance professional to determine the most suitable coverage options for your specific business requirements.

    Liability Insurance

    Liability insurance protects your business against claims arising from injuries or property damage caused to third parties due to your business operations. It safeguards your business assets and financial stability in the event of legal actions or settlements.

    • General Liability Insurance:Covers common risks such as bodily injury, property damage, and personal injury.
    • Professional Liability Insurance:Protects professionals against claims of negligence or errors and omissions in their services.
    • Product Liability Insurance:Protects businesses against claims arising from injuries or damages caused by defective products.

    Property Insurance

    Property insurance safeguards your business premises, equipment, and inventory against physical damage or loss due to events such as fire, theft, or natural disasters. It provides financial compensation to repair or replace damaged assets, ensuring business continuity.

    • Commercial Property Insurance:Covers buildings, equipment, and inventory at your business location.
    • Business Interruption Insurance:Provides coverage for lost income and expenses if your business is forced to close due to a covered event.

    Business Vehicle Insurance

    If your business involves the use of vehicles, business vehicle insurance is essential to protect against liability and financial losses arising from accidents or damage to vehicles. It ensures your business is covered in case of unforeseen events involving company-owned or leased vehicles.

    • Commercial Auto Insurance:Covers liability, collision, and comprehensive coverage for business-owned vehicles.
    • Hired and Non-Owned Auto Insurance:Protects businesses that use employee-owned or rented vehicles for business purposes.

    Workers’ Compensation Insurance

    Workers’ compensation insurance provides benefits to employees who suffer work-related injuries or illnesses. It covers medical expenses, lost wages, and rehabilitation costs, protecting your business from financial liability and ensuring employee well-being.

    Other Coverage Options

    Depending on your industry and specific business needs, additional coverage options may be available to enhance your protection. These include:

    • Cyber Liability Insurance:Protects against financial losses and legal liability arising from data breaches, cyberattacks, or privacy violations.
    • Directors and Officers Insurance:Protects company directors and officers against personal liability for decisions made in their official capacity.
    • Errors and Omissions Insurance:Covers professionals against claims of negligence or errors in performing their services.

    Factors Affecting Insurance Costs: Cheap Llc Business Insurance

    Insurance llc talent strategy title book bankruptcy 3d business complete guide preview

    The cost of LLC business insurance is influenced by several key factors, including the nature of your business, its size, location, and claims history. By understanding these factors and taking steps to mitigate them, you can lower your insurance premiums and protect your business from financial risks.

    Industry and Business Activities

    The type of business you operate significantly impacts your insurance costs. Businesses with higher risks, such as those involving hazardous materials or heavy machinery, will typically pay higher premiums. Similarly, businesses with a history of claims or lawsuits are considered higher risk and will face increased insurance costs.

    Business Size and Revenue

    Larger businesses with higher revenue tend to have higher insurance costs due to their increased exposure to risks. This is because larger businesses typically have more employees, more assets, and more complex operations, all of which can contribute to a higher likelihood of accidents or claims.

    Location

    The location of your business can also affect your insurance costs. Businesses located in areas with higher crime rates or natural disaster risks will typically pay higher premiums. This is because insurance companies consider these areas to be more susceptible to claims and losses.

    Claims History

    Your business’s claims history is a major factor in determining your insurance costs. Businesses with a history of frequent or large claims will be considered higher risk and will face increased premiums. It is important to maintain a good claims history by promptly reporting and resolving any accidents or incidents that occur.

    Comparison of Insurance Providers

    To secure the most suitable and affordable LLC business insurance, it’s crucial to compare offerings from various insurance providers. This comprehensive comparison will empower you to make informed decisions, ensuring your business is adequately protected without breaking the bank.

    To facilitate your research, we’ve compiled a detailed table outlining the coverage options, premiums, and customer service ratings of several reputable insurance providers. This table will provide you with a clear overview of the key factors to consider when choosing an insurance provider.

    Coverage Options

    When evaluating insurance providers, it’s essential to scrutinize their coverage options. Ensure that the policies they offer align with the specific risks and exposures faced by your LLC. Consider factors such as general liability, property damage, business interruption, and professional liability coverage.

    Premiums

    Insurance premiums can vary significantly among providers. It’s crucial to compare quotes from multiple insurers to secure the most competitive rates without compromising coverage. Remember to consider both the initial premium and any potential discounts or incentives offered.

    Customer Service

    Exceptional customer service is invaluable when dealing with insurance matters. Research the reputation of each provider for responsiveness, helpfulness, and claims handling efficiency. Positive customer reviews and testimonials can provide valuable insights into the quality of service you can expect.

    Online Insurance Marketplaces

    Online insurance marketplaces are websites or platforms that aggregate quotes from multiple insurance companies, allowing businesses to compare and purchase insurance policies directly online. These marketplaces offer several advantages to businesses seeking cheap LLC business insurance:

    • Convenience:Businesses can access multiple quotes from the comfort of their own office or home, saving time and effort.
    • Transparency:Marketplaces typically display detailed information about each policy, making it easier for businesses to understand and compare coverage options.
    • Competitive pricing:By bringing together multiple insurers, marketplaces encourage competition, which can result in lower premiums for businesses.

    Drawbacks of Using Online Insurance Marketplaces

    • Limited options:Not all insurance companies participate in online marketplaces, so businesses may not have access to the full range of options available in the market.
    • Lack of personalized advice:Marketplaces typically do not provide personalized insurance advice, so businesses may need to consult with an insurance agent to ensure they are getting the right coverage.
    • Hidden fees:Some marketplaces may charge additional fees for using their services, which can increase the overall cost of insurance.

    Tips for Navigating Online Insurance Marketplaces

    • Gather information:Before visiting an online marketplace, gather information about your business, including its industry, size, and specific insurance needs.
    • Compare quotes:Obtain quotes from multiple insurance companies to compare coverage and premiums.
    • Read the fine print:Carefully review the terms and conditions of each policy before purchasing to ensure you understand the coverage and exclusions.
    • Consider your needs:Choose a policy that provides the coverage you need at a price you can afford.

    Tips for Saving on Insurance Costs

    Cheap llc business insurance

    Managing the cost of LLC business insurance is essential for businesses to maintain financial stability and protect their operations. By implementing effective strategies, businesses can reduce their insurance premiums while ensuring adequate coverage.

    To effectively manage insurance costs, businesses should consider the following tips:

    Negotiating Lower Premiums

    Negotiating with insurance providers can be an effective way to secure lower premiums. Businesses should:

    • Research and compare quotes from multiple providers to identify the most competitive options.
    • Provide detailed information about their business operations and risk management practices to demonstrate a low-risk profile.
    • Consider increasing deductibles or adjusting coverage limits to reduce premiums while maintaining adequate protection.

    Bundling Coverage

    Bundling multiple insurance policies, such as general liability, property, and workers’ compensation insurance, with the same provider can often lead to cost savings.

    Insurance providers may offer discounts for bundling coverage, as it reduces their administrative costs and streamlines the insurance process for businesses.

    Improving Risk Management Practices

    Implementing proactive risk management practices can significantly reduce the likelihood of accidents or incidents, leading to lower insurance premiums.

    • Regularly inspect and maintain equipment and facilities to prevent accidents.
    • Provide employee training programs on safety and risk management.
    • Establish clear policies and procedures to minimize potential hazards.

    Real-World Examples, Cheap llc business insurance

    Several businesses have successfully implemented these strategies to save on their insurance costs:

    • A manufacturing company reduced its general liability premium by 15% by negotiating a higher deductible and bundling its coverage with the same provider.
    • A retail store implemented a comprehensive safety program, resulting in a 10% reduction in its workers’ compensation insurance premium.
    • A healthcare clinic improved its risk management practices, including patient screening and staff training, leading to a 20% reduction in its professional liability insurance premium.

    By following these tips and implementing effective risk management practices, businesses can effectively manage their insurance costs while ensuring adequate protection for their operations.

    Ending Remarks

    Cheap LLC business insurance is an essential part of any business plan. By understanding the different types of coverage available and the factors that affect the cost of insurance, you can make an informed decision about the best policy for your business.
    We encourage you to compare quotes from different insurance providers and use online insurance marketplaces to find the best deal on cheap LLC business insurance.

    Helpful Answers

    What is cheap LLC business insurance?

    Cheap LLC business insurance is a type of insurance that provides financial protection for LLCs (limited liability companies). It can cover a variety of risks, including property damage, liability, and business interruption.

    How much does cheap LLC business insurance cost?

    The cost of cheap LLC business insurance varies depending on a number of factors, including the size of your business, the industry you’re in, and the amount of coverage you need. However, there are a number of ways to save money on cheap LLC business insurance, such as bundling your coverage and negotiating lower premiums.

    What are the benefits of cheap LLC business insurance?

    Cheap LLC business insurance can provide a number of benefits for your business, including:

    • Financial protection from unexpected events
    • Peace of mind knowing that your business is protected
    • Improved access to credit
    • Enhanced customer confidence
  • Get Emergency Money for Bills Fast: A Lifeline in Financial Storms

    Get Emergency Money for Bills Fast: A Lifeline in Financial Storms

    Get emergency money for bills fast – In the face of unexpected financial emergencies, accessing quick cash to cover pressing bills can be a daunting task. Fortunately, there are a myriad of options available to help you navigate these challenging times. From government assistance programs to alternative income sources, this comprehensive guide will illuminate your path to securing emergency funds and regaining financial stability.

    Financial Assistance Programs

    Various government and non-profit organizations offer emergency financial assistance to individuals and families facing financial hardship. These programs provide grants, loans, or other forms of support to help cover essential expenses such as rent, utilities, food, and medical bills.

    Eligibility Criteria

    Eligibility for financial assistance programs typically depends on factors such as income, household size, and financial need. Applicants must demonstrate that they are facing a temporary financial crisis and have exhausted other resources.

    Application Procedures

    Application procedures vary depending on the program. Some programs require in-person applications, while others can be submitted online or by mail. Applicants may need to provide documentation to verify their income, expenses, and financial need.

    Potential Benefits, Get emergency money for bills fast

    Financial assistance programs can provide a lifeline for individuals and families facing financial hardship. Benefits may include:

    • Grants or loans to cover essential expenses
    • Counseling and financial planning services
    • Referrals to other community resources

    Comparison of Programs

    The following table compares some of the most common financial assistance programs:

    Program Eligibility Benefits Application
    Temporary Assistance for Needy Families (TANF) Low-income families with children Cash assistance, food stamps, child care In-person application
    Supplemental Nutrition Assistance Program (SNAP) Low-income individuals and families Food stamps Online or in-person application
    Emergency Rental Assistance Program (ERAP) Individuals and families facing eviction Rental assistance, utility assistance Online or in-person application
    Low Income Home Energy Assistance Program (LIHEAP) Low-income households Heating and cooling assistance In-person application
    Salvation Army Emergency Financial Assistance Individuals and families facing financial hardship Grants, food assistance, counseling In-person application

    Short-Term Loans and Payday Advances

    Moneycrashers

    When faced with unexpected expenses or a financial emergency, short-term loans and payday advances can provide quick access to cash. However, these types of loans come with unique features and risks that borrowers should be aware of.

    Finding Reputable Lenders and Comparing Loan Terms

    Finding reputable lenders is crucial to avoid predatory practices and excessive interest rates. Research different lenders online, read reviews, and check their licensing and regulation status. Carefully compare loan terms, including interest rates, fees, and repayment periods. Opt for lenders with transparent terms and no hidden charges.

    Avoiding Predatory Practices

    Predatory lenders often target vulnerable borrowers with exorbitant interest rates and unfair loan terms. To avoid falling prey to such practices, be wary of lenders who pressure you into signing contracts without providing ample time to review them. Look out for lenders who advertise “no credit check” loans, as these typically come with higher interest rates and fees.

    Budgeting and Managing Debt Effectively

    Using short-term loans or payday advances requires careful budgeting and debt management. Create a realistic budget that includes loan repayments and other expenses. Avoid taking on more debt than you can afford to repay. If possible, consider consolidating multiple debts into a single loan with a lower interest rate to reduce monthly payments.

    Alternative Income Sources: Get Emergency Money For Bills Fast

    In the face of financial emergencies, exploring creative ways to generate additional income can provide a lifeline. From gig economy jobs to freelance work and selling unwanted items, there are numerous options to supplement your regular income quickly.

    Gig Economy Jobs

    The gig economy offers flexible and often short-term work opportunities through platforms like Uber, Lyft, and TaskRabbit. These jobs allow you to choose when and where you work, making them ideal for those seeking immediate income.

    Freelance Work

    Freelance platforms such as Upwork and Fiverr connect you with clients worldwide, enabling you to offer your skills in writing, design, coding, and more. Freelancing provides flexibility and the potential for higher earnings, but requires self-motivation and a strong work ethic.

    Selling Unwanted Items

    Declutter your home and earn some extra cash by selling unwanted items online or through consignment stores. Websites like eBay, Craigslist, and Facebook Marketplace make it easy to list and sell your pre-loved belongings.

    Debt Consolidation and Credit Counseling

    Get emergency money for bills fast

    Overwhelming bills can be a major source of stress and anxiety. Fortunately, there are several options available to help you manage your debt, including debt consolidation and credit counseling.

    Debt Consolidation

    Debt consolidation involves combining multiple debts into a single, lower-interest loan. This can make it easier to manage your payments and potentially save you money on interest.

    There are two main types of debt consolidation loans: secured and unsecured.

    • Secured debt consolidation loansare backed by collateral, such as your home or car. This means that if you default on the loan, the lender can seize your collateral.
    • Unsecured debt consolidation loansare not backed by collateral. This means that if you default on the loan, the lender cannot seize your assets.

    Credit Counseling

    Credit counselors are non-profit organizations that can help you create a budget, manage your debt, and improve your credit score.

    Credit counselors can provide you with a variety of services, including:

    • Budgeting assistance
    • Debt management plans
    • Credit counseling
    • Negotiation with creditors

    Budgeting and Expense Management

    Managing your finances effectively requires creating a budget and tracking expenses to control spending. This process involves setting financial goals, prioritizing expenses, and seeking professional help if needed. By implementing these strategies, you can gain control over your finances and achieve financial stability.

    Creating a Budget

    A budget is a plan that Artikels your income and expenses over a specific period, typically a month. To create a budget, start by tracking your income from all sources, including wages, salaries, investments, and government benefits.

    Next, list your expenses, which can be categorized as fixed (e.g., rent, mortgage, car payment) or variable (e.g., groceries, entertainment, dining out). Fixed expenses remain relatively constant each month, while variable expenses can fluctuate.

    Once you have a clear understanding of your income and expenses, you can allocate funds to different categories. Use a budgeting app or spreadsheet to track your expenses and ensure you stay within your budget.

    Tracking Expenses

    Regularly tracking your expenses is crucial for identifying areas where you can save money. Keep receipts, use a budgeting app, or review your bank statements to monitor your spending habits.

    By tracking expenses, you can identify unnecessary purchases, reduce impulse spending, and make informed decisions about your financial choices.

    Reducing Unnecessary Spending

    To reduce unnecessary spending, consider the following strategies:

    • Create a shopping list and stick to it when grocery shopping.
    • Compare prices before making purchases.
    • Negotiate lower rates on bills, such as insurance premiums or phone plans.
    • Consider downsizing your living space or car to lower housing or transportation costs.
    • Cook meals at home instead of dining out.

    Seeking Professional Help

    If you struggle to manage your finances effectively, consider seeking professional help from a financial advisor or credit counselor. These experts can provide personalized guidance, help you create a budget, and develop strategies to reduce debt and improve your financial situation.

    Closing Notes

    Get emergency money for bills fast

    Remember, financial emergencies can strike at any moment, but with the knowledge and resources Artikeld in this guide, you can confidently weather these storms. Embrace the strategies presented here to alleviate financial stress, secure emergency funds, and regain control of your financial well-being.

    Expert Answers

    What are the eligibility criteria for government financial assistance programs?

    Eligibility criteria vary depending on the program. Generally, factors such as income level, household size, and financial need are considered.

    How can I find reputable short-term loan lenders?

    Look for lenders with a proven track record, transparent loan terms, and competitive interest rates. Check online reviews and consult with trusted financial advisors.

    What are the risks associated with payday advances?

    Payday advances often come with high interest rates and short repayment periods, which can lead to a cycle of debt if not managed responsibly.

    How can debt consolidation help me manage overwhelming bills?

    Debt consolidation combines multiple debts into a single loan with a lower interest rate, simplifying repayment and potentially reducing overall debt.

  • Discover Cheap Small Business Insurance Near You: A Comprehensive Guide

    Discover Cheap Small Business Insurance Near You: A Comprehensive Guide

    In the realm of small business, securing affordable insurance is paramount. “Cheap small business insurance near me” embarks on a journey to unravel the intricacies of this essential topic, guiding you towards the most competitive rates and reliable coverage options.

    As we delve into this comprehensive guide, we’ll explore the diverse insurance policies tailored to small businesses, connect you with local experts, and empower you with online tools to compare quotes seamlessly. Join us as we navigate the complexities of small business insurance, ensuring your enterprise thrives in the face of unforeseen circumstances.

    Affordable Insurance Options for Small Businesses: Cheap Small Business Insurance Near Me

    Small businesses face unique risks and challenges, and securing affordable insurance is crucial for their financial well-being. Various types of insurance coverage are available, tailored to protect small businesses from potential liabilities and losses.

    Factors influencing insurance premiums include business size, industry, location, and claims history. Understanding these factors can help small businesses make informed decisions and secure the most competitive rates.

    Insurance Providers Offering Competitive Rates

    • The Hartford:Known for its customizable policies and competitive rates for small businesses in various industries.
    • State Farm:Offers a range of insurance options, including business owner’s policies (BOPs), with discounts for bundling coverage.
    • Progressive:Provides affordable insurance solutions for small businesses, with flexible payment plans and online quoting options.

    Local Insurance Brokers and Agents

    In your local area, there are experienced insurance brokers and agents who can help you find the most affordable insurance solutions for your small business. These professionals have a deep understanding of the local insurance market and can guide you through the process of selecting the right coverage at the right price.

    Benefits of Working with a Local Broker or Agent

    • Personalized service: Local brokers and agents take the time to get to know your business and your unique insurance needs. They can provide tailored advice and recommendations based on your specific situation.
    • Access to exclusive discounts: Local brokers and agents often have access to exclusive discounts and promotions that are not available to the general public. These discounts can save you money on your insurance premiums.
    • Claims support: In the event of a claim, a local broker or agent can help you navigate the claims process and ensure that you receive a fair settlement.

    Online Insurance Marketplaces

    Cheap small business insurance near me

    Online insurance marketplaces provide a convenient and efficient way for small businesses to compare and purchase insurance policies. These platforms offer a wide range of insurance options from multiple insurance companies, allowing businesses to find the best coverage for their needs at competitive rates.

    Using an online insurance marketplace offers several advantages for small businesses:

    • Convenience:Businesses can easily compare multiple quotes from different insurers without having to contact each company individually.
    • Time-saving:Online marketplaces streamline the insurance shopping process, saving businesses time and effort.
    • Access to a wide range of options:Marketplaces offer a comprehensive selection of insurance policies, ensuring businesses can find the coverage they need.
    • Competitive pricing:By comparing quotes from multiple insurers, businesses can secure the most affordable coverage.

    Some reputable online insurance marketplaces include:

    • Insureon
    • CoverWallet
    • Simply Business
    • li>Next Insurance

    • The Hartford

    It’s important to note that while online insurance marketplaces offer many benefits, they also have some potential drawbacks:

    • Limited personal interaction:Businesses may miss out on the personalized advice and guidance they might receive from an insurance agent.
    • Complexity:Some insurance policies can be complex, and businesses may need assistance understanding the coverage details.

    Overall, online insurance marketplaces provide a valuable resource for small businesses seeking affordable and comprehensive insurance coverage. By carefully considering the pros and cons, businesses can determine if an online marketplace is the right choice for their insurance needs.

    Insurance Comparison Tools

    Mccay dickey

    In today’s digital age, small businesses have access to a wide range of online tools that can help them compare insurance quotes from multiple providers. These tools make it easier for businesses to find the best coverage at the most affordable price.

    Insurance comparison tools typically work by gathering information about your business, such as your industry, number of employees, and annual revenue. They then use this information to generate a list of insurance providers that offer coverage for your specific needs.

    Popular Insurance Comparison Tools

    • Insureon:Insureon is a leading provider of online insurance comparison tools for small businesses. They offer a wide range of insurance products, including general liability, professional liability, property insurance, and workers’ compensation.
    • The Hartford:The Hartford is another popular provider of insurance comparison tools for small businesses. They offer a variety of insurance products, including business owners’ policies, commercial auto insurance, and cyber liability insurance.
    • CoverWallet:CoverWallet is an online insurance marketplace that allows small businesses to compare quotes from multiple providers. They offer a variety of insurance products, including general liability, professional liability, property insurance, and workers’ compensation.

    Using an insurance comparison tool can save you a significant amount of time and money. By comparing quotes from multiple providers, you can ensure that you are getting the best coverage at the most affordable price.

    Tips for Negotiating Lower Premiums

    Negotiating lower insurance premiums is a smart way to save money on your business expenses. Here are some tips to help you get the best deal on your insurance coverage:

    Understand your insurance policy and coverage limits.Before you start negotiating, it’s important to understand what your insurance policy covers and what your coverage limits are. This will help you determine what you need to negotiate for.

    Bundling Insurance Policies, Cheap small business insurance near me

    Bundling your insurance policies can save you money on your premiums. When you bundle your policies, you’re essentially buying multiple policies from the same insurance company. This can result in a discount on your premiums, as the insurance company is able to offer you a lower rate for multiple policies.

    Maintaining a Good Claims History

    Maintaining a good claims history is one of the best ways to keep your insurance premiums low. Insurance companies view businesses with a good claims history as less risky, and they’re willing to offer them lower premiums as a result.

    Final Summary

    Cheap small business insurance near me

    In conclusion, finding cheap small business insurance near you is a strategic endeavor that requires careful consideration of your business needs, industry, and budget. By leveraging the insights and resources Artikeld in this guide, you can confidently secure affordable coverage that safeguards your enterprise against potential risks.

    Embrace the power of knowledge and empower your small business with the protection it deserves.

    Answers to Common Questions

    What factors influence small business insurance premiums?

    Premiums are determined by factors such as business size, industry, location, claims history, and coverage limits.

    How can I compare insurance quotes efficiently?

    Utilize online insurance comparison tools that allow you to compare quotes from multiple providers simultaneously.

    What are the benefits of working with a local insurance broker?

    Local brokers provide personalized service, access to exclusive discounts, and expert guidance in finding the most suitable coverage for your business.

  • American Express Savings Bank: A Comprehensive Guide to Services, Benefits, and Fees

    American Express Savings Bank: A Comprehensive Guide to Services, Benefits, and Fees

    Welcome to the world of American Express Savings Bank, where financial empowerment takes center stage. With a rich history and a steadfast commitment to customer satisfaction, American Express Savings Bank has emerged as a leading financial institution, offering a diverse range of services and products tailored to meet the evolving needs of its discerning clientele.

    As we delve into the intricacies of American Express Savings Bank, we will uncover the benefits that set it apart, explore its competitive advantages, and provide valuable insights into its fees and charges. Through customer reviews and expert analysis, we aim to empower you with the knowledge you need to make informed financial decisions.

    Overview of American Express Savings Bank

    American Express Savings Bank, a division of American Express Company, was established in 1994 as a federally chartered savings bank. It offers a range of financial products and services to individuals and small businesses, including high-yield savings accounts, certificates of deposit (CDs), and personal loans.

    Target Audience

    American Express Savings Bank primarily targets individuals and small businesses seeking competitive interest rates on their savings and seeking access to affordable credit options. The bank’s focus on high-yield savings accounts and CDs appeals to those looking to maximize their returns on cash deposits.

    Market Share

    While American Express Savings Bank is not among the largest savings banks in the United States, it has a loyal customer base and a strong reputation for providing competitive rates and personalized service. The bank’s market share is primarily concentrated in the United States, with a particular focus on urban and suburban areas.

    Benefits and Features of American Express Savings Bank

    American Express Savings Bank offers a wide range of benefits and features to its customers, including:

    High-yield savings accounts, American express savings bank

    American Express Savings Bank offers competitive interest rates on its savings accounts, making it a great option for customers who are looking to grow their savings over time. The bank also offers a variety of savings accounts to choose from, so customers can find the account that best meets their needs.

    No-fee checking accounts

    American Express Savings Bank offers no-fee checking accounts, making it a great option for customers who are looking to save money on banking fees. The bank also offers a variety of checking accounts to choose from, so customers can find the account that best meets their needs.

    Online and mobile banking

    American Express Savings Bank offers online and mobile banking, making it easy for customers to manage their accounts from anywhere. Customers can use the bank’s website or mobile app to check their balances, transfer money, and pay bills.

    24/7 customer service

    American Express Savings Bank offers 24/7 customer service, so customers can always get help when they need it. The bank’s customer service representatives are available by phone, email, and chat.

    How to maximize the benefits of banking with American Express Savings Bank

    There are a number of ways to maximize the benefits of banking with American Express Savings Bank. Here are a few tips:

    • Choose the right savings account. American Express Savings Bank offers a variety of savings accounts to choose from, so it’s important to choose the account that best meets your needs.
    • Take advantage of no-fee checking accounts. American Express Savings Bank offers no-fee checking accounts, so you can save money on banking fees.
    • Use online and mobile banking. American Express Savings Bank offers online and mobile banking, making it easy to manage your accounts from anywhere.
    • Take advantage of 24/7 customer service. American Express Savings Bank offers 24/7 customer service, so you can always get help when you need it.

    Fees and Charges of American Express Savings Bank

    American Express Savings Bank charges various fees and charges for its savings accounts. Understanding these fees is crucial for customers to make informed decisions about their banking needs.

    The fees and charges of American Express Savings Bank are generally comparable to those of other banks in the industry. However, it is important to compare the specific fees that apply to your individual banking needs before making a decision.

    Account Maintenance Fees

    American Express Savings Bank charges a monthly maintenance fee of $5 for its basic savings account. This fee can be waived if you maintain a minimum balance of $300 in your account.

    Transaction Fees

    American Express Savings Bank charges a fee of $0.50 for each ATM withdrawal you make from a non-American Express ATM. There is no fee for ATM withdrawals made from American Express ATMs.

    American Express Savings Bank also charges a fee of $3 for each wire transfer you send or receive. There is no fee for online bill payments.

    Other Fees

    American Express Savings Bank may charge other fees for services such as stop payments, returned checks, and overdrafts. It is important to review the bank’s fee schedule carefully before opening an account.

    Customer Reviews and Feedback

    American express savings bank

    American Express Savings Bank has received mixed reviews and feedback from its customers. Some customers have praised the bank’s competitive interest rates, mobile banking features, and customer service, while others have expressed concerns about account fees and a limited branch network.

    To provide a balanced perspective, we have organized the customer reviews into positive and negative categories, highlighting the common themes and concerns raised by customers.

    Positive Reviews

    • Competitive interest rates:Many customers have praised American Express Savings Bank for offering competitive interest rates on savings accounts and certificates of deposit (CDs).
    • Mobile banking features:Customers appreciate the bank’s user-friendly mobile banking app, which allows them to manage their accounts, deposit checks, and transfer funds easily.
    • Customer service:American Express Savings Bank has received positive feedback for its responsive and helpful customer service team, which is available via phone, email, and online chat.

    Negative Reviews

    • Account fees:Some customers have complained about the bank’s account fees, which can include monthly maintenance fees and transaction fees.
    • Limited branch network:American Express Savings Bank has a limited branch network, which may be inconvenient for customers who prefer in-person banking.
    • Hidden fees:A few customers have reported encountering hidden fees that were not disclosed during the account opening process.

    Alternatives to American Express Savings Bank

    Savings express american personal minimum balance rates great glance

    American Express Savings Bank offers a range of banking products and services, but it’s not the only option available. There are several alternative banks that offer similar features and benefits, each with its own unique strengths and weaknesses. Here’s a comparison of some of the most popular alternatives:

    Ally Bank

    • Offers a wide range of savings and investment accounts with competitive interest rates.
    • No monthly maintenance fees or minimum balance requirements.
    • Excellent customer service and online banking platform.
    • Limited branch network, so may not be convenient for in-person banking.

    Capital One 360

    • High-yield savings account with no monthly maintenance fees or minimum balance requirements.
    • Wide range of other banking products, including checking accounts, CDs, and IRAs.
    • No physical branches, so all banking must be done online or through the mobile app.
    • Excellent customer service and online banking platform.

    Discover Bank

    • High-yield savings account with no monthly maintenance fees or minimum balance requirements.
    • Wide range of other banking products, including checking accounts, CDs, and IRAs.
    • Limited branch network, but offers a network of ATMs for cash withdrawals and deposits.
    • Excellent customer service and online banking platform.

    Recommendations

    The best alternative to American Express Savings Bank for you will depend on your specific needs and preferences. If you’re looking for a high-yield savings account with no monthly maintenance fees or minimum balance requirements, Ally Bank, Capital One 360, or Discover Bank are all excellent options.

    If you prefer a bank with a physical branch network, Capital One 360 or Discover Bank may be a better choice. And if you’re looking for a bank with a wide range of banking products and services, American Express Savings Bank, Ally Bank, or Discover Bank are all good options.

    Final Thoughts

    American express savings bank

    In the tapestry of banking institutions, American Express Savings Bank stands out as a beacon of financial innovation and customer-centricity. Its unwavering dedication to providing exceptional services, coupled with its competitive fees and charges, has solidified its position as a trusted partner in the pursuit of financial well-being.

    Whether you seek a reliable haven for your savings, a gateway to financial growth, or personalized financial advice, American Express Savings Bank is the destination where your financial aspirations take flight.

    FAQ Compilation

    What sets American Express Savings Bank apart from its competitors?

    American Express Savings Bank distinguishes itself through its exceptional customer service, innovative digital banking platform, and competitive interest rates on savings accounts.

    Are there any account maintenance fees associated with American Express Savings Bank accounts?

    Yes, there is a monthly account maintenance fee of $5. However, this fee can be waived if you maintain a minimum balance of $300 in your account.

    How can I access my American Express Savings Bank account online?

    You can access your account through American Express Savings Bank’s secure online banking portal. Simply visit their website and log in with your credentials.

  • Professional Liability Insurance Quotes for Small Businesses: A Guide to Coverage, Costs, and Comparison

    Professional Liability Insurance Quotes for Small Businesses: A Guide to Coverage, Costs, and Comparison

    Professional liability insurance quotes small business – Navigating the realm of professional liability insurance quotes for small businesses can be a daunting task, but it’s a crucial step in safeguarding your company’s reputation and financial well-being. Dive into this comprehensive guide to gain insights into the types of coverage available, factors influencing quotes, and strategies for obtaining the best possible rates.

    Understanding professional liability insurance is paramount for small businesses. It acts as a protective shield against claims alleging negligence, errors, or omissions in the services you provide. By investing in this coverage, you mitigate risks, enhance customer trust, and secure your business’s future.

    Coverage and Benefits

    Professional liability insurance quotes small business

    Professional liability insurance, also known as errors and omissions (E&O) insurance, protects small businesses from financial losses resulting from alleged or actual mistakes, errors, or omissions in the performance of their professional services. It provides coverage for claims of negligence, breach of contract, misrepresentation, and other professional liabilities.Having

    professional liability insurance offers numerous benefits for small businesses. It provides peace of mind, knowing that they are financially protected against costly lawsuits. It also enhances their credibility and reputation, demonstrating to clients that they take their professional responsibilities seriously.

    Furthermore, it can help attract and retain clients who are seeking businesses that prioritize professionalism and risk management.Common claims covered by professional liability insurance include:

    • Negligence in the performance of professional services
    • Errors or omissions in advice or recommendations
    • Breach of contract
    • Misrepresentation or misstatement of facts
    • Defamation or libel
    • Intellectual property infringement

    Factors Affecting Quotes

    Professional liability insurance quotes for small businesses are not one-size-fits-all. Several factors influence the cost of coverage, including:

    Business Size

    The larger the business, the higher the potential for claims. Therefore, larger businesses typically pay higher premiums.

    Industry

    Certain industries, such as healthcare and construction, pose higher risks for professional liability claims. As a result, businesses in these industries can expect to pay higher premiums.

    Claims History, Professional liability insurance quotes small business

    Businesses with a history of claims are considered higher risks and will likely pay higher premiums. Even a single claim can significantly increase the cost of coverage.

    Importance of Understanding Your Risk Profile

    Before getting quotes, it’s essential to understand your business’s risk profile. This includes identifying potential risks and taking steps to mitigate them. By understanding your risk profile, you can provide insurers with a clearer picture of your business and potentially secure lower premiums.

    Obtaining Quotes

    Professional liability insurance quotes small business

    Obtaining professional liability insurance quotes for small businesses is a crucial step in securing the right coverage for your business. Here’s a step-by-step guide to help you get started:
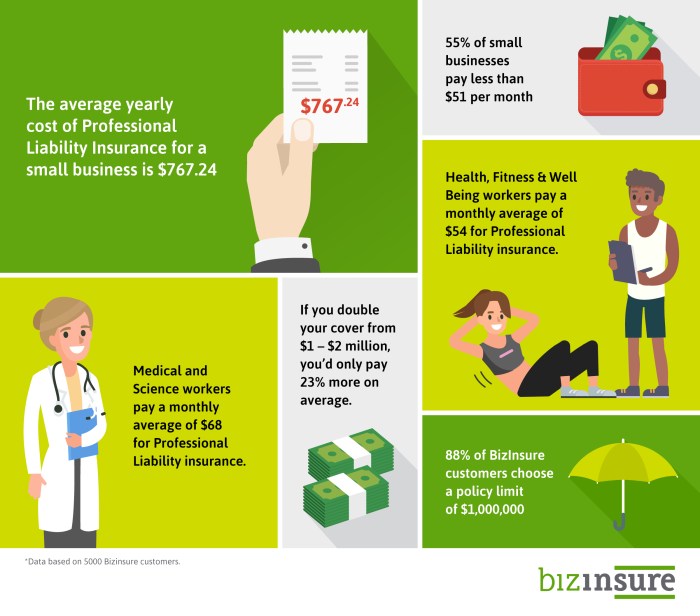
    There are several methods available for obtaining quotes, including online platforms and insurance brokers. Each method has its own advantages and disadvantages:

    Online Platforms

    • Convenience:Online platforms offer a quick and easy way to compare quotes from multiple insurers.
    • Limited Options:Online platforms may not offer quotes from all insurers, which could limit your options.
    • Less Personalization:Online platforms typically provide less personalized advice compared to insurance brokers.

    Insurance Brokers

    • Personalized Advice:Insurance brokers can provide personalized advice and help you understand the coverage options available.
    • Access to Multiple Insurers:Brokers have access to a wider range of insurers, which can increase your chances of finding the best coverage for your business.
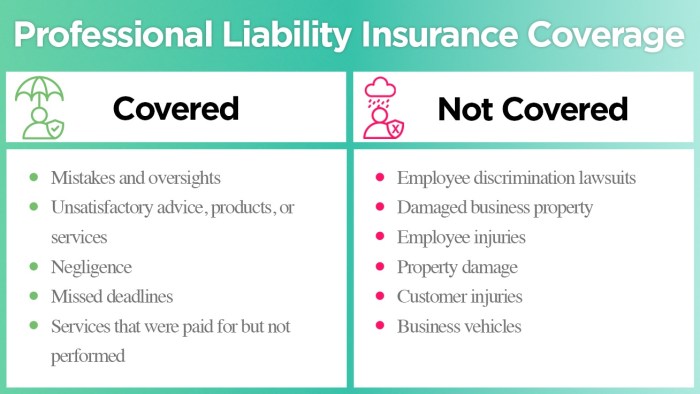
    • Higher Cost:Brokers may charge a fee for their services, which can increase the overall cost of your insurance.

    Once you have chosen a method for obtaining quotes, you can follow these steps to compare quotes and choose the best coverage for your business:

    Compare Coverage and Benefits

    Carefully review the coverage and benefits offered by each insurer. Make sure that the policy meets your specific needs and provides adequate protection for your business.

    Consider Premiums and Deductibles

    Premiums are the annual cost of your insurance, while deductibles are the amount you pay out of pocket before your insurance coverage kicks in. Consider your budget and risk tolerance when comparing premiums and deductibles.

    Check the Insurer’s Financial Stability

    It’s important to choose an insurer with a strong financial rating. This ensures that the insurer will be able to pay out claims in the event of a lawsuit.

    Read the Policy Carefully

    Before purchasing a policy, read the policy carefully to understand the terms and conditions. Make sure that you understand what is covered and what is not.

    Negotiating Premiums

    Negotiating professional liability insurance premiums is crucial for small businesses seeking optimal coverage without breaking the bank. Several strategies can enhance your bargaining position.

    Role of Deductibles, Limits of Liability, and Payment Plans

    Deductibles, limits of liability, and payment plans directly impact premiums. Higher deductibles lower premiums, while increased limits of liability lead to higher premiums. Flexible payment plans may offer discounts for upfront payments.

    Tips for Negotiating with Insurance Companies

    *

    -*Research and Compare Quotes

    Obtain quotes from multiple insurers to compare coverage and rates.

    • -*Provide Detailed Information

      Accurately disclose your business activities, claims history, and risk management measures.

    • -*Emphasize Risk Mitigation

      Highlight implemented risk management protocols to demonstrate your commitment to minimizing potential claims.

    • -*Negotiate Deductibles and Limits

      Discuss adjustments to deductibles and limits of liability to optimize coverage and premiums.

    • -*Explore Discounts and Credits

      Inquire about potential discounts for loyalty, multiple policies, or safety initiatives.

    Importance of Regular Reviews

    Liability pmcaonline

    Maintaining adequate professional liability insurance coverage is crucial for small businesses. Regular reviews ensure that your coverage remains aligned with evolving risks and business needs. Neglecting to review your policy can lead to gaps in coverage, leaving you exposed to financial and reputational risks.

    Checklist for Coverage Reviews

    • Review Coverage Limits:Assess if your coverage limits are sufficient to protect against potential claims. Consider the size of your business, the industry you operate in, and the nature of the services you provide.
    • Examine Exclusions:Identify any exclusions or limitations in your policy that may restrict coverage. Ensure you understand the specific circumstances under which your insurance will not provide protection.
    • Consider Additional Coverages:Explore additional coverage options that may be relevant to your business, such as cyber liability, errors and omissions, or directors and officers insurance.
    • Review Policy Terms:Carefully review the terms and conditions of your policy, including the deductible, reporting requirements, and defense costs.
    • Assess Financial Stability:Verify the financial stability of your insurance provider to ensure they have the resources to cover potential claims.

    Closing Summary

    In conclusion, obtaining professional liability insurance quotes for small businesses is an essential step towards protecting your enterprise. By carefully considering coverage options, understanding factors affecting premiums, and negotiating effectively, you can secure the optimal coverage at the most competitive rates.

    Regular reviews of your policy ensure that your business remains adequately protected as it evolves.

    User Queries: Professional Liability Insurance Quotes Small Business

    What are the common types of professional liability insurance coverage for small businesses?

    Professional liability insurance policies typically cover claims alleging errors, omissions, or negligence in the services provided by your business. These policies can be tailored to specific industries and professions, ensuring that your unique risks are addressed.

    How do I obtain professional liability insurance quotes for my small business?

    There are several ways to obtain quotes for professional liability insurance. You can contact insurance companies directly, use online platforms that compare quotes from multiple providers, or work with an insurance broker who can guide you through the process and negotiate on your behalf.

    What factors influence the cost of professional liability insurance for small businesses?

    The cost of professional liability insurance for small businesses is influenced by several factors, including the size of your business, your industry, your claims history, and your desired coverage limits. Understanding your risk profile and tailoring your policy accordingly can help you secure the best possible rates.

  • Capital One Hysa: An Expansive Guide to High-Yield Savings

    Capital One Hysa: An Expansive Guide to High-Yield Savings

    Capital One Hysa invites you on an enriching journey, revealing the intricacies of high-yield savings with vivid clarity and captivating detail. Embark on this exploration to unlock the secrets of financial growth and discover how Capital One Hysa empowers you to save more, earn more, and achieve your financial aspirations.

    Unravel the exceptional features of Capital One Hysa, meticulously compared to its peers in an illuminating table. Delve into the tangible benefits that await you, empowering you to make informed decisions and maximize your savings potential.

    Capital One Hysa Features

    Gobankingrates comerica bonuses coupons debit credit referral fnbo

    Capital One Hysa offers a range of features that make it a compelling option for savers looking to grow their money.

    One of the standout features of Capital One Hysa is its competitive interest rate. The account currently offers an APY of 3.30%, which is among the highest rates available for high-yield savings accounts. This means that your money can grow faster with Capital One Hysa than with many other savings accounts.

    Another key feature of Capital One Hysa is its lack of monthly maintenance fees. This means that you can keep your money in the account without having to worry about paying any fees, which can eat into your savings over time.

    Capital One Hysa also offers a variety of other features that can make it a convenient and user-friendly option for savers. These features include:

    • Online and mobile banking: You can access your account online or through the Capital One mobile app, making it easy to manage your money from anywhere.
    • Automatic deposits: You can set up automatic deposits from your checking account to your Hysa, making it easy to save money on a regular basis.
    • Customer support: Capital One offers 24/7 customer support, so you can get help with your account whenever you need it.

    Comparison of Capital One Hysa to Other High-Yield Savings Accounts

    The following table compares the features of Capital One Hysa to those of other popular high-yield savings accounts:

    Feature Capital One Hysa Ally Online Savings Account Marcus by Goldman Sachs High Yield Online Savings
    APY 3.30% 3.30% 3.30%
    Monthly maintenance fee $0 $0 $0
    Online and mobile banking Yes Yes Yes
    Automatic deposits Yes Yes Yes
    Customer support 24/7 24/7 24/7

    As you can see, Capital One Hysa compares favorably to other popular high-yield savings accounts in terms of its features and benefits.

    Capital One Hysa Benefits

    Capital one hysa

    Capital One Hysa offers several benefits to its customers, making it a valuable option for those looking to save money and earn interest.

    One of the primary benefits of Capital One Hysa is its competitive interest rates. The high-yield savings account consistently offers one of the highest interest rates in the market, allowing customers to maximize their earnings. The interest is compounded daily, which means that customers earn interest on their interest, leading to even greater returns over time.

    Flexibility and Convenience

    Capital One Hysa provides flexibility and convenience to its customers. There are no minimum balance requirements, so customers can open an account with any amount of money. Additionally, there are no monthly maintenance fees, making it a low-cost option for saving.

    Customers can access their accounts online, through the mobile app, or by phone, making it easy to manage their finances on the go.

    FDIC Insurance, Capital one hysa

    Capital One Hysa is FDIC-insured up to $250,000, providing peace of mind to customers. This means that their deposits are protected in the event of a bank failure, ensuring the safety of their savings.

    Capital One Hysa Requirements

    To open a Capital One Hysa, there are a few basic requirements that you need to meet.

    The first requirement is that you must be a US citizen or resident alien. You must also be at least 18 years of age.

    Minimum Deposit and Balance Requirements

    The minimum deposit to open a Capital One Hysa is $10. Once your account is open, you must maintain a minimum balance of $10.

    Capital One Hysa Fees

    Capital One Hysa offers a competitive interest rate with no monthly maintenance fees. However, there are a few potential fees to be aware of:

    The following table summarizes the fees associated with Capital One Hysa:

    Fee Amount
    Monthly maintenance fee $0
    Early withdrawal penalty Up to 3 months of interest
    Excessive withdrawal penalty Up to $10 per withdrawal after 6 withdrawals per month

    Early Withdrawal Penalty

    If you withdraw funds from your Capital One Hysa before the maturity date, you may be subject to an early withdrawal penalty. The penalty is equal to up to 3 months of interest earned on the withdrawn funds.

    Excessive Withdrawal Penalty

    Capital One Hysa allows up to 6 withdrawals per month without penalty. However, if you make more than 6 withdrawals in a month, you may be subject to an excessive withdrawal penalty of up to $10 per withdrawal.

    Capital One Hysa Alternatives

    Capital One Hysa is a competitive option in the market, but there are other high-yield savings accounts that may suit your specific needs.

    When comparing Capital One Hysa to other financial institutions, consider factors such as interest rates, minimum balance requirements, and fees.

    Interest Rates

    • Capital One Hysa offers a competitive interest rate, but other institutions may offer higher rates.
    • Compare interest rates from multiple institutions to find the highest yield for your savings.

    Minimum Balance Requirements

    • Capital One Hysa has a low minimum balance requirement, but some institutions may offer accounts with no minimum balance.
    • Consider your savings habits and choose an account that aligns with your financial situation.

    Fees

    • Capital One Hysa has no monthly maintenance fees, but other institutions may charge fees for certain transactions or services.
    • Review the fee schedule of each institution to avoid any unexpected charges.

    Final Thoughts: Capital One Hysa

    Capital one hysa

    As you reach the pinnacle of this enlightening discourse, you will emerge with a profound understanding of Capital One Hysa. Its requirements, fees, and alternatives have been laid bare, equipping you with the knowledge to make discerning choices and navigate the world of high-yield savings with confidence.

    Remember, Capital One Hysa stands as a beacon of financial empowerment, guiding you toward a brighter financial future. Embrace its transformative power and unlock the gateway to financial success.

    Query Resolution

    What sets Capital One Hysa apart from other high-yield savings accounts?

    Capital One Hysa distinguishes itself through its competitive interest rates, user-friendly platform, and commitment to customer satisfaction. Its tailored features cater to a wide range of financial needs, making it an exceptional choice for those seeking to maximize their savings.

    Are there any fees associated with Capital One Hysa?

    Capital One Hysa offers a straightforward fee structure with no monthly maintenance fees or minimum balance requirements. However, there is a one-time $10 closing fee if the account is closed within 180 days of opening.

    How do I open a Capital One Hysa?

    Opening a Capital One Hysa is a seamless process. You can apply online, through the Capital One mobile app, or by visiting a local branch. The minimum opening deposit is $0, making it accessible to individuals at all financial stages.