Blog

  • Workmans Comp for Small Businesses: A Comprehensive Guide to Understanding and Managing Workplace Risks

    Workmans Comp for Small Businesses: A Comprehensive Guide to Understanding and Managing Workplace Risks

    Workmans comp for small business – Navigating the intricacies of workers’ compensation for small businesses can be a daunting task. Understanding the legal requirements, choosing the right insurance, managing claims, and preventing accidents are crucial aspects that every small business owner must address to ensure a safe and compliant work environment.

    This comprehensive guide delves into the essential elements of workers’ compensation, empowering small businesses with the knowledge and strategies to protect their employees and safeguard their operations.

    As a small business owner, it’s imperative to recognize the significance of workers’ compensation insurance. Not only does it provide financial protection for employees who suffer work-related injuries or illnesses, but it also shields businesses from potential legal liabilities. Understanding the coverage, eligibility criteria, and reporting procedures is paramount to ensuring compliance and mitigating risks.

    Understanding Workers’ Compensation for Small Businesses

    Workmans comp for small business

    Workers’ compensation insurance is a vital protection for small businesses and their employees. It provides financial support and medical care to workers who suffer job-related injuries or illnesses, ensuring their well-being and protecting the business from potential liabilities.

    Types of Injuries and Illnesses Covered

    Workers’ compensation covers a wide range of injuries and illnesses sustained during the course of employment, including:

    • Physical injuries, such as fractures, sprains, cuts, and burns
    • Occupational diseases, such as repetitive stress injuries, hearing loss, and respiratory problems
    • Mental health conditions, such as post-traumatic stress disorder and depression caused by workplace events

    Common Workplace Accidents

    Workers’ compensation claims often arise from common workplace accidents, such as:

    • Slips, trips, and falls
    • Lifting injuries
    • Vehicle accidents
    • Machinery-related accidents
    • Exposure to hazardous substances

    Legal Requirements and Responsibilities

    Workmans comp for small business

    Workers’ compensation laws vary from state to state, and employers must be aware of the specific requirements in their jurisdiction. In most states, employers with a certain number of employees are required to carry workers’ compensation insurance. Failure to comply with these laws can result in significant penalties, including fines, imprisonment, and civil liability.

    Employer Responsibilities

    Employers have a legal obligation to provide a safe work environment for their employees and to ensure that they have access to workers’ compensation benefits if they are injured or become ill on the job. This includes:

    • Providing a safe workplace
    • Maintaining accurate records of work-related injuries and illnesses
    • Reporting work-related injuries and illnesses to the appropriate authorities
    • Providing employees with information about their rights and responsibilities under the workers’ compensation system

    Employee Responsibilities

    Employees also have responsibilities under the workers’ compensation system. These include:

    • Reporting work-related injuries and illnesses to their employer
    • Cooperating with the employer and the workers’ compensation insurer during the investigation and claims process
    • Following the doctor’s orders and attending all scheduled appointments
    • Returning to work as soon as they are medically able

    Choosing the Right Workers’ Compensation Insurance

    Selecting the appropriate workers’ compensation insurance provider is crucial for small businesses. Here are some key factors to consider when making this decision:

    It’s essential to assess the financial stability and reputation of potential providers. Consider their claims-paying history, underwriting practices, and industry ratings. A financially sound and reputable insurer will provide peace of mind and ensure that your business is protected in the event of a claim.

    Types of Workers’ Compensation Insurance Policies

    Various types of workers’ compensation insurance policies are available, each tailored to specific business needs. Some common types include:

    • Standard Workers’ Compensation Policy:This policy provides coverage for employees who are injured or become ill due to work-related activities.
    • Employer’s Liability Insurance:This policy covers the employer’s legal liability for injuries or illnesses sustained by employees.
    • Occupational Accident Insurance:This policy provides coverage for employees who are injured or become ill due to accidents that occur on the job.

    Understanding the different types of policies and their coverage limits will help you select the one that best meets your business’s specific requirements.

    Tailoring the Policy to Your Needs

    Customizing your workers’ compensation insurance policy to align with your business’s unique needs is essential. Consider factors such as the number of employees, industry, and potential risks. A tailored policy will ensure that you have adequate coverage without paying for unnecessary benefits.

    Managing Workers’ Compensation Claims

    Managing workers’ compensation claims involves a comprehensive process that ensures timely and appropriate support for injured employees while safeguarding the interests of employers. The steps involved in filing a claim, the role of the insurance company, and best practices for efficient claim management are crucial aspects to consider.

    Steps Involved in Filing a Workers’ Compensation Claim

    When an employee sustains a work-related injury or illness, they must report the incident to their supervisor promptly. The employer is responsible for providing the employee with a claim form and assisting them in completing it. The employee should provide detailed information about the injury, the date and time of the incident, and any witnesses present.

    The completed claim form is then submitted to the employer’s workers’ compensation insurance carrier.

    Role of the Insurance Company

    The insurance company plays a vital role in investigating and adjudicating workers’ compensation claims. Upon receiving the claim form, the insurance company will assign a claims adjuster to the case. The claims adjuster will review the claim, gather additional information if necessary, and determine if the claim is compensable under the policy.

    The insurance company will also provide the employee with medical treatment and other benefits as authorized by the policy.

    Best Practices for Managing Workers’ Compensation Claims

    To manage workers’ compensation claims efficiently and effectively, employers should follow certain best practices. These include:

    • Early reporting:Encouraging employees to report injuries promptly ensures timely medical attention and reduces the risk of complications.
    • Thorough documentation:Maintaining accurate records of all aspects of the claim, including medical reports, witness statements, and correspondence, is crucial for efficient processing.
    • Open communication:Maintaining open communication with the injured employee, the insurance company, and medical providers facilitates a collaborative approach to claim management.
    • Return-to-work programs:Implementing return-to-work programs helps injured employees return to work as soon as possible, reducing lost productivity and promoting their recovery.

    Preventing Workplace Accidents and Injuries

    Compensation workmans hartford workman assigns classification council

    Maintaining a secure and salubrious work environment is paramount to prevent workplace accidents and injuries. This entails implementing comprehensive strategies that encompass safety training, hazard identification, and ergonomic principles.

    Safety Training, Workmans comp for small business

    Comprehensive safety training programs are indispensable for equipping employees with the knowledge and skills necessary to identify and mitigate potential hazards. Training should encompass topics such as proper equipment operation, emergency procedures, and workplace-specific safety protocols.

    Hazard Identification

    Regularly conducting hazard assessments is crucial for proactively identifying potential risks within the workplace. These assessments should involve a thorough inspection of the work environment, identifying hazards such as slippery surfaces, unguarded machinery, or inadequate lighting.

    Ergonomics

    Implementing ergonomic principles in the workplace can significantly reduce the risk of musculoskeletal disorders, which are common injuries resulting from repetitive or awkward movements. Ergonomic interventions include optimizing workstations, providing proper seating, and encouraging regular breaks to prevent strain and fatigue.

    Ultimate Conclusion

    In conclusion, workers’ compensation for small businesses is a multifaceted subject that requires careful consideration and proactive management. By adhering to legal obligations, selecting appropriate insurance coverage, implementing effective risk management strategies, and fostering a culture of safety, small businesses can create a secure and supportive work environment for their employees while safeguarding their own interests.

    Embracing these principles will not only enhance workplace well-being but also contribute to the overall success and sustainability of the business.

    Clarifying Questions: Workmans Comp For Small Business

    What are the key benefits of workers’ compensation insurance for small businesses?

    Workers’ compensation insurance offers several advantages for small businesses, including financial protection against employee injury or illness-related expenses, reduced legal liability, improved employee morale, and enhanced business reputation.

    What types of injuries and illnesses are typically covered by workers’ compensation?

    Workers’ compensation insurance generally covers injuries or illnesses that arise out of and in the course of employment, including accidents, occupational diseases, repetitive motion injuries, and mental health conditions caused by work-related stress.

    What are the common workplace accidents that may lead to workers’ compensation claims?

    Common workplace accidents that can result in workers’ compensation claims include slips, trips, and falls; machinery-related injuries; exposure to hazardous substances; repetitive motion injuries; and motor vehicle accidents.

  • Workers Comp for Small Business: Essential Coverage for Workplace Protection

    Workers Comp for Small Business: Essential Coverage for Workplace Protection

    Workers comp for small business – Navigating the complexities of workers’ compensation for small businesses can be a daunting task. This comprehensive guide will illuminate the purpose, benefits, and legal obligations associated with this crucial insurance, empowering you to protect your employees and safeguard your business.

    Understanding the ins and outs of workers’ comp is paramount for small businesses seeking to ensure a safe and compliant workplace. By delving into the intricacies of coverage, premium calculations, and risk management strategies, you can optimize your coverage and minimize costs.

    Understanding Workers’ Compensation for Small Businesses

    Workers’ compensation insurance is a crucial protection for small businesses, safeguarding both employers and employees in the event of workplace injuries or illnesses. It provides financial support for medical expenses, lost wages, and other related costs, ensuring that injured workers receive the necessary care and compensation while protecting businesses from potential legal liabilities.

    Covered Incidents

    Workers’ compensation coverage typically extends to injuries or illnesses that arise directly from the course and scope of employment. This includes accidents, occupational diseases, and repetitive stress injuries. Common examples include:

    • Slips, trips, and falls
    • Exposure to hazardous substances
    • Repetitive motions leading to carpal tunnel syndrome
    • Occupational lung diseases, such as silicosis

    Excluded Incidents

    However, certain incidents are not covered by workers’ compensation, such as:

    • Injuries or illnesses caused by intoxication or willful misconduct
    • Self-inflicted injuries
    • Injuries sustained outside the workplace or during non-work activities
    • Intentional acts of violence

    Legal Obligations and Penalties

    In most jurisdictions, it is a legal requirement for businesses to carry workers’ compensation insurance. Failure to comply can result in significant penalties, including fines, imprisonment, and civil lawsuits from injured employees.

    Determining Coverage and Premium Costs

    Workers comp for small business

    Understanding the nuances of workers’ compensation coverage and premium calculations is essential for small businesses. Let’s explore how to determine employee eligibility, factors that influence premium costs, and strategies for optimizing coverage while minimizing expenses.

    Employee Eligibility

    In most jurisdictions, employees who work a minimum number of hours or earn a specific income threshold are eligible for workers’ compensation coverage. This includes part-time, temporary, and seasonal workers. It’s important to note that independent contractors are generally not eligible for workers’ compensation benefits.

    Premium Calculations

    Premium costs for workers’ compensation insurance are influenced by several factors, including:

    • -*Industry

      Businesses in high-risk industries, such as construction or manufacturing, typically have higher premiums due to the increased likelihood of workplace accidents.

    • -*Payroll

      The total amount of wages paid to employees is a significant factor in premium calculations. Higher payrolls result in higher premiums.

    • -*Claims History

      Businesses with a history of frequent or costly claims will have higher premiums, as insurers factor in the potential for future claims.

    Optimizing Coverage and Minimizing Costs

    To optimize coverage and minimize costs, consider the following strategies:

    • -*Proper Classification

      Ensure that your business is classified accurately based on its industry and operations. Misclassification can lead to incorrect premium calculations.

    • -*Safety Programs

      Implementing comprehensive safety programs can help reduce the risk of accidents and subsequent claims, potentially lowering premiums.

    • -*Claims Management

      Promptly reporting and managing claims effectively can help mitigate costs and prevent disputes.

    • -*Negotiating Premiums

      Work with your insurance provider to negotiate competitive premium rates. Consider shopping around for quotes from multiple insurers.

    Managing Claims and Reducing Risk

    Workers comp compensation business small insurance collar does need loss medical worker state blue employees accounting services

    Managing workers’ compensation claims and reducing workplace accidents are crucial for small businesses. This guide will provide a step-by-step process for reporting and handling claims, along with best practices for preventing injuries and creating a safe work environment.

    Reporting and Managing Workers’ Compensation Claims

    Follow these steps to effectively manage workers’ compensation claims:

    1. Report the injury promptly:Inform your insurance carrier and the injured employee’s supervisor immediately after an accident or injury occurs.
    2. Document the incident:Gather details about the injury, including the date, time, location, witnesses, and a description of what happened.
    3. Provide medical attention:Ensure the injured employee receives appropriate medical care and follow-up treatment.
    4. Investigate the incident:Determine the cause of the accident or injury and implement measures to prevent similar incidents in the future.
    5. Manage communication:Keep the injured employee, their supervisor, and the insurance carrier informed about the claim status and any updates.

    Preventing Workplace Accidents and Injuries

    Implement these best practices to minimize the risk of workplace accidents and injuries:

    • Conduct regular safety inspections:Identify potential hazards and take steps to eliminate or mitigate them.
    • Provide safety training:Educate employees on safe work practices and emergency procedures.
    • Use appropriate safety equipment:Ensure employees have and use personal protective equipment (PPE) such as helmets, gloves, and safety glasses.
    • Encourage employee involvement:Create a safety committee or involve employees in developing and implementing safety measures.
    • Maintain a clean and organized work environment:Clutter and debris can contribute to accidents.

    Creating a Safe and Healthy Work Environment

    Beyond preventing accidents, a safe and healthy work environment promotes employee well-being and productivity:

    • Provide adequate lighting and ventilation:Ensure the workplace is well-lit and has good air quality.
    • Control noise levels:Excessive noise can lead to hearing loss and other health issues.
    • Promote ergonomic workstations:Design workstations to minimize strain and discomfort.
    • Offer wellness programs:Encourage healthy habits and provide access to resources that support employee well-being.
    • Maintain open communication:Encourage employees to report any safety concerns or suggestions for improvement.

    Working with Insurance Providers

    Selecting the right workers’ compensation insurance provider is crucial for protecting your business and employees. Different types of insurance providers offer varying levels of coverage, services, and expertise.

    Evaluating and Selecting an Insurance Company

    • Assess financial stability:Check the insurer’s financial ratings from reputable agencies like AM Best or Standard & Poor’s to ensure they have the resources to cover claims.
    • Review coverage options:Compare the types of coverage offered by different providers to determine which best suits your business needs.
    • Consider experience and reputation:Look for an insurer with a proven track record of providing workers’ compensation insurance and handling claims effectively.
    • Get quotes from multiple providers:Compare premium costs and coverage details to find the most competitive and comprehensive option.
    • Consult with an insurance broker:A broker can help you navigate the insurance market, evaluate providers, and negotiate the best terms for your business.

    Maintaining Open Communication and Building a Strong Relationship

    Once you have selected an insurance provider, it’s essential to maintain open communication and foster a strong relationship.

    • Establish clear communication channels:Designate specific individuals within your business and the insurance company as primary contacts for communication.
    • Schedule regular meetings:Meet with your insurer periodically to review coverage, discuss claims, and identify areas for improvement.
    • Provide timely updates:Inform your insurer promptly about any changes in your business operations, employee count, or claims status.
    • Foster trust and collaboration:Build a relationship based on mutual respect, trust, and a shared goal of protecting your business and employees.

    Legal Considerations and Compliance

    Navigating workers’ compensation laws can be a complex task for small businesses. Understanding your legal responsibilities and adhering to state and federal regulations is crucial to ensure compliance and minimize risk.

    At the core of workers’ compensation laws is the principle that employers are liable for injuries sustained by their employees during the course of their employment. This liability extends to both physical injuries and occupational diseases. By providing workers’ compensation insurance, businesses fulfill their legal obligation to provide financial support to injured workers, regardless of fault.

    State and Federal Regulations

    Workers’ compensation laws vary from state to state, with each jurisdiction having its own specific requirements and regulations. It is essential for businesses to be familiar with the laws applicable in their state to ensure compliance.

    In addition to state laws, federal regulations also play a role in workers’ compensation. The Occupational Safety and Health Act (OSHA) sets minimum standards for workplace safety and health, while the Americans with Disabilities Act (ADA) prohibits discrimination against employees with disabilities, including those who have suffered work-related injuries.

    Recordkeeping and Reporting Requirements, Workers comp for small business

    Businesses are required to maintain accurate records of all work-related injuries and illnesses. These records should include details such as the date and time of the incident, the nature of the injury or illness, and the employee’s job duties.

    In most states, businesses are also required to report work-related injuries and illnesses to the state workers’ compensation agency. The specific reporting requirements vary by state, but typically include providing information about the injured employee, the employer, and the incident.

    Conclusive Thoughts

    Workers comp for small business

    Workers’ compensation for small businesses is not merely a legal requirement but a fundamental investment in employee well-being and business sustainability. By embracing a proactive approach to coverage, claims management, and risk reduction, you can foster a thriving and protected work environment that benefits both your employees and your bottom line.

    FAQ Corner: Workers Comp For Small Business

    What are the key benefits of workers’ compensation insurance?

    Workers’ compensation provides coverage for medical expenses, lost wages, and disability benefits in the event of a work-related injury or illness, protecting both employees and employers.

    How can small businesses determine their coverage needs?

    Factors such as industry, payroll, and claims history influence premium calculations. By assessing these variables, small businesses can tailor their coverage to meet their specific requirements.

    What are the best practices for preventing workplace accidents and injuries?

    Implementing safety protocols, providing proper training, and maintaining a clean and organized work environment are crucial for minimizing risks and fostering a safe workplace.

  • Bank Accounts with No Opening Deposit: A Financial Lifeline for All

    Bank Accounts with No Opening Deposit: A Financial Lifeline for All

    Bank accounts with no opening deposit are financial lifelines, offering access to essential banking services without the barrier of an initial deposit. These accounts empower individuals with limited funds to manage their finances, build savings, and participate in the formal financial system.

    From traditional banks to online fintech platforms, various institutions offer bank accounts with no opening deposit. These accounts cater to diverse needs, from basic checking and savings accounts to specialized accounts designed for specific purposes.

    Benefits of Bank Accounts with No Opening Deposit

    Bank accounts with no opening deposit

    Opening a bank account without an initial deposit offers numerous advantages, especially for individuals with limited funds or those who are just starting out. These accounts provide access to essential banking services without the barrier of a minimum deposit requirement.

    One of the primary benefits of bank accounts with no opening deposit is the increased accessibility to banking services. For individuals who may not have the means to make a substantial initial deposit, these accounts offer a gateway to managing their finances more effectively.

    They can deposit their earnings, pay bills, and access other essential banking services, promoting financial inclusion.

    Examples of Banks Offering No Opening Deposit Accounts, Bank accounts with no opening deposit

    • Chime:Chime offers a no-fee checking account with no minimum balance requirement, making it accessible to individuals with limited funds.
    • Axos Bank:Axos Bank’s Essential Checking account has no monthly maintenance fees or minimum balance requirements, providing a convenient option for those who want to avoid additional charges.
    • Ally Bank:Ally Bank’s Online Savings Account requires no minimum deposit to open and offers competitive interest rates, allowing individuals to start saving without any upfront investment.

    Types of Bank Accounts with No Opening Deposit

    Bank accounts with no opening deposit

    Bank accounts with no opening deposit offer convenience and accessibility to individuals who may not have the initial funds to open a traditional account. These accounts come in various types, each with its own set of features, benefits, and eligibility criteria.

    Checking Accounts

    • Basic Checking Accounts:Designed for everyday banking needs, these accounts offer features such as check writing, debit card access, and online banking. Eligibility typically requires proof of identity and a valid address.
    • Interest-Bearing Checking Accounts:Similar to basic checking accounts, these accounts earn interest on the balance, providing a potential way to grow savings over time. Eligibility may require a higher minimum balance.

    Savings Accounts

    • Passbook Savings Accounts:Traditional savings accounts that use a passbook to record transactions. They offer a safe and secure way to save money, with eligibility often requiring only a valid ID.
    • Online Savings Accounts:Convenient and accessible, these accounts are managed online and offer competitive interest rates. Eligibility may require a valid email address and a linked checking account.

    Money Market Accounts

    • Money Market Deposit Accounts (MMDAs):High-yield savings accounts that offer check-writing privileges. They may require a higher minimum balance to open and may have transaction limits.
    • Money Market Savings Accounts (MMSAs):Similar to MMDAs, these accounts offer check-writing privileges but may have lower interest rates and higher minimum balance requirements.

    Fees and Charges Associated with Bank Accounts with No Opening Deposit

    Bank accounts with no opening deposit may have associated fees or charges that can impact account holders. These fees can vary depending on the financial institution and the type of account.

    Account Maintenance Fees

    Account maintenance fees are monthly or annual charges for maintaining an account. These fees can range from a few dollars to tens of dollars per month. If an account holder does not maintain a minimum balance or meet certain activity requirements, they may be charged an account maintenance fee.

    Using Bank Accounts with No Opening Deposit

    Opening and using bank accounts with no opening deposit is a convenient and accessible way to manage your finances. Here’s a step-by-step guide to help you get started:

    Step 1: Choose a Bank and Account Type

    Research different banks that offer no-opening-deposit accounts and compare their terms, conditions, and fees. Select an account type that aligns with your financial needs, such as a checking account for everyday transactions or a savings account for long-term savings.

    Step 2: Submit an Application

    Complete the bank’s account opening application online or in person. Provide your personal information, contact details, and proof of identity (e.g., driver’s license, passport).

    Step 3: Verify Your Identity

    The bank may require you to verify your identity through additional documents or a video call. This step ensures the security and compliance of your account.

    Step 4: Activate Your Account

    Once your identity is verified, the bank will activate your account. You may receive a debit card or online banking credentials to access your account.

    Step 5: Manage Your Account

    Use your account for everyday transactions, such as depositing checks, making withdrawals, and paying bills. Monitor your account balance and transactions regularly to ensure proper management.

    Limitations and Restrictions

    While bank accounts with no opening deposit offer convenience, they may have certain limitations and restrictions:

    • Limited Features:These accounts may not offer all the features of traditional bank accounts, such as overdraft protection or check writing.
    • Monthly Maintenance Fees:Some no-opening-deposit accounts charge monthly maintenance fees to keep the account active.
    • Transaction Limits:There may be limits on the number of transactions you can make per month or the amount of money you can withdraw.
    • Minimum Balance Requirements:Some accounts require you to maintain a minimum balance to avoid fees or penalties.
    • Eligibility Criteria:Banks may have eligibility criteria for opening no-opening-deposit accounts, such as proof of income or a good credit history.

    Comparison of Bank Accounts with No Opening Deposit

    Choosing a bank account with no opening deposit can be daunting, given the various options available. To simplify the process, we have compiled a table comparing different bank accounts based on their features, fees, and eligibility criteria. This comprehensive comparison will help you identify the account that best aligns with your financial needs.

    Features

    Bank accounts with no opening deposit typically offer a range of features to cater to different banking requirements. Some common features include:

    • Online and mobile banking
    • Debit card or ATM card
    • Direct deposit
    • Bill pay
    • Check writing (in some cases)

    Fees

    While bank accounts with no opening deposit may not require an initial deposit, they may charge various fees, including:

    • Monthly maintenance fees
    • Transaction fees
    • Overdraft fees
    • ATM withdrawal fees

    Eligibility Criteria

    Eligibility criteria for bank accounts with no opening deposit can vary depending on the bank and the specific account type. Some common eligibility requirements include:

    • Minimum age requirement (usually 18 years)
    • Valid government-issued ID
    • Proof of address
    • Social Security number or Taxpayer Identification Number

    By carefully comparing the features, fees, and eligibility criteria of different bank accounts with no opening deposit, you can make an informed decision that meets your specific banking needs.

    Final Thoughts

    Account checking opening deposit current open cbz

    Bank accounts with no opening deposit are a game-changer for financial inclusion, providing a gateway to financial stability and empowerment. They offer a lifeline to individuals who have traditionally been excluded from the formal banking system, fostering financial literacy and economic growth.

    Essential FAQs

    Can I open a bank account with no opening deposit if I have bad credit?

    Yes, some banks offer bank accounts with no opening deposit and no credit checks. These accounts are designed to provide access to banking services for individuals with limited credit history or poor credit.

    What are the fees associated with bank accounts with no opening deposit?

    Fees vary depending on the bank and the type of account. Some accounts may have monthly maintenance fees, transaction fees, or minimum balance requirements. It’s important to compare fees before choosing an account.

    Can I use a bank account with no opening deposit to receive government benefits?

    Yes, many banks allow you to receive government benefits, such as Social Security or unemployment benefits, into a bank account with no opening deposit. This can provide a safe and convenient way to manage your finances.

  • Veteran Emergency Financial Assistance: A Lifeline in Times of Crisis

    Veteran Emergency Financial Assistance: A Lifeline in Times of Crisis

    When life throws unexpected financial challenges at veterans, veteran emergency financial assistance serves as a lifeline, providing much-needed support during their most trying times. This comprehensive guide explores the various programs, eligibility requirements, and application processes available to veterans seeking emergency financial assistance, empowering them to navigate these challenges with dignity and resilience.

    Financial Assistance Programs for Veterans

    Veterans facing financial emergencies can access a range of government and non-profit programs designed to provide temporary assistance. These programs offer various benefits, from one-time grants to ongoing support, to help veterans navigate financial challenges and maintain stability.

    Government Programs

    The Department of Veterans Affairs (VA) offers several financial assistance programs specifically tailored to veterans in need:

    Program Eligibility Benefits Application
    Emergency Financial Aid Veterans with financial emergencies due to sudden events One-time grant up to $1,500 Apply through local VA medical centers
    Supplemental Pension Low-income veterans with limited assets Monthly pension payments to supplement other income Apply through VA regional offices
    VA Health Care for the Homeless Program Homeless or at-risk veterans Medical, dental, and mental health care; housing assistance Apply through local VA medical centers

    Non-Profit Programs

    Numerous non-profit organizations also provide financial assistance to veterans. These programs may offer grants, loans, or other forms of support:

    • American Red Cross:Provides emergency financial assistance to veterans affected by disasters or other emergencies.
    • Salvation Army:Offers financial assistance, housing, and other support services to veterans in need.
    • United Way:Provides financial assistance and other support services to veterans through its network of local affiliates.

    Eligibility and Application Process

    Assistance financial dependent veterans

    Veterans in need of immediate financial assistance may qualify for emergency aid from various organizations. Eligibility requirements and application processes vary depending on the program and provider. However, there are some general guidelines that apply to most programs.

    Eligibility Requirements

    To be eligible for emergency financial assistance, veterans typically must meet the following requirements:

    • Discharge Status:Veterans must have been honorably discharged from active duty.
    • Income Limits:Veterans must demonstrate financial need, typically by meeting specific income limits.
    • Proof of Need:Veterans must provide documentation to support their financial need, such as bills, rent statements, or medical expenses.

    Application Process

    To apply for emergency financial assistance, veterans can follow these steps:

    1. Contact a Service Organization:Veterans can contact a local veterans service organization, such as the American Legion or Veterans of Foreign Wars, to inquire about assistance programs.
    2. Gather Required Documents:Veterans will need to gather documentation to support their application, such as a DD Form 214 (Certificate of Release or Discharge from Active Duty), proof of income, and proof of need.
    3. Submit Application:Veterans can submit their application in person, by mail, or online, depending on the program and provider.
    4. Review and Approval:Applications will be reviewed by the organization or provider, and veterans will be notified of the approval or denial of their request.

    Types of Emergency Financial Assistance

    Veterans facing financial emergencies have access to various types of assistance designed to provide temporary relief and support. These programs offer grants, loans, and housing assistance tailored to specific needs.

    The funds can be utilized for essential expenses such as rent or mortgage payments, medical bills, transportation costs, or other urgent needs that arise during challenging times.

    Grants

    Grants are non-repayable funds awarded to veterans who meet specific eligibility criteria. They provide immediate financial relief for pressing expenses, including:

    • Housing costs (rent or mortgage payments)
    • Medical expenses (co-pays, deductibles, prescriptions)
    • Transportation costs (car repairs, public transportation fares)
    • Utilities (electricity, gas, water bills)

    Loans

    Loans are financial assistance that must be repaid over time. They offer veterans a way to access larger sums of money for significant expenses, such as:

    • Home repairs or modifications
    • Education or training expenses
    • Starting a business
    • Consolidating high-interest debts

    Housing Assistance

    Housing assistance programs provide veterans with access to affordable housing options or financial assistance to maintain their current housing. These programs include:

    • Rental assistance (subsidized rent payments)
    • Homeless prevention programs
    • Housing vouchers
    • Homeownership assistance (down payment assistance, mortgage counseling)

    Resources for Veterans in Financial Crisis

    Veterans facing financial hardship can access a range of organizations and resources that provide essential support. These services include financial counseling, debt management, and other assistance programs tailored to meet the unique needs of veterans.

    Financial Counseling and Debt Management Services

    National Foundation for Credit Counseling (NFCC)

    NFCC offers free and confidential credit counseling services to veterans, including budgeting assistance, debt management plans, and financial education.

    Military OneSource

    Military OneSource provides financial counseling and support services to active-duty service members, veterans, and their families.

    Veterans Benefits Administration (VBA)

    VBA offers financial counseling and debt management assistance to veterans with service-connected disabilities.

    Other Support Services, Veteran emergency financial assistance

    American Red Cross

    The American Red Cross provides emergency financial assistance, food, and shelter to veterans in need.

    Salvation Army

    The Salvation Army offers a range of support services to veterans, including food, clothing, shelter, and financial assistance.

    Veterans of Foreign Wars (VFW)

    VFW provides financial assistance, housing support, and other services to veterans and their families.

    Case Studies and Success Stories

    Veteran emergency financial assistance

    Veterans facing financial crises can find solace in the numerous emergency financial assistance programs available to them. These programs have positively impacted the lives of many veterans, helping them overcome financial hurdles and regain stability. Here are some real-life case studies that highlight the challenges veterans have faced, the assistance they received, and the positive outcomes achieved.

    Veteran Overcomes Housing Crisis with Emergency Financial Assistance

    John, a veteran who served in the Marine Corps for six years, found himself facing eviction after losing his job due to a disability. With no income and mounting bills, he was on the verge of losing his home. John reached out to a local veterans’ service organization, which connected him with an emergency financial assistance program.

    The program provided him with rental assistance, helping him avoid eviction and maintain stable housing. With his housing situation secured, John could focus on his recovery and job search, eventually securing a new job and regaining financial stability.

    Emergency Assistance Helps Veteran Avoid Medical Debt

    Sarah, a veteran who served in the Army for eight years, was struggling with overwhelming medical debt after a serious illness. The cost of her treatments had depleted her savings, and she was facing collection notices and the threat of wage garnishment.

    Sarah contacted a veterans’ benefits counselor, who informed her about an emergency financial assistance program that could help her with medical expenses. The program provided her with a grant that covered a significant portion of her medical debt, allowing her to breathe a sigh of relief and focus on her recovery without the burden of financial stress.

    Financial Assistance Program Provides Stability for Veteran and Family

    Mark, a veteran who served in the Navy for four years, was struggling to provide for his family after his wife lost her job. With only one income and expenses piling up, Mark was worried about how he would make ends meet.

    He sought help from a local veterans’ center, which referred him to an emergency financial assistance program. The program provided Mark with a temporary cash assistance grant, helping him cover essential expenses such as groceries, utilities, and transportation. This assistance gave Mark and his family the breathing room they needed to adjust to the unexpected financial setback and work towards a more stable future.

    Conclusive Thoughts

    Veteran emergency financial assistance

    Veteran emergency financial assistance is not merely a handout but an investment in the well-being of those who have served our nation. By providing timely and targeted support, these programs help veterans overcome financial obstacles, regain stability, and continue contributing to their communities.

    Their impact extends beyond individuals, strengthening families and fostering a sense of camaraderie among those who have shared the sacrifices of military service.

    FAQs: Veteran Emergency Financial Assistance

    What types of emergency financial assistance are available to veterans?

    Veterans can access various forms of emergency financial assistance, including grants, loans, housing assistance, medical expense assistance, and transportation assistance.

    How do I apply for veteran emergency financial assistance?

    The application process varies depending on the program and organization. Generally, veterans must provide proof of military service, income, and financial need.

    What are the eligibility criteria for veteran emergency financial assistance?

    Eligibility criteria may include discharge status, income limits, and proof of financial hardship. Some programs have additional requirements, such as a service-connected disability.

    Where can I find resources for veterans in financial crisis?

    Numerous organizations and resources provide financial counseling, debt management, and other support services to veterans in financial crisis. These include the Department of Veterans Affairs, the Veterans of Foreign Wars, and the American Legion.

  • Small Business Indemnity Insurance: A Lifeline for Entrepreneurs

    Small Business Indemnity Insurance: A Lifeline for Entrepreneurs

    Small business indemnity insurance stands as a guardian angel for entrepreneurs, safeguarding them against financial pitfalls and legal woes. It’s a safety net that provides peace of mind, allowing businesses to thrive amidst unforeseen circumstances.

    This insurance policy extends its protective shield over a wide spectrum of risks, including bodily injury, property damage, and financial losses. It empowers businesses to navigate the complexities of liability claims, ensuring they can continue their operations without facing financial ruin.

    Coverage Overview

    Small business indemnity insurance serves as a protective shield for your enterprise, safeguarding it against a spectrum of financial liabilities and risks. It encompasses coverage for bodily injuries sustained by individuals on your premises, damage to property belonging to others, and financial losses incurred due to negligence or errors.

    This insurance policy acts as a safety net, ensuring that your business remains financially stable even in the face of unforeseen events. It empowers you to focus on growing your venture without the burden of excessive financial concerns.

    Covered Risks

    • Bodily Injury:Coverage extends to injuries suffered by individuals on your business premises, regardless of whether they are customers, employees, or visitors.
    • Property Damage:This aspect covers damage caused to the property of others due to your business operations or negligence.
    • Financial Loss:The policy provides protection against financial losses arising from legal liability, such as claims for defamation or copyright infringement.

    Key Features and Benefits

    Small business indemnity insurance

    Small business indemnity insurance is designed to protect businesses from financial liability and legal costs arising from claims made against them. It offers a range of key features and benefits that can provide peace of mind and financial security.

    Indemnity insurance policies typically cover the following:

    Claims Coverage, Small business indemnity insurance

    • Bodily injury or property damage to third parties
    • Legal expenses, including court costs and attorney fees
    • Judgments and settlements awarded against the business

    These policies can also provide:

    Additional Coverage

    • Coverage for employee injuries, even if the business is not at fault
    • Protection against claims arising from products or services provided by the business
    • Coverage for claims made by contractors or subcontractors

    By obtaining small business indemnity insurance, businesses can safeguard their financial well-being and protect themselves from the potentially devastating consequences of lawsuits.

    Eligibility and Exclusions: Small Business Indemnity Insurance

    To qualify for small business indemnity insurance, businesses must meet certain eligibility criteria, including:

    • Being a legally registered business entity.
    • Operating within the policy’s defined business activities.
    • Having a proven track record of financial stability.

    Despite providing broad coverage, indemnity insurance policies typically exclude certain types of claims, such as:

    Common Exclusions

    • Intentional Acts:Damages or injuries caused by deliberate or malicious actions of the business or its employees.
    • Contractual Liabilities:Claims arising from breach of contracts or agreements.
    • Employee Injuries:Injuries sustained by employees while performing their job duties, which are typically covered by workers’ compensation insurance.
    • Property Damage:Physical damage to property owned or leased by the business.
    • Environmental Liability:Claims related to environmental damage or pollution caused by the business’s operations.

    Cost and Premiums

    The cost of small business indemnity insurance premiums is influenced by several factors, including the size of the business, the industry in which it operates, the number of employees, the coverage limits, and the deductible.

    Businesses can minimize their insurance costs by:

    Risk Management

    • Implementing strong risk management practices, such as regular safety inspections and employee training.
    • Maintaining a good claims history.
    • Working with an insurance broker to find the best coverage at the most competitive price.

    Claims Process and Dispute Resolution

    Small business indemnity insurance

    Filing a claim under a small business indemnity insurance policy typically involves the following steps:

    The policyholder must notify the insurer promptly after an incident occurs. This can usually be done by phone, email, or through the insurer’s online portal.

    The insurer will assign a claims adjuster to investigate the claim. The adjuster will gather evidence, interview witnesses, and determine the extent of the loss.

    Once the investigation is complete, the insurer will issue a settlement offer to the policyholder. The policyholder can accept or reject the offer.

    If the policyholder accepts the offer, the insurer will issue payment for the claim.

    If the policyholder rejects the offer, they can appeal the decision through the insurer’s internal dispute resolution process.

    Dispute Resolution

    If the policyholder is not satisfied with the insurer’s decision, they can appeal the decision through the insurer’s internal dispute resolution process.

    The internal dispute resolution process typically involves the following steps:

    1. The policyholder must submit a written appeal to the insurer.
    2. The insurer will review the appeal and make a decision.
    3. If the policyholder is still not satisfied with the decision, they can file a complaint with the state insurance commissioner.

    Concluding Remarks

    Business indemnity insurance

    In the ever-evolving business landscape, small business indemnity insurance emerges as a beacon of stability. It empowers entrepreneurs to take calculated risks, knowing that they have a financial cushion to fall back on. As businesses grow and expand, this insurance policy remains a steadfast companion, providing unwavering support and protection.

    FAQ Insights

    What types of businesses need small business indemnity insurance?

    Any small business that interacts with customers, clients, or the public can benefit from indemnity insurance. It’s particularly crucial for businesses that provide services or products that could potentially lead to bodily injury or property damage.

    How much does small business indemnity insurance cost?

    The cost of indemnity insurance varies depending on factors such as the size of the business, the industry, and the level of coverage required. It’s advisable to obtain quotes from multiple insurance providers to compare rates and find the most cost-effective option.

    What are the exclusions under a small business indemnity insurance policy?

    Common exclusions include intentional acts, criminal activities, and damage caused by pollution. It’s important to carefully review the policy to understand what is and isn’t covered.

  • Affordable Business Insurance: Protect Your Enterprise with Cost-Effective Coverage

    Affordable Business Insurance: Protect Your Enterprise with Cost-Effective Coverage

    In today’s competitive business landscape, safeguarding your enterprise with cheap business insurance is not just a wise move—it’s a necessity. By understanding the coverage options available, implementing cost-saving strategies, and comparing providers, you can secure the protection your business needs without breaking the bank.

    Tailoring your coverage to your unique business requirements is crucial. From general liability to property damage and business interruption insurance, the right policies can provide a safety net against unexpected events that could threaten your financial stability.

    Coverage Options

    Small businesses face a unique set of risks that require tailored insurance coverage to mitigate potential financial losses. From property damage to liability claims, a comprehensive insurance policy can provide a safety net and ensure business continuity in the face of unexpected events.

    The types of insurance coverage available for small businesses vary depending on the industry, size, and specific needs of the business. Some common types of insurance policies include:

    • General Liability Insurance:Protects businesses from claims of bodily injury, property damage, or personal injury caused by their products, services, or operations.
    • Commercial Property Insurance:Covers physical assets such as buildings, equipment, inventory, and furniture against damage or loss due to fire, theft, or natural disasters.
    • Business Interruption Insurance:Provides coverage for lost income and expenses incurred if a business is forced to suspend operations due to a covered event.
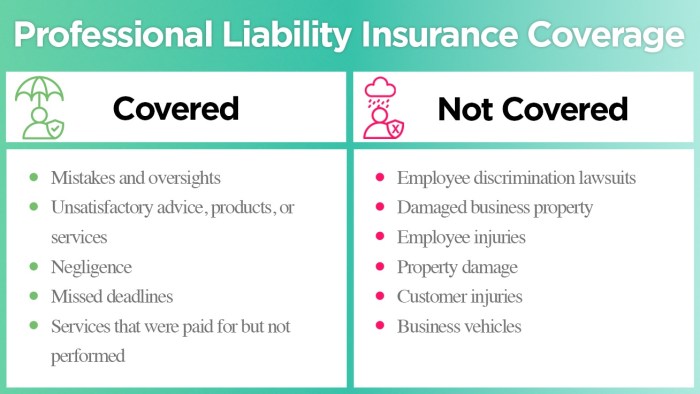
    • Errors and Omissions Insurance (E&O):Protects professionals, such as lawyers, accountants, and consultants, from claims of negligence or errors in their work.
    • Cyber Liability Insurance:Covers businesses against financial losses and legal liabilities arising from data breaches, cyberattacks, or other technology-related incidents.

    It’s crucial for small businesses to carefully assess their risks and tailor their insurance coverage accordingly. An experienced insurance agent can help businesses navigate the complex world of insurance options and select the policies that best meet their specific needs.

    Cost-Saving Strategies

    Reducing insurance premiums while maintaining adequate coverage is crucial for businesses seeking financial prudence. This section delves into effective cost-saving strategies, providing practical tips and case studies to help businesses optimize their insurance expenses.

    Negotiating with insurance companies is an art form that requires preparation and a thorough understanding of the market. By leveraging their knowledge of comparable policies and industry benchmarks, businesses can negotiate favorable terms that align with their specific needs and risk profile.

    Negotiation Strategies

    • Research and Compare:Gather quotes from multiple insurance providers to establish a baseline for negotiations. This allows businesses to identify the most competitive offers and leverage them during discussions.
    • Understand Your Coverage:Have a clear understanding of the coverage you need and the risks you want to mitigate. This knowledge empowers businesses to negotiate specific terms and avoid unnecessary coverage.
    • Leverage Industry Data:Utilize industry reports and statistics to support your negotiation points. Demonstrating an understanding of the market landscape strengthens your position and encourages insurance companies to offer more favorable terms.

    Case studies provide valuable insights into how businesses have successfully reduced their insurance costs. By examining real-world examples, businesses can glean practical strategies and learn from the experiences of others.

    Case Study: Manufacturing Company Reduces Insurance Costs by 20%, Cheap business insurance

    A manufacturing company implemented a comprehensive safety program that included employee training, equipment upgrades, and improved risk management practices. As a result, the company’s claims history improved significantly, leading to a 20% reduction in insurance premiums.

    Comparison of Providers

    Cheap business insurance

    When comparing business insurance providers, it’s crucial to evaluate their offerings, costs, and customer service to make an informed decision. Here’s a detailed comparison of some reputable providers to assist you in your research:

    Insurance Provider Comparison
    Provider Features Cost Customer Service Claims Processing Financial Stability
    Provider A Comprehensive coverage optionsCompetitive ratesOnline policy management Varies based on coverage and risk Excellent customer ratings

    /7 support

    Efficient and timely Strong financial backing
    Provider B Tailored coverage for specific industriesFlexible payment options Dedicated account manager Generally higher premiums Responsive and knowledgeableExtended business hours Thorough but may take longer
    Provider C Wide range of discounts and incentivesEasy online quoting Simplified claims process Competitive for small businesses Mixed customer reviewsLimited support availability Quick and convenient
    Provider D Specialty insurance for high-risk businessesCustomizable coverage options In-house claims handling Higher premiums for specialized coverage Excellent customer satisfactionPersonalized service Efficient and reliable
    Provider E Affordable premiums for startups and low-risk businessesBundling options for multiple policies Online risk management tools Limited coverage optionsBasic customer service Simple and straightforward

    Pros and Cons of Each Provider

    Provider A:Pros

    • Comprehensive coverage, competitive rates, excellent customer service. Cons
    • May not be the most affordable option.

    Provider B:Pros

    • Tailored coverage, flexible payment options, dedicated account manager. Cons
    • Higher premiums, less responsive customer service.

    Provider C:Pros

    • Discounts and incentives, easy online quoting, simplified claims process. Cons
    • Mixed customer reviews, limited support availability.

    Provider D:Pros

    • Specialty coverage, customizable options, in-house claims handling. Cons
    • Higher premiums for specialized coverage.

    Provider E:Pros

    • Affordable premiums, bundling options, online risk management tools. Cons
    • Limited coverage options, basic customer service.

    Industry-Specific Considerations: Cheap Business Insurance

    Insurance bechdel slideshares

    Different industries face unique risks and liabilities, which necessitate specialized insurance coverage. Understanding these industry-specific needs is crucial for businesses to adequately protect themselves from potential losses.

    Insurance companies offer tailored policies designed to address the specific risks associated with various industries. For instance, construction companies may require coverage for property damage, liability, and workers’ compensation, while healthcare providers need policies that cover medical malpractice and patient safety.

    Importance of Working with an Experienced Agent

    Working with an insurance agent who has a deep understanding of the specific risks faced by a business is essential. These agents can provide valuable guidance in selecting the most appropriate policies and ensuring that the coverage limits are adequate.

    They can also assist in negotiating favorable premiums and navigating the complexities of insurance contracts.

    Online Resources

    Online resources provide a convenient and efficient way to compare insurance quotes and find the best coverage at the lowest cost. Here’s a list of reputable websites and tools to help you:

    • Insureon:Provides instant quotes from multiple insurance companies.
    • The Zebra:Allows you to compare quotes side-by-side and offers personalized recommendations.
    • NerdWallet:Offers unbiased reviews and comparisons of insurance providers.
    • Policygenius:Guides you through the insurance selection process and provides expert advice.
    • CoverWallet:Specializes in online insurance for small businesses.

    To use these resources effectively, follow these steps:

    1. Gather your information:Have your business details, financial statements, and any relevant insurance history ready.
    2. Input your data:Enter the required information into the online tools to receive quotes.
    3. Compare quotes:Review the coverage options, premiums, and deductibles offered by different providers.
    4. Consider your needs:Choose the policy that best meets your business’s specific coverage requirements and budget.
    5. Read the fine print:Before purchasing, carefully review the policy terms and conditions to ensure you understand the coverage and exclusions.

    Tips to Avoid Scams

    When using online resources, it’s important to avoid scams. Here are some tips to protect yourself:

    • Check the provider’s legitimacy:Verify the company’s license and accreditation through reputable organizations like the Better Business Bureau (BBB) or state insurance departments.
    • Be wary of unsolicited offers:Avoid clicking on links or providing personal information in response to unsolicited emails or phone calls.
    • Use secure websites:Look for the “https” prefix in the website’s URL, indicating a secure connection.
    • Read reviews:Check online reviews and testimonials from other customers to gauge the provider’s reputation.
    • Don’t rush:Take your time to research and compare multiple quotes before making a decision.

    Ending Remarks

    Cheap business insurance

    Remember, cheap business insurance is not about cutting corners—it’s about finding the optimal balance between coverage and cost. By leveraging the tips and resources Artikeld in this guide, you can empower your business with affordable protection that ensures its long-term success.

    Essential Questionnaire

    What are the key factors to consider when choosing cheap business insurance?

    Coverage options, cost-effectiveness, and provider reputation are all crucial factors to evaluate.

    How can I reduce my business insurance premiums without compromising coverage?

    Implementing risk management measures, negotiating with insurers, and comparing quotes from multiple providers can help lower costs.

    What are some industry-specific insurance considerations for small businesses?

    Unique risks associated with different industries necessitate specialized policies tailored to their specific needs.

  • Emergency Money Assistance: A Comprehensive Guide to Navigating Financial Crises

    Emergency Money Assistance: A Comprehensive Guide to Navigating Financial Crises

    Emergency money assistance is a lifeline for individuals and families facing unexpected financial setbacks. This comprehensive guide delves into the various programs, resources, and strategies available to help you weather financial storms and regain stability.

    From government assistance to non-profit organizations, this guide provides a roadmap to accessing emergency funds, managing debt, and safeguarding your emotional and mental well-being during challenging times.

    Financial Assistance Programs

    Emergency fund saving money start funds emergencies why savings unexpected need build financial much benefits should planning reasons possible soon

    Individuals and families facing financial emergencies can seek assistance from various government and non-profit programs designed to provide temporary financial relief. These programs offer a range of benefits, including cash assistance, housing support, food assistance, and utility assistance.

    Government Programs

    Government-funded programs provide financial assistance to low-income individuals and families who meet specific eligibility criteria. These programs are typically administered by state or local agencies.

    • Temporary Assistance for Needy Families (TANF):TANF provides cash assistance to low-income families with children. Eligibility requirements vary by state, but generally include income limits, work requirements, and time limits on benefits.
    • Supplemental Nutrition Assistance Program (SNAP):SNAP, formerly known as food stamps, provides food assistance to low-income individuals and families. Eligibility is based on income and asset limits.
    • Supplemental Security Income (SSI):SSI provides monthly cash payments to low-income individuals who are aged, blind, or disabled. Eligibility is based on income and asset limits, as well as medical documentation of disability.
    • Housing Choice Voucher Program (Section 8):Section 8 provides rental assistance to low-income families. Eligible families receive a voucher that they can use to rent a unit in the private market.
    • Low Income Home Energy Assistance Program (LIHEAP):LIHEAP provides financial assistance to low-income households to help pay for heating and cooling costs.

    Non-Profit Programs, Emergency money assistance

    Non-profit organizations also offer financial assistance to individuals and families in need. These programs may provide cash assistance, food assistance, housing assistance, or other forms of support.

    • United Way:United Way is a non-profit organization that provides financial assistance to individuals and families in need. United Way offers a variety of programs, including emergency cash assistance, food assistance, and housing assistance.
    • Salvation Army:The Salvation Army is a non-profit organization that provides financial assistance to individuals and families in need. The Salvation Army offers a variety of programs, including emergency cash assistance, food assistance, and housing assistance.
    • Catholic Charities:Catholic Charities is a non-profit organization that provides financial assistance to individuals and families in need. Catholic Charities offers a variety of programs, including emergency cash assistance, food assistance, and housing assistance.

    Non-Governmental Aid

    In times of financial crisis, non-governmental organizations (NGOs) and crowdfunding platforms play a crucial role in providing emergency money assistance to individuals and families. These organizations offer a range of services, including financial grants, loans, and counseling, to help people overcome financial challenges.

    Charitable Organizations

    Numerous charitable organizations offer emergency money assistance to individuals and families facing financial hardship. These organizations typically provide financial grants or loans to help people cover essential expenses such as rent, utilities, food, and medical care.

    • Salvation Army: The Salvation Army provides financial assistance, food, and shelter to individuals and families in need. They offer emergency grants to help people cover basic expenses.
    • United Way: United Way is a network of local charities that provides financial assistance, counseling, and other services to individuals and families in need. They offer emergency grants to help people cover essential expenses.
    • Catholic Charities: Catholic Charities provides financial assistance, food, and shelter to individuals and families in need. They offer emergency grants to help people cover basic expenses.

    Crowdfunding Platforms

    Crowdfunding platforms allow individuals to raise money from a large number of people, typically through online donations. These platforms can be a valuable resource for people who need emergency financial assistance and do not qualify for traditional loans or grants.

    • GoFundMe: GoFundMe is a popular crowdfunding platform that allows individuals to raise money for a variety of purposes, including emergency financial assistance.
    • YouCaring: YouCaring is a crowdfunding platform that specializes in raising money for medical expenses. They offer a variety of resources to help people create and manage crowdfunding campaigns.
    • Fundly: Fundly is a crowdfunding platform that allows individuals to raise money for a variety of purposes, including emergency financial assistance. They offer a variety of tools to help people create and manage crowdfunding campaigns.

    Budgeting and Debt Management

    Emergency money assistance

    Managing your finances during an emergency can be daunting, but it’s essential to take control of your budget and debt to mitigate the financial impact. Here’s a guide to help you navigate this challenging time.

    Creating a Budget

    A budget is a roadmap that Artikels your income and expenses. It helps you track your spending, identify areas for improvement, and make informed financial decisions. To create a budget:

    • Track your income and expenses:Note down all sources of income and every expense, no matter how small.
    • Categorize expenses:Group expenses into categories like housing, food, transportation, and entertainment.
    • Set financial goals:Determine your financial objectives, such as paying off debt or saving for an emergency fund.
    • Adjust your budget:Regularly review and adjust your budget based on your income and expenses.

    Managing Debt

    Debt can be a significant burden during an emergency. Here are strategies to manage debt effectively:

    • Consolidate your debt:Combine multiple debts into a single loan with a lower interest rate, reducing monthly payments and saving on interest.
    • Negotiate with creditors:Contact your creditors to discuss payment plans, interest rate reductions, or other options to alleviate your debt burden.
    • Explore debt relief programs:Consider government or non-profit programs that offer assistance with debt management or repayment.

    Reducing Expenses

    Reducing expenses is crucial during an emergency to free up more cash flow. Here are some tips:

    • Negotiate lower bills:Contact service providers like utility companies, insurance companies, and internet providers to negotiate lower rates or payment plans.
    • Cut unnecessary expenses:Identify non-essential expenses, such as entertainment or dining out, and eliminate or reduce them.
    • li> Use coupons and discounts:Take advantage of coupons, promo codes, and discounts to save on purchases.

    • Explore shared expenses:Consider sharing expenses like housing, utilities, or transportation with roommates or family members.

    Increasing Income

    Increasing your income can help you offset expenses and pay down debt faster. Here are some strategies:

    • Get a part-time job or freelance:Explore additional income sources to supplement your primary income.
    • Sell unused items:Declutter your home and sell items you no longer need to generate extra cash.
    • Rent out a room or property:If possible, consider renting out a spare room or property to generate additional income.
    • Start a small business:Explore entrepreneurial opportunities to create a passive or active income stream.

    Legal Considerations: Emergency Money Assistance

    Receiving emergency financial assistance involves legal implications that need careful consideration. Understanding these implications can help individuals make informed decisions and avoid potential pitfalls.

    Emergency financial assistance often comes in the form of loans, which carry specific repayment terms and consequences for defaulting. Failure to repay loans on time can damage credit scores, making it difficult to obtain future loans or qualify for other financial products.

    Repayment Terms

    Repayment terms for emergency financial assistance vary depending on the lender and the type of loan. Some loans may have fixed repayment schedules with regular monthly payments, while others may offer more flexible repayment options.

    It’s crucial to carefully review the loan agreement and understand the repayment terms, including the interest rate, loan amount, and payment due dates. Failure to meet repayment obligations can result in penalties, fees, or even legal action.

    Consequences of Defaulting

    Defaulting on an emergency financial assistance loan can have serious consequences. Lenders may report the default to credit bureaus, which can negatively impact an individual’s credit score.

    A damaged credit score can make it difficult to qualify for future loans, credit cards, or other financial products. Additionally, defaulting on a loan may lead to legal action, such as wage garnishment or asset seizure.

    Seeking Legal Advice

    Individuals facing financial difficulties should consider seeking legal advice from an attorney or financial counselor. Legal professionals can provide guidance on understanding loan agreements, negotiating repayment plans, and exploring options for debt management.

    Seeking legal advice can help individuals navigate the legal complexities of emergency financial assistance and make informed decisions that protect their financial well-being.

    Emotional and Mental Health Support

    Financial emergencies can take a significant toll on our emotional and mental well-being. The stress, anxiety, and uncertainty associated with financial difficulties can lead to a range of mental health issues, including depression, anxiety disorders, and even suicidal thoughts.

    It’s important to remember that you are not alone. Many people experience financial emergencies at some point in their lives. There are resources available to help you cope with the emotional and mental toll of financial hardship.

    Mental Health Support and Counseling Services

    There are a number of mental health support and counseling services available to people who are struggling with financial emergencies. These services can provide you with support, guidance, and coping mechanisms to help you manage the emotional and mental challenges of financial hardship.

    • The National Suicide Prevention Lifeline: 1-800-273-TALK (8255)
    • The National Alliance on Mental Illness (NAMI): 1-800-950-NAMI (6264)
    • The Anxiety and Depression Association of America (ADAA): 1-800-829-1982

    Coping Mechanisms and Strategies for Managing Stress and Anxiety

    In addition to seeking professional help, there are a number of coping mechanisms and strategies that you can use to manage the stress and anxiety associated with financial emergencies.

    • Talk to someone you trust about what you’re going through.
    • Exercise regularly to reduce stress and improve your mood.
    • Get enough sleep.
    • Eat healthy foods.
    • Practice relaxation techniques, such as yoga or meditation.
    • Set realistic financial goals and create a budget.
    • Seek out financial assistance programs and other resources that can help you manage your debt.

    Final Summary

    Emergency money assistance

    Navigating financial emergencies can be daunting, but with the right knowledge and support, it is possible to overcome these challenges and emerge stronger. This guide empowers you with the tools and resources you need to weather financial storms and achieve long-term financial stability.

    Quick FAQs

    What are the eligibility criteria for government emergency financial assistance programs?

    Eligibility criteria vary depending on the program. Generally, applicants must demonstrate financial hardship, such as job loss, medical expenses, or natural disasters.

    How can I access emergency money assistance from non-profit organizations?

    Contact local charities or visit their websites to inquire about emergency assistance programs. Some organizations may require proof of income or documentation of financial hardship.

    What are the legal implications of receiving emergency financial assistance?

    Emergency loans may come with repayment terms and interest rates. It is important to understand the terms of the loan and seek legal advice if you have any concerns about repayment.

  • M&A Lawyers: Guiding Complex Transactions with Expertise and Strategy

    M&A Lawyers: Guiding Complex Transactions with Expertise and Strategy

    M&A lawyers stand at the forefront of complex business transactions, navigating legal intricacies with expertise and strategic guidance. They play a pivotal role in shaping the corporate landscape, ensuring smooth mergers, acquisitions, and other transformative deals.

    With a deep understanding of the legal complexities involved in M&A transactions, these lawyers provide invaluable support to clients, guiding them through the complexities of due diligence, negotiation, and regulatory compliance.

    Legal Expertise and Experience

    M&A lawyer

    M&A lawyers require a comprehensive understanding of the legal complexities involved in mergers and acquisitions. They must be well-versed in corporate law, securities law, antitrust law, and tax law. Additionally, they should have experience in negotiating and drafting complex legal agreements, conducting due diligence investigations, and managing regulatory approvals.

    Types of M&A Transactions, M&A lawyer

    M&A transactions can take various forms, including mergers, acquisitions, divestitures, and joint ventures. Each type of transaction presents unique legal challenges, and M&A lawyers must be familiar with the specific legal requirements and regulations that apply to each type.

    Legal Due Diligence

    Legal due diligence is a critical step in any M&A transaction. It involves a thorough investigation of the target company’s legal, financial, and operational condition. The purpose of due diligence is to identify potential risks and liabilities that could impact the transaction.

    M&A lawyers play a key role in conducting due diligence, ensuring that all relevant legal issues are addressed and that the client is fully informed of the risks involved.

    Industry Knowledge and Market Trends

    M&A lawyer

    Industry knowledge is paramount for M&A lawyers as it enables them to understand the nuances of the industries they operate in. This understanding helps them provide tailored advice to their clients, anticipate potential issues, and navigate the complex regulatory landscape.

    Current market trends, such as the rise of digitalization and globalization, have a significant impact on M&A transactions. Lawyers must stay abreast of these trends to effectively advise their clients on the potential risks and opportunities they present.

    Regulatory Landscape

    The regulatory landscape plays a crucial role in shaping M&A activity. Lawyers must be well-versed in the relevant laws and regulations to ensure compliance and mitigate potential legal risks. They must also monitor changes in the regulatory environment to anticipate their impact on future transactions.

    Communication and Negotiation Skills

    Effective communication and negotiation skills are essential for M&A lawyers. They must be able to clearly and concisely communicate complex legal concepts to clients, other lawyers, and business professionals. They must also be able to negotiate effectively on behalf of their clients, ensuring that their interests are protected.

    There are a number of different negotiation strategies that can be used in M&A transactions. Some of the most common strategies include:

    • Positional bargaining:This is a traditional negotiation strategy in which each party starts by stating their desired outcome and then gradually moves towards a compromise.
    • Interest-based bargaining:This is a more collaborative negotiation strategy in which the parties focus on identifying their underlying interests and then working together to find a solution that meets the needs of both parties.
    • Principled negotiation:This is a negotiation strategy that is based on the principles of fairness, objectivity, and mutual respect. The goal of principled negotiation is to reach an agreement that is fair to both parties and that is based on objective criteria.

    In addition to strong communication and negotiation skills, M&A lawyers must also be able to build strong relationships with clients and other parties involved in the transaction. This includes developing a deep understanding of the client’s business and objectives, as well as being able to work effectively with other professionals, such as accountants, investment bankers, and financial advisors.

    Ethical Considerations and Professional Responsibilities: M&A Lawyer

    M&A lawyers are bound by strict ethical considerations and professional responsibilities. These include adhering to the highest standards of integrity, maintaining confidentiality, and avoiding conflicts of interest.

    One of the most important ethical considerations for M&A lawyers is maintaining confidentiality. M&A transactions often involve sensitive information, such as financial data, business plans, and trade secrets. Lawyers must take all necessary steps to protect this information from unauthorized disclosure.

    Conflicts of Interest

    Another important ethical consideration for M&A lawyers is avoiding conflicts of interest. A conflict of interest arises when a lawyer has a personal or financial interest that could impair their ability to represent their client objectively. For example, a lawyer cannot represent both the buyer and seller in an M&A transaction.

    Professional Responsibilities

    M&A lawyers have a professional responsibility to provide their clients with the highest quality legal advice. They must also act in the best interests of their clients and the public. This means that M&A lawyers must be honest, diligent, and competent.

    Career Path and Advancement Opportunities

    The career path of an M&A lawyer offers a dynamic and rewarding journey, with opportunities for advancement and specialization. As you progress through your career, you will assume increasingly complex roles and responsibilities, broadening your legal expertise and strategic advisory skills.

    In the early stages of your career, you may work as an associate attorney, assisting senior lawyers with due diligence, drafting transaction documents, and negotiating agreements. With experience and proven performance, you can progress to a senior associate or counsel position, taking on more responsibility for managing transactions and advising clients.

    Partnership and Leadership

    At the partnership level, you will have a significant role in developing and executing the firm’s M&A strategy, mentoring junior lawyers, and building client relationships. As you advance in your career, you may assume leadership positions within the firm, such as practice group leader or managing partner, overseeing the overall direction and growth of the M&A practice.

    Tips for Advancement

    To achieve professional success in M&A law, consider the following tips:

    • Develop a strong foundation in corporate law and finance.
    • Gain practical experience through internships or secondments.
    • Build a network of industry professionals and potential clients.
    • Stay updated on legal and regulatory developments.
    • li>Seek mentorship from experienced lawyers.

    • Develop excellent communication, negotiation, and analytical skills.

    Ultimate Conclusion

    M&A lawyer

    In conclusion, M&A lawyers are indispensable partners in the world of business transactions. Their expertise, communication skills, and ethical considerations empower them to facilitate successful deals that shape the future of companies and industries.

    Query Resolution

    What is the primary role of an M&A lawyer?

    M&A lawyers advise clients on legal aspects of mergers, acquisitions, and other complex business transactions, ensuring compliance and protecting their interests.

    What skills are essential for an M&A lawyer?

    M&A lawyers require a strong foundation in corporate law, negotiation skills, and an understanding of industry trends and regulations.

    What are the ethical considerations for M&A lawyers?

    M&A lawyers must maintain confidentiality, avoid conflicts of interest, and act in the best interests of their clients while adhering to professional standards.