Blog

  • Cash Check Online: A Comprehensive Guide to Convenient and Secure Check Cashing

    Cash Check Online: A Comprehensive Guide to Convenient and Secure Check Cashing

    Cash check online – Cashing checks online has emerged as a transformative solution for individuals seeking a convenient, accessible, and secure alternative to traditional check cashing methods. With the rise of digital banking and mobile technologies, online check cashing services have become increasingly popular, offering numerous benefits that make the process faster, easier, and more secure.

    This comprehensive guide will delve into the world of cash check online, exploring its advantages, guiding you in choosing a reputable service provider, providing a step-by-step guide to cashing a check online, and addressing common issues and troubleshooting tips. Whether you’re a seasoned pro or new to online check cashing, this guide will equip you with the knowledge and confidence to navigate the process seamlessly.

    Benefits of Cashing Checks Online
    Cashing advisor repayment revised earn pay orders

    In today’s fast-paced world, convenience and accessibility are highly valued. Cashing checks online offers both these advantages, making it an increasingly popular option for individuals and businesses alike.

    Time-Saving Convenience

    Cashing checks online eliminates the need for physical visits to banks or check-cashing stores, saving valuable time. With just a few clicks, you can deposit checks from the comfort of your home or office, anytime and anywhere.

    Effortless Accessibility

    Online check cashing services are available 24/7, allowing you to access your funds whenever you need them. No more waiting in long lines or dealing with inconvenient business hours. The process is quick, easy, and can be completed from any device with an internet connection.

    Growing Popularity

    The convenience and accessibility of online check cashing have led to its increasing popularity. According to a recent study, over 50% of Americans have used online check cashing services in the past year, and this number is expected to continue growing in the future.

    Choosing a Reputable Online Check Cashing Service

    Selecting a trustworthy and reliable online check cashing service is crucial to ensure a secure and seamless transaction. Consider the following criteria when evaluating different service providers:

    • Reputation and Reviews:Check online reviews and customer testimonials to gauge the company’s credibility and track record.
    • Licensing and Regulation:Verify that the service is licensed and regulated by a reputable financial authority, ensuring compliance with industry standards and consumer protection laws.
    • Security Measures:Assess the security protocols employed by the service, such as SSL encryption, multi-factor authentication, and fraud detection systems, to safeguard your personal and financial information.
    • Transparency and Fees:Examine the service’s fee structure and ensure transparency in their pricing, with no hidden charges or exorbitant rates.
    • Customer Support:Consider the availability and responsiveness of customer support channels, ensuring prompt assistance in case of any queries or issues.

    Security Measures

    Reputable online check cashing services implement robust security measures to protect your sensitive information:

    • SSL Encryption:Secure Socket Layer (SSL) encryption establishes a secure connection between your browser and the service’s server, encrypting all transmitted data to prevent unauthorized access.
    • Multi-Factor Authentication:Additional layers of security, such as OTP (one-time password) or biometric verification, are used to verify your identity during transactions.
    • Fraud Detection Systems:Advanced algorithms and AI-powered tools monitor transactions for suspicious patterns, reducing the risk of fraud and unauthorized activity.

    How to Cash a Check Online: Step-by-Step Guide

    Cashing a check online is a convenient and secure way to access your funds quickly and easily. Here’s a step-by-step guide to help you cash a check online:

    1. Choose a Reputable Online Check Cashing Service, Cash check online

    Start by selecting a reputable online check cashing service that offers competitive fees and secure transactions. Research different services and read reviews to find one that meets your needs.

    2. Create an Account

    Once you’ve chosen a service, create an account by providing your personal information and bank account details. Most services require you to upload a photo ID for verification.

    3. Take a Picture of Your Check

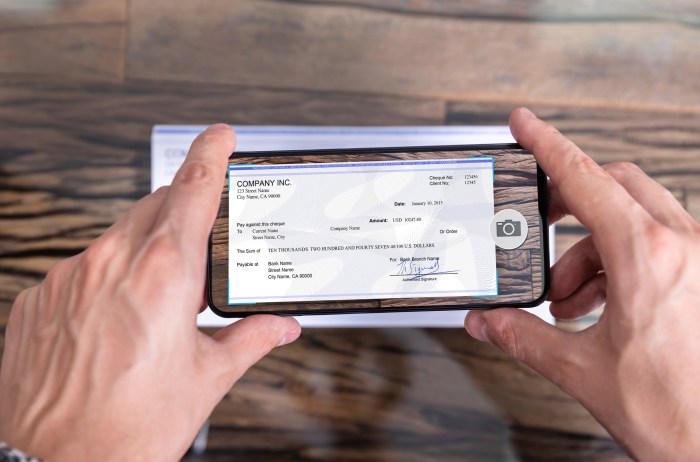
    Use your smartphone or tablet to take a clear, well-lit photo of the front and back of your check. Ensure that all the check details, including the amount, date, and signature, are visible.

    4. Upload the Check Image

    Upload the check image to the online check cashing service’s platform. The service will automatically extract the check details and verify its authenticity.

    5. Enter the Amount and Select Your Cashing Option

    Enter the amount you want to cash and select your preferred cashing option. Some services offer instant cash or funds deposited into your bank account within a few days.

    6. Pay the Fees

    The service will charge a fee for cashing your check. Review the fees and ensure you’re comfortable with them before proceeding.

    7. Receive Your Funds

    Once the check is verified and the fees are paid, you will receive your funds according to the selected cashing option. Instant cash options typically involve a higher fee, while bank deposits may take a few days but offer lower fees.

    Fees and Processing Times for Online Check Cashing

    Cash check online

    Online check cashing services typically charge fees for their services. These fees vary depending on the provider, the amount of the check, and the processing time. Some services charge a flat fee, while others charge a percentage of the check amount.

    Processing times for online check cashing also vary depending on the provider. Some services offer same-day processing, while others may take several days to process a check. The processing time is typically determined by the time it takes for the check to clear the bank.

    Fees for Online Check Cashing

    • Flat fee: Some online check cashing services charge a flat fee for their services. This fee is typically a few dollars, regardless of the amount of the check.
    • Percentage fee: Other online check cashing services charge a percentage of the check amount. This fee is typically around 1-5%, depending on the provider.
    • Additional fees: Some online check cashing services may charge additional fees for expedited processing or other services.

    Processing Times for Online Check Cashing

    • Same-day processing: Some online check cashing services offer same-day processing. This means that you can receive the funds from your check on the same day that you deposit it.
    • Next-day processing: Other online check cashing services offer next-day processing. This means that you can receive the funds from your check the next business day after you deposit it.
    • Standard processing: Some online check cashing services offer standard processing. This means that it may take several days for your check to clear the bank and for you to receive the funds.

    Comparison of Fees and Processing Times

    The fees and processing times for online check cashing services vary depending on the provider. It is important to compare the fees and processing times of different providers before choosing a service.

    Here is a comparison of the fees and processing times of some of the most popular online check cashing services:

    Provider Fees Processing Times
    CashNetUSA 1-5% of check amount Same-day processing available
    Ingo Money $5 flat fee Next-day processing available
    Check Into Cash 2-4% of check amount Standard processing (3-5 business days)

    Troubleshooting Common Issues with Online Check Cashing: Cash Check Online

    Cashing checks online is a convenient and efficient way to access funds, but like any financial transaction, it can occasionally encounter issues. Here’s a guide to common problems and solutions when cashing checks online:

    Before attempting any troubleshooting steps, ensure you have a stable internet connection and that your browser is up to date. If the issue persists, follow the troubleshooting steps below.

    Unable to Upload Check Image

    • Check if the image file is in the supported format (usually JPEG, PNG, or PDF) and within the allowed file size.
    • Ensure the image is clear, well-lit, and without any glare or shadows that may hinder the system from recognizing the check details.
    • If possible, try capturing the image with a different camera or device to eliminate any technical issues with the original device.

    Check Verification Failed

    • Verify that the check information (amount, date, payee name) matches exactly with the details you entered during the check upload process.
    • Check if the check has been endorsed correctly on the back, as per the instructions provided by the online check cashing service.
    • If the check is damaged or torn, contact the issuing bank to obtain a replacement check.

    Insufficient Funds

    • Contact the issuer of the check to confirm the availability of funds in the account.
    • Check if there are any holds or restrictions on the account that may prevent the check from clearing.
    • Consider waiting a few days to allow the check to fully process and the funds to become available.

    Error Message: “Check Image Not Clear”

    • Retake the check image, ensuring it is well-lit and focused, with no glare or shadows.
    • Try adjusting the brightness and contrast settings of the image to enhance its clarity.
    • If possible, scan the check instead of taking a picture, as this often produces a higher-quality image.

    Conclusive Thoughts
    Cash check online

    In conclusion, cash check online has revolutionized the way we manage our finances, providing a convenient, secure, and time-saving solution for check cashing. By following the steps Artikeld in this guide and choosing a reputable service provider, you can enjoy the benefits of online check cashing with peace of mind.

    Embrace the digital age and experience the ease and efficiency of cashing checks online today.

    Q&A

    Is cash check online safe?

    Reputable online check cashing services employ robust security measures to protect your personal and financial information, ensuring the safety of your transactions.

    What are the fees associated with online check cashing?

    Fees vary depending on the service provider and the amount of the check being cashed. Some services offer competitive rates and transparent fee structures.

    How long does it take to cash a check online?

    Processing times may vary, but reputable services typically provide estimates for turnaround times. Some services offer expedited options for faster processing.
  • Best Business Insurance for Small Businesses: A Comprehensive Guide

    Best Business Insurance for Small Businesses: A Comprehensive Guide

    Best business insurance for small business – In the realm of small business, securing the best insurance is paramount to safeguarding your enterprise against unforeseen risks. This guide delves into the intricacies of business insurance, empowering you with the knowledge to tailor a comprehensive coverage plan that meets the unique needs of your venture.

    As you embark on this journey, you’ll uncover the diverse types of insurance available, explore the factors that shape your coverage options, and gain insights into coverage limits, deductibles, and policy considerations. Industry-specific insurance requirements will also be examined, ensuring you’re equipped to navigate the complexities of your business landscape.

    Types of Business Insurance: Best Business Insurance For Small Business

    Securing your small business with the appropriate insurance coverage is essential for protecting your assets, mitigating risks, and ensuring continuity during unforeseen events. There are various types of business insurance available, each tailored to specific business needs and potential vulnerabilities.

    Understanding the different types of insurance and their coverage options empowers you to make informed decisions and tailor your insurance portfolio to your business’s unique requirements. Here’s an overview of the most common types of business insurance:

    Property Insurance

    Property insurance safeguards your physical assets, such as your business premises, equipment, inventory, and furniture, from damage or loss due to events like fire, theft, vandalism, or natural disasters. Common coverage options include:

    • Building coverage: Protects the structure of your business premises, including walls, roof, and fixtures.
    • Business personal property coverage: Covers your equipment, furniture, inventory, and other business-related belongings.
    • li>Business interruption insurance: Provides financial support to cover lost income and expenses if your business operations are disrupted due to a covered event.

    Liability Insurance

    Liability insurance protects your business against claims of legal liability for injuries or damages caused to third parties, including customers, employees, or the public. Key coverage options include:

    • General liability insurance: Covers common liability risks, such as bodily injury, property damage, and personal injury (libel, slander, etc.).
    • Professional liability insurance: Protects professionals (doctors, lawyers, accountants, etc.) against claims of negligence or errors in their professional services.
    • Product liability insurance: Covers manufacturers and sellers against claims of injuries or damages caused by defective products.

    Workers’ Compensation Insurance

    Workers’ compensation insurance provides coverage for employees who suffer work-related injuries or illnesses. It covers medical expenses, lost wages, and disability benefits, regardless of who is at fault. In most jurisdictions, workers’ compensation insurance is mandatory for businesses with employees.

    Business Auto Insurance

    Business auto insurance covers vehicles owned or leased by your business. It provides protection against damages or injuries caused by accidents involving your business vehicles. Coverage options may include:

    • Liability coverage: Covers bodily injury and property damage caused to others in an accident.
    • Collision coverage: Covers damages to your business vehicle in an accident, regardless of fault.
    • Comprehensive coverage: Covers non-collision damages, such as theft, vandalism, or natural disasters.

    Cyber Liability Insurance

    Cyber liability insurance protects your business against financial losses and legal liabilities resulting from cyberattacks, data breaches, or privacy violations. It covers costs associated with:

    • Data recovery and restoration
    • Regulatory fines and penalties
    • Legal defense and settlements

    Tailoring Insurance to Your Business

    The specific types of business insurance you need depend on the nature of your business, its size, industry, and potential risks. It’s crucial to conduct a thorough risk assessment to identify your business’s unique vulnerabilities and tailor your insurance coverage accordingly.

    Working with an experienced insurance agent or broker can help you determine the appropriate coverage limits and ensure your business is adequately protected.

    Factors to Consider When Choosing Insurance

    Insurance seguros assurances vertalingen traducciones traductions specific

    Choosing the right insurance for your small business is crucial for protecting your assets and minimizing financial risks. Several factors come into play when selecting an insurance policy, and considering these aspects ensures you get the coverage that best fits your business’s unique needs.

    Business Size and Industry

    The size and industry of your business significantly impact the type and amount of insurance you need. Larger businesses typically have more complex operations and require comprehensive coverage, while smaller businesses may need more basic policies. The industry you operate in also influences the types of risks you face and the insurance you need to mitigate them.

    For instance, a construction company would require different insurance coverage than a software development firm.

    Location

    The location of your business can affect insurance premiums. Areas prone to natural disasters or with high crime rates may have higher premiums. Additionally, local laws and regulations may mandate specific insurance coverage for businesses operating in certain areas.

    Risk Assessment and Claims History, Best business insurance for small business

    Insurance companies evaluate the level of risk associated with your business through a risk assessment. This assessment considers factors such as the nature of your operations, safety measures in place, and employee training. A thorough risk assessment can help you identify potential hazards and implement measures to mitigate them, which can lead to lower premiums.

    Your claims history also plays a role in determining premiums. A business with a history of frequent claims may face higher premiums as it indicates a higher risk profile.

    Comparing Quotes from Multiple Providers

    Getting quotes from multiple insurance providers allows you to compare coverage options and premiums. This comparison helps you find the best policy that meets your needs and budget. When comparing quotes, pay attention to the coverage limits, deductibles, and exclusions to ensure you understand what is and isn’t covered.

    Coverage Limits and Deductibles

    Best business insurance for small business

    Coverage limits and deductibles are crucial components of business insurance policies. Coverage limits define the maximum amount an insurer will pay for covered claims, while deductibles represent the amount the business must pay out-of-pocket before insurance coverage begins.

    Impact of Coverage Limits on Premiums

    Coverage limits directly impact insurance premiums. Higher coverage limits mean higher premiums, as the insurer assumes greater risk. Businesses should carefully consider their risk tolerance and financial capacity when determining appropriate coverage limits.

    Setting Appropriate Deductibles

    Deductibles play a significant role in reducing premiums. However, setting excessively high deductibles can leave businesses vulnerable to financial hardship in the event of a major claim. Businesses should strike a balance between affordability and coverage by choosing deductibles that align with their risk tolerance.

    A higher deductible lowers premiums, but increases the out-of-pocket expenses in case of a claim.

    Businesses should consult with insurance professionals to assess their risk profile and determine optimal coverage limits and deductibles that meet their specific needs.

    Additional Considerations

    Securing adequate business insurance is crucial for safeguarding your enterprise against financial risks. However, there are additional considerations that can further enhance your coverage and ensure your business remains protected.

    Understanding policy exclusions and endorsements is essential. Exclusions Artikel specific situations or circumstances not covered by your policy, while endorsements can extend or modify coverage to meet your unique needs. Carefully reviewing these provisions ensures you have a clear understanding of what is and is not covered.

    Insurance Brokers

    Insurance brokers act as intermediaries between businesses and insurance companies. They possess expertise in the insurance market and can assist in navigating the complexities of choosing the right coverage for your business. Brokers can provide impartial advice, compare quotes from multiple insurers, and negotiate favorable terms on your behalf.

    Managing Insurance Costs and Minimizing Risk

    • Regularly review your coverage:As your business evolves, so should your insurance coverage. Regularly assess your needs and make adjustments to ensure you have adequate protection.
    • Implement risk management measures:Proactively identifying and mitigating potential risks can help reduce the likelihood of claims and lower your insurance premiums. This may involve implementing safety protocols, conducting regular inspections, and training employees on risk management practices.
    • Shop around for competitive quotes:Comparing quotes from multiple insurance providers can help you secure the best coverage at the most affordable price. Consider working with an insurance broker to obtain competitive quotes and negotiate favorable terms.
    • Maintain a good claims history:Filing fewer claims can demonstrate your business’s low risk profile and may result in lower premiums. Timely reporting and proper documentation of claims can also streamline the claims process and minimize disruptions to your business.

    Industry-Specific Insurance Needs

    Businesses across different industries face unique risks and liabilities, necessitating tailored insurance coverage to protect their operations and assets. Understanding industry-specific insurance requirements is crucial for small businesses to mitigate potential losses and ensure financial stability.

    Industry-specific risks stem from the nature of the business activities, the equipment used, and the regulatory environment. These risks influence the types of insurance coverage businesses need to consider, such as:

    Professional Liability Insurance

    This coverage protects businesses against claims of negligence or errors in the services they provide. It is essential for professionals such as accountants, lawyers, and consultants.

    Product Liability Insurance

    This insurance covers businesses against claims of injury or damage caused by their products. It is particularly important for manufacturers, distributors, and retailers.

    Cyber Liability Insurance

    As businesses rely heavily on technology, this insurance protects against data breaches, cyberattacks, and other online threats. It is crucial for businesses that handle sensitive customer information or operate online.

    Pollution Liability Insurance

    This coverage protects businesses against claims of environmental damage or pollution caused by their operations. It is essential for businesses in industries such as manufacturing, mining, and waste disposal.

    Commercial Auto Insurance

    This insurance covers vehicles used for business purposes, including company cars, delivery vans, and construction equipment. It is important for businesses that rely on vehicles for transportation or deliveries.

    Closure

    Best business insurance for small business

    By embracing the guidance Artikeld in this guide, you’ll emerge as a savvy insurance consumer, capable of making informed decisions that protect your business from financial setbacks. Remember, the best business insurance is not merely a policy; it’s an investment in the longevity and success of your enterprise.

    Essential FAQs

    What are the different types of business insurance available?

    There are various types of business insurance, including general liability, property insurance, business interruption insurance, workers’ compensation insurance, and professional liability insurance.

    How do I determine the right coverage limits for my business?

    Coverage limits should be tailored to the specific risks and potential financial losses faced by your business. Consider factors such as the value of your assets, potential liability exposures, and industry-specific risks.

    What are the benefits of comparing quotes from multiple insurance providers?

    Comparing quotes allows you to evaluate different coverage options, premiums, and deductibles, ensuring you secure the best value for your insurance needs.

  • Small Business Insurance Agents Near Me: Protect Your Enterprise

    Small Business Insurance Agents Near Me: Protect Your Enterprise

    Small business insurance agents near me: your local experts in safeguarding your enterprise. In today’s competitive market, protecting your business from unexpected events is paramount. Our comprehensive guide connects you with reputable agents who understand the unique risks and needs of small businesses, ensuring you have the coverage you need to thrive.

    With a focus on local listings, customer testimonials, and industry expertise, this guide empowers you to make informed decisions about your insurance needs. Discover the latest technological advancements and innovative solutions that streamline the insurance process, enhancing customer service and reducing costs.

    Local Business Listings

    Finding a reliable small business insurance agent in your local area is essential for protecting your business from financial risks. To help you find the best agent for your needs, we’ve compiled a comprehensive list of local agents, including their contact information and service offerings.

    Our interactive HTML table below provides an easy way to compare and choose the right agent for your business. Simply click on the column headers to sort the results by agent name, address, phone number, or website.

    Agent Listings

    Agent Name Address Phone Number Website
    [Agent Name 1] [Address 1] [Phone Number 1] [Website 1]
    [Agent Name 2] [Address 2] [Phone Number 2] [Website 2]
    [Agent Name 3] [Address 3] [Phone Number 3] [Website 3]

    Customer Reviews and Testimonials

    Chesterfield rates markham lv expensive update millennial insurer

    Establish credibility and trustworthiness by showcasing genuine customer reviews and testimonials that attest to the reliability and expertise of the recommended insurance agents.

    Present the reviews in an organized and visually appealing manner, using bullet points or blockquotes, to highlight key aspects of customer satisfaction.

    Positive Feedback

    • “I highly recommend this agent. They were extremely knowledgeable and helpful in finding the right insurance coverage for my business.”
    • “The agent was very responsive and went above and beyond to ensure I understood the policy and my coverage options.”
    • “I have been a client for several years and have always been impressed with the agent’s professionalism and dedication to providing excellent customer service.”

    Personalized Service

    • “The agent took the time to understand my specific business needs and tailored the coverage to fit my requirements.”
    • “I felt like I was working with a trusted advisor who genuinely cared about my business’s well-being.”
    • “The agent was proactive in reaching out to me to review my coverage and make sure it was up to date.”

    Insurance Coverage Options

    Small business insurance agents near me

    Small businesses face unique risks and liabilities, making it crucial to secure comprehensive insurance coverage. Different types of insurance policies provide varying levels of protection, catering to specific business needs.

    General Liability Insurance

    General liability insurance protects businesses against claims of bodily injury, property damage, or personal injury caused by their operations, products, or services. It covers legal defense costs and damages awarded to the injured party.

    Property Insurance

    Property insurance safeguards a business’s physical assets, such as buildings, equipment, inventory, and business records. It covers losses or damages due to fire, theft, vandalism, natural disasters, and other covered perils.

    Workers’ Compensation Insurance

    Workers’ compensation insurance provides coverage for employees who suffer work-related injuries or illnesses. It covers medical expenses, lost wages, and disability benefits, protecting both the employee and the business from financial burdens.

    Comparison of Coverage Options

    The table below compares the key features of general liability, property, and workers’ compensation insurance:

    Coverage Type Coverage Scope Premiums Deductibles
    General Liability Bodily injury, property damage, personal injury Varies based on risk factors Typically low
    Property Physical assets, business records Based on value of property insured Can vary significantly
    Workers’ Compensation Work-related injuries or illnesses Set by state regulations Often not applicable

    When choosing insurance coverage, it’s essential to consider the specific risks and exposures of your business. Consulting with an experienced insurance agent can help you tailor a coverage plan that meets your unique needs and provides comprehensive protection.

    Industry Expertise and Specialization

    Small business insurance agents near me

    When choosing a small business insurance agent, consider their expertise and specialization in specific industries. Agents who have a deep understanding of your industry’s unique risks and needs can provide tailored solutions that protect your business effectively.

    For example, if you own a healthcare practice, an agent specializing in healthcare insurance can guide you through the complexities of medical malpractice coverage, HIPAA compliance, and patient privacy regulations.

    Construction Industry

    • Agents specializing in construction insurance understand the risks associated with construction projects, including property damage, liability, and workers’ compensation.
    • They can help you navigate the complex insurance requirements for different types of construction projects, such as residential, commercial, and infrastructure.

    Retail Industry

    • Agents specializing in retail insurance understand the risks faced by businesses operating in the retail sector, such as theft, property damage, and product liability.
    • They can help you develop a comprehensive insurance program that protects your inventory, equipment, and employees.

    Benefits of Working with an Industry Specialist

    • Customized coverage: Agents with industry expertise can tailor insurance policies to meet the specific risks and needs of your business.
    • Proactive risk management: They can identify potential risks and develop strategies to mitigate them, reducing the likelihood of costly claims.
    • Efficient claims handling: Agents who understand your industry can help you navigate the claims process smoothly and efficiently, ensuring timely settlement.

    Technology and Innovation: Small Business Insurance Agents Near Me

    The small business insurance industry is embracing technology and innovation to improve efficiency, enhance customer service, and reduce costs. Agents are leveraging cutting-edge tools to streamline the quoting and policy management process, providing a seamless experience for their clients.

    Digital Quoting and Policy Management

    Digital quoting platforms enable agents to quickly and accurately generate quotes for small businesses. These platforms integrate with insurance carriers’ systems, allowing agents to access real-time data and provide tailored recommendations. Automated underwriting processes reduce the time and effort required to issue policies, ensuring a faster turnaround time for clients.

    Customer Relationship Management (CRM) Systems, Small business insurance agents near me

    CRM systems help agents manage customer relationships and provide personalized service. These systems store customer data, track interactions, and generate automated reminders for renewals and other important events. By leveraging CRM systems, agents can nurture relationships with their clients and provide proactive support.

    Data Analytics and Artificial Intelligence (AI)

    Data analytics and AI are transforming the insurance industry. Agents are using data to identify trends, predict risks, and develop customized insurance solutions for their clients. AI-powered chatbots and virtual assistants provide 24/7 support, answering customer questions and resolving issues quickly and efficiently.

    Last Point

    Partnering with a small business insurance agent near you provides invaluable peace of mind, allowing you to focus on growing your business while knowing that your assets and operations are protected. Embrace the insights and recommendations in this guide to secure the insurance coverage that empowers your business to succeed.

    Helpful Answers

    How can I find the best small business insurance agent near me?

    Our guide provides a comprehensive list of reputable agents in your area, along with their contact information and service offerings.

    What types of insurance coverage do small businesses need?

    Small businesses typically require general liability, property insurance, and workers’ compensation coverage. Our guide compares the coverage options, premiums, and deductibles offered by different agents.

    How can technology benefit my small business insurance experience?

    Agents are leveraging technology to streamline the quoting and policy management process, enhance customer service, and reduce costs. Our guide explores these advancements and their impact on the industry.

  • Add Money to Chime with Debit Card: A Comprehensive Guide

    Add Money to Chime with Debit Card: A Comprehensive Guide

    Add money to chime with debit card – Discover the seamless process of adding funds to your Chime account using a debit card. From step-by-step instructions to security considerations, this comprehensive guide empowers you to manage your finances with ease.

    With Chime’s user-friendly platform and secure payment gateway, topping up your account has never been more convenient. Explore the various methods, fees, and limits associated with adding funds via debit card, ensuring a smooth and secure financial experience.

    Adding Funds with Debit Card

    Adding funds to your Chime account with a debit card is a convenient and straightforward process. Here’s a step-by-step guide to help you get started:

    Steps to Add Funds

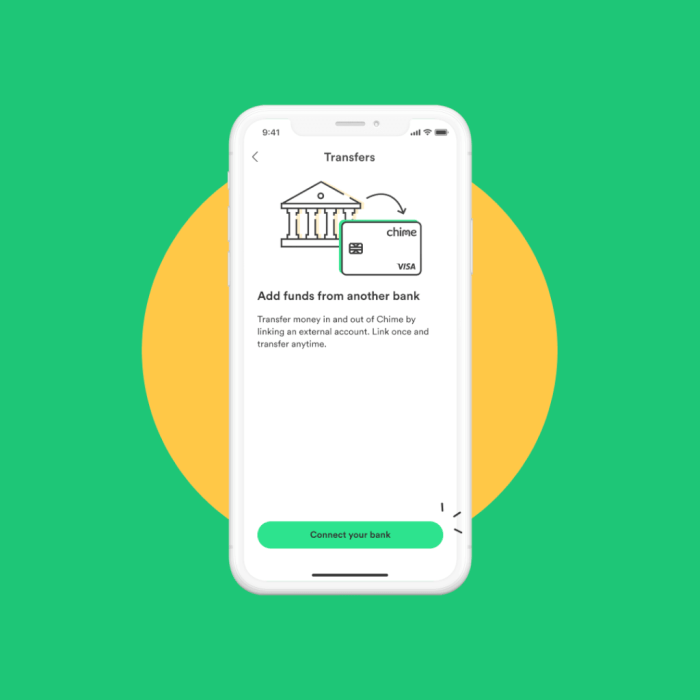
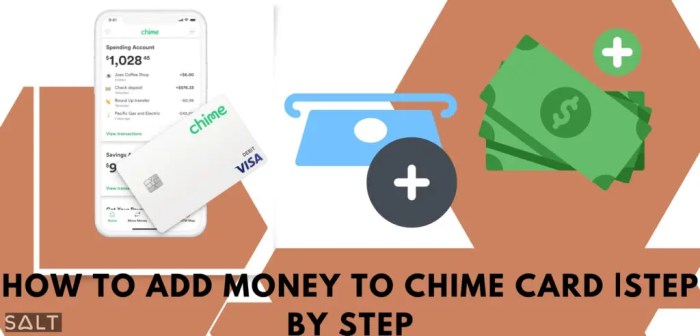
    1. Log in to your Chime account:Visit the Chime website or open the mobile app and enter your login credentials.
    2. Navigate to the “Add Money” page:Once logged in, click on the “Add Money” button located on the homepage.
    3. Select “Debit Card” as the funding source:On the “Add Money” page, choose “Debit Card” as the method to add funds.
    4. Enter the debit card details:Input the card number, expiration date, and CVV code of your debit card.
    5. Enter the amount to add:Specify the amount of money you wish to add to your Chime account.
    6. Review and confirm the transaction:Check the details of the transaction, including the amount and the source of funds, before confirming the transfer.
    7. Complete the transfer:Click on the “Add Money” button to complete the transaction and add the funds to your Chime account.

    Fees and Limits: Add Money To Chime With Debit Card

    Adding funds to your Chime account using a debit card incurs no fees. However, there are certain limits to consider:

    • Daily Limit:The maximum amount you can add to your Chime account using a debit card in a single day is $1,000.
    • Weekly Limit:The maximum amount you can add to your Chime account using a debit card in a week is $2,500.
    • Monthly Limit:The maximum amount you can add to your Chime account using a debit card in a month is $5,000.

    These limits are in place to protect you from fraud and unauthorized access to your funds. If you need to add more than these limits allow, you can contact Chime’s customer support for assistance.

    Security Considerations

    Add money to chime with debit card

    Adding funds to your Chime account using a debit card involves sensitive financial information. Chime has implemented robust security measures to protect your data during transactions:

    Encryption:Chime uses industry-standard encryption protocols to safeguard your personal and financial information during transmission. All data is encrypted, making it unreadable to unauthorized parties.

    Two-Factor Authentication:For added security, Chime may require you to provide a one-time passcode sent to your mobile phone or email before completing a transaction.

    Fraud Monitoring:Chime employs advanced fraud detection systems to monitor transactions for suspicious activity. If any irregularities are detected, you may be contacted to verify the transaction.

    Potential Risks and Precautions

    • Phishing Scams:Be wary of emails or text messages that appear to be from Chime but request sensitive information like your password or debit card details. Chime will never ask for this information via unsecure channels.
    • Public Wi-Fi Networks:Avoid using public Wi-Fi networks when adding funds to your Chime account. These networks can be vulnerable to eavesdropping, exposing your sensitive data.
    • Strong Passwords:Use a strong and unique password for your Chime account. Avoid using easily guessable passwords or sharing them with others.

    Alternative Methods

    Besides using a debit card, Chime offers several alternative methods for adding funds to your account, each with its own advantages and disadvantages.

    Let’s explore these options:

    Direct Deposit

    Direct deposit is a convenient way to have your paycheck or other regular payments automatically deposited into your Chime account. This method is reliable and ensures that funds are added securely without the need for manual transfers.

    Cash Deposit

    Chime allows you to deposit cash at select retail locations, such as Walmart and CVS. This method is convenient for those who prefer to handle cash or do not have access to other funding options. However, it may involve fees and limited availability depending on your location.

    Mobile Check Deposit

    With Chime’s mobile check deposit feature, you can deposit checks remotely using your smartphone. This method is convenient and allows you to add funds without leaving your home. However, it may be subject to processing times and daily deposit limits.

    Customer Support

    Add money to chime with debit card

    Chime offers various channels to reach their customer support team for assistance with adding funds using a debit card.

    You can connect with a representative through the following methods:

    Phone Support

    • Phone Number: 1-844-244-6363
    • Available 24/7

    Email Support, Add money to chime with debit card

    • Email Address: support@chime.com
    • Typically responds within 24 hours

    Online Support

    Final Thoughts

    Chime deposit activation activate fintech becomes valuable

    Whether you’re a seasoned Chime user or a newcomer to its innovative banking services, this guide provides invaluable insights into adding funds with a debit card. Embrace the convenience and security of Chime’s financial ecosystem, empowering you to take control of your finances with confidence.

    Questions and Answers

    How long does it take to add funds with a debit card?

    Funds are typically added to your Chime account instantly upon completion of the transaction.

    Are there any fees for adding funds with a debit card?

    No, there are no fees charged by Chime for adding funds with a debit card.

    What is the maximum amount I can add to my Chime account using a debit card?

    The maximum amount you can add to your Chime account using a debit card is $10,000 per day.

  • Best Rated Whole Life Insurance for Seniors: A Comprehensive Guide

    Best Rated Whole Life Insurance for Seniors: A Comprehensive Guide

    Embark on a journey to discover the best rated whole life insurance for seniors, a financial lifeline that provides peace of mind and enduring protection. As you navigate the complexities of aging, secure your future with a policy tailored to your unique needs, offering comprehensive coverage and exceptional financial strength.

    Our in-depth guide unveils the secrets of whole life insurance, empowering you to make informed decisions. Dive into the nuances of coverage options, premiums, customer service, and policy provisions, ensuring you choose a plan that aligns perfectly with your aspirations.

    Company Rankings and Financial Strength

    Best rated whole life insurance for seniors

    When selecting a whole life insurance policy for seniors, it is crucial to consider the company’s financial strength and rankings. These factors provide insights into the insurer’s ability to meet its obligations and provide long-term financial security for policyholders.

    Top-Rated Whole Life Insurance Companies for Seniors

    The following table compares the top-rated whole life insurance companies for seniors based on financial strength ratings from leading independent agencies:

    Company Financial Strength Rating
    Northwestern Mutual A++ (Superior)
    MassMutual A++ (Superior)
    New York Life A++ (Superior)
    Guardian Life A+ (Excellent)
    Prudential A+ (Excellent)

    Companies with higher financial strength ratings are generally considered more stable and reliable, indicating a lower risk of default or financial distress.

    Coverage and Benefits: Best Rated Whole Life Insurance For Seniors

    Insurance seniors aarp

    Whole life insurance policies provide a range of coverage options and benefits that can meet the specific needs of seniors. These policies offer lifelong protection, with premiums and death benefits remaining constant throughout the policy term. Additionally, whole life insurance policies accumulate cash value, which can be borrowed against or withdrawn for various purposes.

    Some of the unique features and riders that may be beneficial for seniors include:

    Guaranteed Issue Whole Life Insurance

    • Guaranteed issue whole life insurance policies do not require a medical exam, making them accessible to seniors who may have pre-existing health conditions.
    • However, these policies typically have lower death benefits and higher premiums compared to medically underwritten policies.

    Simplified Issue Whole Life Insurance

    • Simplified issue whole life insurance policies require only a few basic health questions and no medical exam.
    • They offer higher death benefits and lower premiums compared to guaranteed issue policies, but still have lower coverage limits than medically underwritten policies.

    Chronic Illness Rider, Best rated whole life insurance for seniors

    • A chronic illness rider provides an accelerated death benefit if the insured is diagnosed with a qualifying chronic illness.
    • This benefit can be used to cover medical expenses, long-term care costs, or other expenses associated with a chronic illness.

    Terminal Illness Rider

    • A terminal illness rider provides an accelerated death benefit if the insured is diagnosed with a terminal illness with a life expectancy of less than 12 months.
    • This benefit can be used to cover end-of-life expenses, such as hospice care, funeral costs, or outstanding debts.

    Waiver of Premium Rider

    • A waiver of premium rider waives the policy premiums if the insured becomes totally disabled.
    • This benefit ensures that the policy remains in force even if the insured is unable to work and pay the premiums.

    Comparison of Coverage Options and Benefits

    Coverage Options and Benefits of Top-Rated Whole Life Insurance Policies
    Policy Death Benefit Cash Value Guaranteed Issue Simplified Issue Chronic Illness Rider Terminal Illness Rider Waiver of Premium Rider
    Policy A Up to $500,000 Accumulates at a fixed rate No Yes Yes Yes Yes
    Policy B Up to $1,000,000 Accumulates at a variable rate No Yes No Yes No
    Policy C Up to $2,000,000 Accumulates at a variable rate Yes No Yes Yes Yes

    Cost and Premiums

    The cost of whole life insurance premiums for seniors is influenced by several factors, including age, health, and the amount of coverage desired. As you age, your premiums will typically increase due to the higher risk of mortality. Similarly, if you have a history of health problems, your premiums may be higher than someone with a clean bill of health.

    The amount of coverage you choose will also impact your premiums, with higher coverage amounts leading to higher premiums.

    To give you a better idea of the costs involved, we’ve compared the premium rates of the top-rated whole life insurance policies for seniors. The table below summarizes the premium costs and payment options for each policy.

    Premium Rates and Payment Options

    Company Premium Rate (Monthly) Payment Options
    AIG $150 Monthly, Quarterly, Semi-Annually, Annually
    Mutual of Omaha $175 Monthly, Quarterly, Semi-Annually, Annually
    Northwestern Mutual $200 Monthly, Quarterly, Semi-Annually, Annually
    Pacific Life $225 Monthly, Quarterly, Semi-Annually, Annually
    Transamerica $250 Monthly, Quarterly, Semi-Annually, Annually

    Customer Service and Reviews

    Best rated whole life insurance for seniors

    Exceptional customer service is paramount in choosing a whole life insurance provider. It ensures that your queries and concerns are addressed promptly and efficiently. Positive policyholder reviews indicate a company’s commitment to customer satisfaction.

    Customer Reviews and Testimonials

    Reputable sources like J.D. Power and Consumer Reports provide valuable insights into customer experiences. These organizations conduct surveys and gather feedback from policyholders, evaluating their satisfaction levels with various aspects of service, such as responsiveness, claim handling, and overall experience.

    Top-Rated Whole Life Insurance Companies: Customer Service Ratings
    Company J.D. Power Rating Consumer Reports Rating
    Northwestern Mutual 880 85
    MassMutual 875 83
    New York Life 870 82

    Policy Details and Provisions

    Whole life insurance policies come with a variety of provisions and terms that determine the coverage, benefits, and costs. Understanding these provisions is crucial for making informed decisions about your policy.

    Whole life insurance policies typically include the following provisions:

    Death Benefit

    The death benefit is the amount of money that will be paid to your beneficiaries upon your death. The death benefit is usually a fixed amount, but it can be increased or decreased over time through policy riders.

    Cash Value

    The cash value is a savings component that grows over time on a tax-deferred basis. You can borrow against the cash value or withdraw it for any reason, but doing so will reduce the death benefit.

    Premiums

    Premiums are the payments you make to keep your policy in force. Premiums are typically fixed for the life of the policy, but they can increase if you add riders or change the coverage amount.

    Policy Options and Riders

    In addition to the basic provisions, whole life insurance policies can also include a variety of policy options and riders. These options and riders can provide additional coverage or benefits, such as:

    • Guaranteed insurability riders: These riders allow you to increase your coverage amount without having to undergo a medical exam.
    • Accidental death and dismemberment riders: These riders provide additional coverage if you die or are dismembered in an accident.
    • Waiver of premium riders: These riders waive your premium payments if you become disabled.

    Table of Policy Details and Provisions

    The following table Artikels the policy details and provisions of the top-rated whole life insurance policies for seniors:

    Company Death Benefit Cash Value Premiums
    Company A Up to $1 million Up to $500,000 Starting at $100 per month
    Company B Up to $2 million Up to $750,000 Starting at $125 per month
    Company C Up to $3 million Up to $1 million Starting at $150 per month

    Closing Summary

    In the twilight of your years, secure your legacy with the best rated whole life insurance for seniors. With a policy that stands the test of time, you can rest assured that your loved ones will be protected and your financial future is in safe hands.

    Embrace the peace of mind that comes with knowing you’ve made a wise investment in your well-being and the well-being of those who matter most.

    FAQ Section

    What factors should I consider when choosing a whole life insurance policy?

    Consider your age, health, lifestyle, financial situation, and long-term goals. A policy with adequate coverage, affordable premiums, and favorable policy provisions is crucial.

    How do I compare different whole life insurance policies?

    Compare coverage options, premiums, financial strength ratings, customer service, and policy provisions. Our guide provides a detailed comparison table to assist you.

    What are the benefits of whole life insurance for seniors?

    Whole life insurance offers lifelong coverage, guaranteed cash value growth, and tax-deferred earnings, providing financial security and peace of mind during your retirement years.

  • Best Women’s Life Insurance: Protection, Peace, and Financial Security

    Best Women’s Life Insurance: Protection, Peace, and Financial Security

    In the realm of financial planning, best women’s life insurance stands as a beacon of protection, providing peace of mind and securing the future for women and their loved ones. Embark on a journey of discovery as we delve into the intricacies of women’s life insurance, empowering you with knowledge to make informed decisions that safeguard your financial well-being.

    From understanding the types of policies available to navigating the factors that influence rates, this comprehensive guide unravels the complexities of women’s life insurance, empowering you to make choices that align with your unique needs and aspirations.

    Best Women’s Life Insurance Providers

    Best women's life insurance

    When it comes to securing financial protection for your loved ones, choosing the right life insurance provider is crucial. For women, there are specific factors to consider to ensure you get the best coverage at the most affordable rates.

    To help you make an informed decision, we’ve compiled a detailed comparison of the top women’s life insurance providers in the market. Our analysis takes into account key factors such as coverage options, premium costs, customer ratings, and financial stability.

    Factors to Consider

    • Financial Stability:Look for providers with strong financial ratings from independent agencies like AM Best and Moody’s.
    • Customer Service:Choose providers with a reputation for excellent customer support, including prompt claims processing and responsive representatives.
    • Claim Payout History:Research the provider’s history of paying out claims quickly and fairly.
    • li> Coverage Options:Ensure the provider offers a range of coverage options to meet your specific needs, including term life, whole life, and universal life.

    • Premium Costs:Compare premiums from different providers to find the most affordable option that meets your coverage requirements.

    Types of Women’s Life Insurance Policies

    Women have unique life insurance needs that differ from men’s due to factors such as life expectancy, income levels, and family responsibilities. Understanding the various types of life insurance policies available can help women make informed decisions to protect their loved ones and financial security.

    Term Life Insurance

    • Pros:Affordable, provides coverage for a specific period (e.g., 10, 20, or 30 years), no cash value accumulation.
    • Cons:Coverage expires after the term, no death benefit if the insured outlives the policy term.
    • Suitable for:Young women with limited financial resources, those seeking temporary coverage for specific needs (e.g., mortgage protection).

    Whole Life Insurance

    • Pros:Provides lifelong coverage, accumulates cash value that can be borrowed against or withdrawn, guaranteed death benefit.
    • Cons:Higher premiums compared to term life, cash value growth is slow, inflexible premium payments.
    • Suitable for:Women with long-term financial goals, those seeking permanent coverage and cash value accumulation.

    Universal Life Insurance

    • Pros:Flexible premiums and death benefit, cash value growth potential, policy loans available.
    • Cons:Higher premiums than term life, cash value growth depends on investment performance, risk of policy lapse if premiums are not paid.
    • Suitable for:Women seeking customizable coverage, those with varying income levels or financial needs.

    Coverage Options for Women’s Life Insurance

    Women’s life insurance coverage options offer flexibility to meet their unique needs and circumstances. From varying death benefit amounts to optional riders and guaranteed insurability, there’s a range of options to choose from.

    Determining the appropriate coverage amount is crucial. Factors to consider include income, expenses, family responsibilities, and future financial goals. A comprehensive assessment of these factors helps ensure adequate protection for your loved ones in the event of your untimely demise.

    Death Benefit Amounts, Best women’s life insurance

    The death benefit is the lump sum paid to your beneficiaries upon your passing. The amount you choose should align with your financial obligations and goals. Consider factors such as mortgage balance, outstanding debts, funeral expenses, and income replacement for your family.
    Riders

    Riders are optional add-ons that enhance your policy’s coverage. Common riders include:

    • Accidental Death Benefit:Provides an additional death benefit in case of accidental death.
    • Waiver of Premium Rider:Exempts you from paying premiums if you become disabled.
    • Child Rider:Extends coverage to your children, providing a death benefit in case of their passing.

    Guaranteed Insurability

    Guaranteed insurability riders allow you to purchase additional coverage in the future without undergoing another medical exam. This is especially beneficial for women who anticipate significant life changes, such as getting married, having children, or purchasing a home.

    Benefits of Women’s Life Insurance

    Life insurance offers numerous benefits tailored specifically to women, providing financial protection, peace of mind, and a secure future for their families.

    Life insurance empowers women to take control of their financial well-being, ensuring their loved ones are financially protected in the event of an unexpected event.

    Financial Protection for Dependents

    Life insurance provides a financial safety net for dependents, ensuring they have the resources to maintain their standard of living in the event of the policyholder’s untimely demise.

    This financial cushion can cover expenses such as mortgage payments, education costs, and childcare, alleviating the financial burden on grieving family members.

    Peace of Mind

    Life insurance brings peace of mind, knowing that your loved ones will be financially secure in your absence.

    It eliminates the worry and uncertainty that often accompany unexpected life events, allowing you to focus on living your life to the fullest.

    Estate Planning

    Life insurance can serve as a valuable estate planning tool, ensuring your assets are distributed according to your wishes.

    The death benefit can be used to pay estate taxes, cover funeral expenses, and provide inheritances for beneficiaries, ensuring your legacy lives on.

    Financial Goals

    Life insurance can contribute to achieving your financial goals, such as retirement planning or saving for your children’s education.

    The cash value component of certain policies grows tax-deferred, providing a potential source of funds for future needs.

    How to Get the Best Women’s Life Insurance Rates

    Insurance womenwhomoney much

    Getting the best life insurance rates as a woman involves understanding the factors that influence your premium and taking steps to improve your health and lifestyle. By following these tips, you can increase your chances of securing affordable and comprehensive coverage.

    Factors Affecting Women’s Life Insurance Rates

    Several factors influence the cost of women’s life insurance, including:

    • -*Age

      As you age, your life expectancy decreases, leading to higher premiums.

    • -*Health

      Your overall health and medical history can impact your rates. Conditions such as obesity, heart disease, and diabetes can increase your risk of mortality and result in higher premiums.

    • -*Lifestyle

      Your lifestyle choices, such as smoking and excessive alcohol consumption, can affect your life expectancy and insurance costs.

    • -*Occupation

      Women in hazardous occupations or with high levels of stress may face higher premiums.

    • -*Family history

      A family history of certain diseases or premature death can influence your insurance rates.

    Improving Your Health and Lifestyle

    To qualify for lower life insurance rates, consider the following health and lifestyle improvements:

    • -*Maintain a healthy weight

      Obesity is a significant risk factor for various health conditions, leading to higher premiums.

    • -*Exercise regularly

      Regular exercise helps maintain a healthy weight, reduces stress, and improves overall well-being.

    • -*Eat a balanced diet

      A nutritious diet rich in fruits, vegetables, and whole grains supports good health and longevity.

    • -*Quit smoking

      Smoking is a major risk factor for heart disease, stroke, and cancer, all of which can increase your life insurance premiums.

    • -*Manage stress

      Chronic stress can have negative effects on your health and increase your risk of developing certain diseases.

    Conclusive Thoughts

    Best women's life insurance

    In conclusion, best women’s life insurance is an invaluable tool that empowers women to protect their families, achieve financial goals, and secure their future. By understanding the intricacies of different policies, coverage options, and rate-influencing factors, you can make informed decisions that safeguard your loved ones and provide peace of mind for years to come.

    FAQs

    What are the key factors to consider when choosing a women’s life insurance policy?

    When selecting a women’s life insurance policy, it’s crucial to evaluate factors such as the type of policy, coverage amount, premium costs, financial stability of the insurer, customer service, and claim payout history.

    How can women determine the appropriate coverage amount for their life insurance policy?

    To determine the appropriate coverage amount, women should consider their income, expenses, family responsibilities, debts, and future financial goals. It’s advisable to consult with a financial advisor to assess individual needs and circumstances.

    What are the benefits of having a women’s life insurance policy?

    Women’s life insurance offers numerous benefits, including financial protection for dependents in the event of the policyholder’s passing, peace of mind knowing that loved ones are financially secure, and the ability to plan for the future by covering end-of-life expenses and estate planning.

  • Discover the Best No-Exam Term Life Insurance: A Guide to Hassle-Free Coverage

    Discover the Best No-Exam Term Life Insurance: A Guide to Hassle-Free Coverage

    In the realm of financial security, best no exam term life insurance emerges as a beacon of simplicity and convenience. Dive into this comprehensive guide, where we unveil the intricacies of this insurance, empowering you to make informed decisions that safeguard your loved ones.

    No-exam term life insurance stands out as a game-changer, eliminating the need for intrusive medical examinations. Its benefits are undeniable, from expedited application processes to hassle-free underwriting. Yet, it’s crucial to weigh these advantages against potential drawbacks, ensuring you make the choice that aligns perfectly with your needs.

    Overview of Best No-Exam Term Life Insurance

    Term life insurance is a type of life insurance that provides coverage for a specific period of time, such as 10, 20, or 30 years. It is designed to provide financial protection for your loved ones in the event of your untimely death.

    No-exam life insurance is a type of term life insurance that does not require you to take a medical exam.

    There are a number of benefits to no-exam term life insurance, including:

    • Convenience:No-exam life insurance is quick and easy to apply for. You can typically complete the application online in a matter of minutes.
    • No medical exam:As the name suggests, no-exam life insurance does not require you to take a medical exam. This can be a major benefit for people who are in poor health or who have a history of medical problems.
    • Affordable:No-exam life insurance is typically more affordable than traditional term life insurance. This is because the insurance company does not have to pay for the cost of a medical exam.

    However, there are also some drawbacks to no-exam term life insurance, including:

    • Lower coverage limits:No-exam life insurance policies typically have lower coverage limits than traditional term life insurance policies.
    • Higher premiums:No-exam life insurance policies typically have higher premiums than traditional term life insurance policies.
    • Limited underwriting:No-exam life insurance policies typically have limited underwriting, which means that the insurance company may not be able to assess your risk as accurately as they would if you took a medical exam.

    Factors to Consider When Choosing a No-Exam Term Life Insurance Policy

    When selecting a no-exam term life insurance policy, several key factors should be carefully evaluated to ensure it meets your specific needs and financial situation. These factors include:

    Understanding Coverage Amounts and Policy Terms: Determine the appropriate coverage amount based on your income, debts, and financial obligations. Consider the policy term, which is the duration for which the coverage will be provided, and choose one that aligns with your financial goals and life stage.

    Comparing Premiums and Policy Features

    Compare premiums from different insurance companies to find the most competitive rates. Examine policy features such as the death benefit, riders (additional coverage options), and exclusions (situations where coverage may not apply). Choose a policy that offers the best combination of coverage, features, and affordability.

    Evaluating the Financial Stability of Insurance Companies

    Research the financial stability of insurance companies by checking their ratings from independent agencies such as AM Best, Standard & Poor’s, and Moody’s. A higher rating indicates a stronger financial position and lower risk of the company being unable to fulfill its obligations.

    Comparison of Top No-Exam Term Life Insurance Providers

    Life insurance exam companies history definitive update guide

    Comparing different no-exam term life insurance providers is crucial to find the best policy for your needs. Here’s a table summarizing key features of top providers:

    Provider Coverage Limits Policy Terms Premium Rates
    Haven Life Up to $1 million 10, 15, 20, or 30 years Competitive rates, especially for younger and healthier applicants
    Ladder Up to $8 million 10, 15, 20, 25, or 30 years Higher premiums but offers underwriting without a medical exam
    Bestow Up to $1.5 million 10, 15, 20, 25, or 30 years Simplified underwriting process, but higher premiums for smokers
    Fabric Up to $5 million 10, 15, 20, or 30 years Offers customizable coverage and riders, but may have higher premiums
    Fidelity Life Up to $1 million 10, 15, 20, or 30 years Lower premiums for older applicants, but limited coverage amounts

    Strengths and Weaknesses

    Each provider has its strengths and weaknesses:

    • Haven Life:Low premiums, easy application process, but lower coverage limits.
    • Ladder:High coverage limits, underwriting without a medical exam, but higher premiums.
    • Bestow:Simplified underwriting, no medical exam required, but higher premiums for smokers.
    • Fabric:Customizable coverage, additional riders, but potentially higher premiums.
    • Fidelity Life:Lower premiums for older applicants, but limited coverage amounts.

    Application Process for No-Exam Term Life Insurance

    Best no exam term life insurance

    Applying for no-exam term life insurance is designed to be simple and straightforward. Unlike traditional life insurance, which requires a medical exam, no-exam life insurance eliminates the need for invasive procedures and lengthy medical questionnaires.

    Simplified Application Process

    The application process typically involves completing an online form or speaking with an insurance agent over the phone. The form typically asks for basic information such as your name, age, health history, and lifestyle habits. You may also be asked about your occupation and financial situation.

    Underwriting Process, Best no exam term life insurance

    Once you submit your application, the insurance company will review your information to determine your risk level. This process is known as underwriting. For no-exam life insurance, underwriting relies on the information you provide in your application, as well as data from external sources such as medical records and prescription history.

    Tips for Maximizing Approval Chances

    To increase your chances of approval for no-exam term life insurance, consider the following tips:

    • Be honest and accurate when completing your application.
    • Disclose any pre-existing health conditions or lifestyle habits that may affect your risk level.
    • Consider your occupation and financial situation. High-risk occupations or unstable financial situations may impact your approval.
    • Shop around and compare quotes from multiple insurance providers to find the best coverage for your needs.

    Tips for Getting the Best No-Exam Term Life Insurance Policy: Best No Exam Term Life Insurance

    Securing the most favorable no-exam term life insurance policy requires a proactive approach. By implementing these strategies, you can maximize your coverage and minimize your financial burden.

    First and foremost, it’s essential to shop around and compare quotes from multiple providers. Utilizing online comparison tools and consulting with independent insurance agents can help you identify the most competitive rates that meet your specific needs and budget.

    Importance of Reading and Understanding Policy Details

    Before signing on the dotted line, thoroughly review and comprehend the terms and conditions of your policy. Pay close attention to the coverage amount, premium payments, and any exclusions or limitations that may affect your eligibility for benefits.

    Don’t hesitate to ask questions and seek clarification from the insurance provider to ensure you fully understand the scope of your coverage and any potential implications.

    Negotiating with Insurance Providers

    Negotiating with insurance providers can often yield favorable results. Consider bundling your no-exam term life insurance policy with other insurance products, such as homeowners or auto insurance, to potentially qualify for discounts.

    Additionally, maintaining a healthy lifestyle, including regular exercise and a balanced diet, can positively impact your insurance premiums. By demonstrating a commitment to your well-being, you may be eligible for preferred rates.

    Epilogue

    Best no exam term life insurance

    As you embark on the journey of securing the best no-exam term life insurance policy, remember to prioritize coverage amounts that align with your financial responsibilities and life goals. Embrace the power of comparison, evaluating premiums, policy features, and the financial stability of insurance providers.

    By following the expert tips Artikeld in this guide, you’ll navigate the application process with ease, maximizing your chances of approval.

    May this guide serve as your trusted companion, empowering you to secure peace of mind and financial protection for your loved ones. The world of no-exam term life insurance awaits your exploration, where convenience and security intertwine seamlessly.

    Frequently Asked Questions

    What sets no-exam term life insurance apart from traditional life insurance?

    No-exam term life insurance streamlines the application process by eliminating the need for medical examinations, providing a faster and more convenient path to coverage.

    Are there any drawbacks to consider with no-exam term life insurance?

    While no-exam term life insurance offers convenience, it may come with higher premiums compared to traditional life insurance due to the absence of medical information.

    How can I find the best no-exam term life insurance policy for my needs?

    Thoroughly compare coverage amounts, policy terms, and premium rates offered by different providers. Seek guidance from insurance professionals to ensure you make an informed decision.

  • Uncover the Secrets to Affordable Life Insurance: A Guide to Cheap Life Insurance Quotes

    Uncover the Secrets to Affordable Life Insurance: A Guide to Cheap Life Insurance Quotes

    Embark on a journey to discover the world of cheap life insurance quotes, where affordability meets peace of mind. Dive into a comprehensive exploration of life insurance options, empowering you to make informed decisions that safeguard your loved ones without breaking the bank.

    From comparing quotes across multiple insurers to understanding the nuances of life insurance riders, this guide will equip you with the knowledge to navigate the complexities of life insurance and secure the best coverage for your unique needs.

    Affordable Life Insurance Coverage

    Cheap life insurance quotes

    In today’s uncertain world, securing your family’s financial future is paramount. Affordable life insurance provides peace of mind, knowing that your loved ones will be protected in the event of your untimely demise. With a wide range of options available, finding cheap life insurance that meets your specific needs is within reach.

    The cost of life insurance premiums is influenced by several factors, including your age, health, lifestyle habits, and the amount of coverage you need. Understanding these factors can help you make informed decisions and potentially reduce your costs.

    Factors Influencing Life Insurance Premiums

    • Age:As you age, your risk of health issues increases, leading to higher premiums.
    • Health:Your overall health and medical history play a significant role in determining your premiums. Pre-existing conditions can increase your risk and, consequently, your costs.
    • Lifestyle Habits:Engaging in risky behaviors, such as smoking or excessive alcohol consumption, can raise your premiums.
    • Amount of Coverage:The higher the coverage amount you need, the more you’ll pay in premiums.

    Tips to Reduce Life Insurance Costs

    • Compare Quotes:Obtain quotes from multiple insurers to compare rates and find the best deal.
    • Consider Term Life Insurance:Term life insurance provides coverage for a specific period, often at a lower cost than whole life insurance.
    • Improve Your Health:Maintaining a healthy lifestyle, including regular exercise and a balanced diet, can improve your health rating and reduce premiums.
    • Quit Smoking:Smoking significantly increases your risk of health problems, leading to higher premiums. Quitting can save you money on insurance.
    • Increase Your Deductible:Choosing a higher deductible on your policy can lower your premiums.

    By understanding the factors that influence life insurance premiums and implementing cost-saving strategies, you can secure affordable coverage that meets your needs without breaking the bank.

    Comparing Quotes from Multiple Insurers

    Securing affordable life insurance coverage is a crucial step in safeguarding your loved ones’ financial future. To ensure you make an informed decision, it’s essential to compare quotes from various insurance providers. This comprehensive guide will empower you with the knowledge and strategies to gather, compare, and select the most suitable life insurance policy that meets your unique needs and budget.

    Gathering Life Insurance Quotes

    The first step in comparing quotes is to gather them from multiple insurance providers. You can do this by:

    • Online Quote Comparison Tools:Utilize online platforms that allow you to compare quotes from several insurers simultaneously.
    • Insurance Brokers:Consult with an independent insurance broker who represents multiple insurers and can provide unbiased advice.
    • Direct Contact:Reach out to individual insurance companies directly to request quotes.

    Comparing Life Insurance Quotes

    Once you have gathered quotes from different insurers, it’s time to compare them carefully. Consider the following factors:

    • Coverage Amount:Ensure the coverage amount is sufficient to meet your family’s financial needs in the event of your untimely demise.
    • Premiums:Compare the monthly or annual premiums charged by each insurer. Remember, lower premiums don’t always indicate a better deal.
    • Policy Terms:Understand the policy terms, including the length of the coverage, the waiting period, and any exclusions or limitations.
    • Riders and Benefits:Consider additional riders or benefits, such as accidental death benefits or disability income riders, that may enhance the coverage.
    • Financial Strength of the Insurer:Research the financial stability and reputation of each insurance provider to ensure they have the ability to fulfill their obligations.

    Advantages and Disadvantages of Different Insurers

    Each insurance provider offers unique advantages and disadvantages. Some insurers may specialize in certain types of life insurance policies, while others may offer competitive premiums or comprehensive coverage options. By understanding the strengths and weaknesses of different insurers, you can make an informed decision that aligns with your specific requirements.

    Understanding Life Insurance Riders and Benefits

    Seniors affordable

    Life insurance riders are optional add-ons that can enhance the coverage of your policy and provide additional benefits. They offer a range of options to tailor your policy to your specific needs and circumstances.

    Types of Life Insurance Riders

    There are several types of life insurance riders available, each providing unique benefits. Some common riders include:

    • Accidental Death Benefit:Provides an additional payout if the insured person dies as a result of an accident.
    • Critical Illness Coverage:Provides a lump sum payment if the insured person is diagnosed with a covered critical illness, such as cancer or heart disease.
    • Waiver of Premium:Exempts the insured person from paying premiums if they become disabled and unable to work.
    • Return of Premium:Refunds a portion or all of the premiums paid if the insured person outlives the policy term.
    • Child Rider:Provides coverage for the insured person’s children.

    Benefits and Drawbacks of Riders

    Adding riders to your life insurance policy can provide valuable benefits. However, it is important to consider the potential drawbacks as well:

    Benefits:

    • Increased coverage and financial protection
    • Tailored coverage to meet specific needs
    • Peace of mind knowing that loved ones are protected

    Drawbacks:

    • Increased premiums
    • Potential restrictions or limitations on coverage
    • May not be necessary for all individuals

    Table of Common Riders and Impact on Premiums

    The following table Artikels some of the common riders offered by insurers and their impact on premiums:

    Rider Benefit Impact on Premium
    Accidental Death Benefit Additional payout for accidental death Increases premium by 10-20%
    Critical Illness Coverage Lump sum payment for covered critical illness Increases premium by 15-25%
    Waiver of Premium Exemption from premium payments if disabled Increases premium by 5-10%
    Return of Premium Refund of premiums if insured outlives policy term Increases premium by 10-15%
    Child Rider Coverage for insured person’s children Increases premium by 5-10% per child

    Applying for Cheap Life Insurance

    Cheap life insurance quotes

    Obtaining affordable life insurance is crucial for safeguarding your loved ones’ financial well-being. Applying for cheap life insurance involves a straightforward process, but meticulous preparation can enhance your chances of securing favorable rates.

    Required Information and Documentation

    • Personal information: Name, address, date of birth, Social Security number
    • Health history: Medical conditions, medications, surgeries, lifestyle habits
    • Financial information: Income, assets, debts
    • Beneficiary information: Name, relationship, percentage of coverage
    • Proof of insurability: Medical exam, doctor’s report, prescription records

    Steps to Apply

    1. Gather information:Collect the necessary information and documentation Artikeld above.
    2. Compare quotes:Obtain quotes from multiple insurers to find the most affordable options.
    3. Choose a policy:Select the policy that best meets your needs and budget.
    4. Complete the application:Provide accurate and complete information on the application form.
    5. Submit the application:Send the completed application along with supporting documentation to the insurer.
    6. Underwriting process:The insurer will review your application and determine your risk level.
    7. Approval and policy issuance:If approved, the insurer will issue your life insurance policy.

Tips for Securing Affordable Rates

  • Maintain a healthy lifestyle: Non-smokers and individuals with good health habits typically qualify for lower rates.
  • Compare multiple quotes: Shopping around can help you find the most competitive rates.
  • Consider a smaller policy: A lower death benefit amount can result in lower premiums.
  • Increase your coverage gradually: Starting with a smaller policy and gradually increasing coverage as your financial situation improves can help keep costs manageable.

Additional Considerations for Cheap Life Insurance

To secure cheap life insurance quotes, it’s crucial to consider factors that influence premium costs. Medical exams and health screenings play a significant role in assessing your health profile, impacting the insurer’s risk assessment. Age, lifestyle habits, and family history also come into play.

Medical Exams and Health Screenings

Life insurance companies often require medical exams and health screenings to evaluate your overall health. These tests provide valuable insights into your medical history, current health status, and potential risk factors. Based on the results, insurers determine your health classification, which significantly influences your premium rates.

Age

Age is a primary factor in life insurance pricing. Younger individuals typically qualify for lower premiums due to their lower perceived risk of mortality. As you age, the risk of health issues increases, leading to higher premium costs.

Lifestyle Habits, Cheap life insurance quotes

Your lifestyle choices can have a profound impact on your life insurance rates. Smoking, excessive alcohol consumption, and poor dietary habits can increase your health risks, resulting in higher premiums. Conversely, maintaining a healthy lifestyle, including regular exercise and a balanced diet, can qualify you for lower rates.

Family History

Your family’s medical history can also influence your life insurance premiums. If you have a strong family history of chronic diseases, such as heart disease or cancer, you may face higher premium costs. This is because insurers may perceive you as having a higher risk of developing similar conditions.

Maintaining a Healthy Lifestyle

To qualify for cheap life insurance rates, it’s essential to maintain a healthy lifestyle. Regular exercise, a balanced diet, and avoiding harmful habits like smoking and excessive alcohol consumption can significantly improve your health and reduce your risk factors. This, in turn, can lead to lower life insurance premiums.

Final Wrap-Up: Cheap Life Insurance Quotes

As you delve into the realm of cheap life insurance quotes, remember that affordability is not just about finding the lowest premium. It’s about finding the right balance between coverage, cost, and your personal circumstances. By understanding the factors that influence premiums, comparing quotes diligently, and exploring the benefits of riders, you can unlock the secrets to securing cheap life insurance that truly protects your financial future.

Answers to Common Questions

What factors influence the cost of life insurance premiums?

Age, health, lifestyle habits, occupation, and family history all play a role in determining life insurance premiums.

How can I reduce life insurance costs without compromising coverage?

Consider term life insurance over whole life insurance, opt for higher deductibles, and improve your overall health and lifestyle.

What are the advantages of adding riders to a life insurance policy?

Riders can provide additional coverage for specific events, such as accidental death, critical illness, or disability, enhancing the protection provided by your policy.

  • Best Life Insurance for Physicians: Comprehensive Protection for Your Financial Future

    Best Life Insurance for Physicians: Comprehensive Protection for Your Financial Future

    Best life insurance for physicians – Navigating the complexities of life insurance can be daunting, but for physicians, it’s an essential step towards securing their financial well-being. This comprehensive guide will delve into the unique risks and needs of physicians, providing insights into the best life insurance policies and strategies to optimize coverage.

    As a physician, your profession demands a level of financial protection that safeguards your income, supports your family, and ensures your estate planning goals are met. Life insurance serves as a cornerstone of this protection, providing peace of mind and financial stability in the face of unforeseen events.

    Overview of Life Insurance for Physicians

    Physicians face unique risks and responsibilities that necessitate tailored life insurance coverage. The demanding nature of their profession, coupled with substantial earning potential and family obligations, underscores the critical need for adequate financial protection.

    Life insurance provides a safety net for physicians and their families, ensuring income protection in the event of premature death, financial support for loved ones, and assistance with estate planning. By securing appropriate coverage, physicians can safeguard their financial well-being and provide peace of mind for their families.

    Income Protection

    Life insurance serves as a financial cushion, replacing the physician’s income if they are unable to work due to illness, disability, or death. This ensures that their family can maintain their standard of living and meet ongoing expenses, such as mortgage payments, education costs, and daily necessities.

    Family Support

    Life insurance provides financial support for the physician’s family in the event of their untimely death. The death benefit can cover funeral expenses, outstanding debts, and ongoing living expenses, ensuring that the family’s financial stability is not compromised.

    Estate Planning

    Life insurance can be an integral part of a physician’s estate plan. It can provide liquidity to cover estate taxes and administration costs, ensuring a smooth transfer of assets to heirs. Additionally, life insurance can be used to fund charitable donations or establish trusts for future generations.

    Factors to Consider When Choosing Life Insurance

    Insurance lgbtq doctor nhs

    Physicians face unique financial considerations when choosing life insurance. Understanding the factors that influence the selection of a suitable policy is crucial for ensuring adequate protection for their loved ones and financial well-being.

    Key factors to consider include:

    Age and Health

    • Age plays a significant role in determining life insurance premiums, with younger applicants typically paying lower rates.
    • Health status can also impact premiums, with individuals with pre-existing conditions facing higher costs.

    Income and Family Size

    • Physicians with higher incomes may need larger life insurance policies to cover potential income loss for their families.
    • The number of dependents (spouse, children) also influences the amount of coverage required.

    Financial Goals

    • Life insurance can serve multiple financial goals, such as providing for end-of-life expenses, paying off debts, or funding education.
    • Determining the specific financial needs will help determine the appropriate policy amount.

    Types of Life Insurance Policies

    There are three main types of life insurance policies available:

    • Term Life Insurance:Provides coverage for a specific period (e.g., 10, 20, 30 years) at a fixed premium. Once the term expires, the policy can be renewed at a higher premium or allowed to lapse.
    • Whole Life Insurance:Provides coverage for the entire life of the insured person and accumulates a cash value component that can be borrowed against or withdrawn.
    • Universal Life Insurance:A hybrid policy that combines features of term and whole life insurance, offering flexibility in premium payments and coverage amounts.

    Choosing the right type of life insurance depends on individual circumstances and financial goals. Term life insurance is generally more affordable, while whole life insurance provides additional benefits but comes with higher premiums.

    Top Life Insurance Providers for Physicians

    Best life insurance for physicians

    Choosing the right life insurance provider is crucial for physicians. Here’s a comparison of the top providers, their policy offerings, premiums, and customer service:

    Policy Offerings

    • Policy Types:Term life, whole life, universal life, variable life
    • Riders:Disability income, critical illness, accidental death and dismemberment
    • Tailored Policies:Policies designed specifically for physicians, such as high death benefit options and coverage for medical malpractice

    Premiums

    • Factors Affecting Premiums:Age, health, lifestyle, occupation, and policy type
    • Discounts:Available for non-smokers, healthy lifestyles, and professional affiliations
    • Quote Comparison:Get quotes from multiple providers to compare premiums

    Customer Service

    • Online Tools:Policy management, claims filing, and financial planning resources
    • Dedicated Agents:Specialized in working with physicians
    • Claims Processing:Efficient and timely claims settlement

    Provider Comparison Table

    Provider Policy Offerings Premiums Customer Service
    Provider A Term, whole, universal, variable Competitive Online tools, dedicated agents, fast claims processing
    Provider B Term, whole, universal Industry average Online tools, dedicated agents, responsive customer support
    Provider C Term, whole, universal, variable Slightly higher Online tools, dedicated agents, personalized financial planning

    Specific Policy Examples

    • High Death Benefit Policy:Provides a substantial death benefit for physicians with high income or financial obligations
    • Medical Malpractice Coverage:Covers legal expenses and damages in case of medical malpractice lawsuits
    • Disability Income Protection:Provides income replacement if a physician is unable to work due to illness or injury

    Additional Considerations for Physicians

    Best life insurance for physicians

    Physicians have unique financial needs and face specific risks that require tailored insurance coverage. In addition to life insurance, it’s essential for physicians to consider other insurance policies to ensure comprehensive financial protection.

    Disability Insurance

    Disability insurance provides income replacement if you become unable to work due to illness or injury. For physicians, this is crucial as their income relies heavily on their ability to practice medicine. Disability insurance ensures that financial obligations can still be met even when earning capacity is compromised.

    Health Insurance, Best life insurance for physicians

    Health insurance is essential for covering medical expenses and safeguarding financial stability in the event of illness or injury. Physicians often have access to employer-sponsored health insurance, but it’s crucial to carefully review the coverage and consider supplemental plans if necessary.

    Long-Term Care Insurance

    Long-term care insurance provides coverage for expenses associated with extended care needs, such as assisted living or nursing home stays. As physicians age, the likelihood of requiring long-term care increases. This insurance can help protect against the financial burden of these expenses, ensuring financial security during retirement.

    Strategies for Optimizing Life Insurance Coverage

    Physicians have unique life insurance needs that require careful consideration and optimization strategies. By implementing these strategies, physicians can ensure they have adequate coverage to protect their loved ones and financial future.

    One key strategy is to maximize coverage limits. Physicians should determine the appropriate amount of coverage based on their income, debts, family size, and future financial goals. A financial advisor can assist in calculating the optimal coverage amount.

    Utilizing Riders

    Riders are optional add-ons that can enhance the coverage of a life insurance policy. Some common riders for physicians include:

    • Accidental Death Benefit:Provides additional coverage in case of accidental death.
    • Disability Income Rider:Provides a monthly income if the physician becomes disabled and unable to work.
    • Long-Term Care Rider:Covers the costs of long-term care expenses, such as nursing home or assisted living.

    Exploring Group Policies

    Physicians may also consider exploring group life insurance policies offered through their employer or professional organizations. Group policies often provide lower premiums and simplified underwriting processes.

    Role of Financial Advisors

    Financial advisors play a crucial role in helping physicians make informed decisions about life insurance. They can:

    • Assess the physician’s financial situation and coverage needs.
    • Recommend appropriate life insurance products and coverage amounts.
    • Explain the benefits and limitations of different riders.
    • Monitor the policy and make adjustments as the physician’s circumstances change.

    Final Conclusion: Best Life Insurance For Physicians

    In conclusion, choosing the best life insurance for physicians requires careful consideration of factors such as age, health, income, family size, and financial goals. By understanding the different types of life insurance policies and exploring the offerings of top providers, physicians can tailor a coverage plan that meets their specific needs.

    Remember, life insurance is not just a financial transaction; it’s an investment in your future and the well-being of your loved ones. By optimizing your coverage and seeking guidance from financial advisors, you can ensure that your life insurance policy provides the protection you need, when you need it most.

    Query Resolution

    What is the best type of life insurance for physicians?

    The best type of life insurance for physicians depends on their individual needs and circumstances. Term life insurance provides affordable coverage for a specific period, while whole life insurance offers lifelong coverage and a cash value component.

    How much life insurance do physicians need?

    Physicians should aim for life insurance coverage that is 10-15 times their annual income. This amount can vary based on factors such as family size, financial obligations, and retirement goals.

    What are some additional insurance considerations for physicians?

    In addition to life insurance, physicians should consider disability insurance, health insurance, and long-term care insurance. These policies provide complementary protection against income loss, medical expenses, and the costs of long-term care.

  • Affordable Life Insurance Without Medical Exams: A Convenient and Accessible Option

    Affordable Life Insurance Without Medical Exams: A Convenient and Accessible Option

    Cheap term life insurance no medical exam – As cheap term life insurance without medical exams takes center stage, it beckons individuals seeking financial protection with its unparalleled convenience and accessibility. This innovative insurance solution eliminates the traditional medical exam requirement, making it an ideal choice for those who prioritize speed, privacy, or have health concerns.

    The absence of a medical exam streamlines the application process, allowing you to secure coverage quickly and efficiently. It also provides peace of mind for individuals who may be hesitant to undergo medical examinations due to health conditions or personal preferences.

    Benefits of Cheap Term Life Insurance without Medical Exam

    Cheap term life insurance no medical exam

    Term life insurance without a medical exam offers several advantages, making it an attractive option for individuals seeking affordable and convenient coverage.

    Accessibility and Convenience

    No-exam policies eliminate the need for invasive medical examinations, which can be time-consuming and uncomfortable. This makes it a hassle-free process, especially for those with busy schedules or health concerns.

    Eligibility and Coverage

    No-exam term life insurance is particularly beneficial for individuals who may not qualify for traditional policies due to pre-existing conditions or other health factors. It provides coverage for a wide range of causes of death, ensuring peace of mind for policyholders.

    Affordability and Simplicity, Cheap term life insurance no medical exam

    By eliminating the cost of medical exams, no-exam term life insurance policies are generally more affordable than traditional policies. The application process is also simplified, requiring only basic information about your health and lifestyle.

    Factors to Consider When Choosing a Policy

    Selecting a cheap term life insurance policy without a medical exam requires careful consideration of several key factors that can impact your premiums and coverage. Understanding these factors will help you make an informed decision that aligns with your needs and financial situation.

    The primary factors to consider include your age, health, and lifestyle habits. These elements play a significant role in determining your risk profile and, consequently, the cost of your insurance policy.

    Age

    Age is a crucial factor in term life insurance premiums. As you age, your risk of developing health conditions increases, leading to higher premiums. Younger individuals typically pay lower premiums than older individuals because they have a lower risk of experiencing health issues.

    Health

    Your overall health status is another critical factor that insurance companies assess when determining your premiums. Individuals with pre-existing medical conditions or a history of chronic illnesses may face higher premiums. On the other hand, those in good health and with a clean medical history can qualify for lower premiums.

    Lifestyle

    Your lifestyle habits, such as smoking, excessive alcohol consumption, and risky hobbies, can also impact your premiums. Insurance companies view these factors as indicators of potential health risks and may adjust premiums accordingly. Individuals who engage in healthier lifestyles and avoid risky behaviors can secure lower premiums.

    Tips for Comparing Policies

    • Obtain quotes from multiple insurance providers to compare premiums and coverage options.
    • Review the policy details thoroughly, including the coverage amount, term length, and any exclusions or limitations.
    • Consider your budget and financial goals to determine the coverage amount and premium that aligns with your needs.
    • Seek advice from an insurance agent or financial advisor to gain a comprehensive understanding of your options and make an informed decision.

    Understanding Coverage and Exclusions

    Exam

    Understanding the coverage and exclusions of a cheap term life insurance policy without a medical exam is crucial to ensure you have the right protection for your needs. These policies typically provide coverage for death due to natural causes, accidents, and other specified events.

    However, there may be certain exclusions and limitations that apply.

    Types of Coverage

    * Death benefit: The primary coverage provided by term life insurance, which pays out a lump sum to your beneficiaries upon your death.

    Accidental death benefit

    Additional coverage that provides a higher death benefit if your death results from an accident.

    Dismemberment benefit

    Coverage that provides a benefit if you lose a limb or eyesight due to an accident.

    Common Exclusions

    * Pre-existing conditions: Most policies exclude coverage for deaths resulting from pre-existing medical conditions that you had before the policy was issued.

    Suicide

    Many policies exclude coverage for deaths resulting from suicide within the first two years of the policy.

    High-risk activities

    Certain policies may exclude coverage for deaths resulting from high-risk activities, such as skydiving or bungee jumping.

    Criminal activity

    Policies typically exclude coverage for deaths resulting from criminal activity.

    Importance of Understanding Terms and Conditions

    It is essential to thoroughly read and understand the terms and conditions of your policy before purchasing. This will help you avoid any surprises down the road and ensure you are fully aware of the coverage and exclusions that apply.

    Application Process and Approval: Cheap Term Life Insurance No Medical Exam

    Cheap term life insurance no medical exam

    Applying for term life insurance without a medical exam is a straightforward process designed for convenience. The application typically consists of a few simple steps, making it accessible to individuals seeking coverage quickly and easily.

    Underwriting for policies without a medical exam involves assessing the applicant’s health and lifestyle based on information provided in the application. Insurers use sophisticated algorithms and data analysis to evaluate factors such as age, gender, occupation, and medical history disclosed by the applicant.

    Approval Process

    The approval process typically involves reviewing the applicant’s information and making a decision within a short period. In many cases, approval can be granted within a matter of hours or days, providing peace of mind and timely coverage to the applicant.

    Reputable Providers and Policy Options

    Navigating the world of cheap term life insurance without a medical exam can be daunting, but it doesn’t have to be. Numerous reputable providers offer affordable policies tailored to your specific needs. This section will introduce you to some of the leading providers and help you understand their policy options.

    When selecting a provider, it’s crucial to consider their financial stability, customer service, and policy terms. Research different companies, read reviews, and compare their offerings to make an informed decision.

    List of Reputable Providers

    • Banner Life Insurance Company:Known for its competitive rates and customizable policies.
    • Ethos Life Insurance:Offers instant coverage and simplified underwriting.
    • Haven Life Insurance Agency:Provides affordable coverage with no hidden fees.
    • Legal & General America:Established provider with a wide range of policy options.
    • Prudential Financial:Offers comprehensive coverage with various riders and add-ons.

    Policy Options Comparison

    Provider Coverage Amount Premiums Benefits
    Banner Life $100,000

    $10,000,000

    Starting at $15/month Guaranteed coverage, flexible payment options
    Ethos Life $10,000

    $1,000,000

    Starting at $7/month Instant approval, no medical exam required
    Haven Life $25,000

    $1,000,000

    Starting at $12/month Simplified underwriting, no medical exam required
    Legal & General America $50,000

    $10,000,000

    Starting at $18/month Flexible coverage terms, variety of riders
    Prudential Financial $100,000

    $10,000,000

    Starting at $20/month Comprehensive coverage, accidental death benefit

    Choosing the Right Provider and Policy

    Choosing the right provider and policy depends on your individual circumstances and financial goals. Consider the following factors:

    • Coverage amount:Determine the amount of coverage you need to protect your loved ones financially.
    • Premiums:Compare premiums from different providers to find the most affordable option.
    • Benefits:Review the benefits offered by each policy, such as guaranteed coverage, flexible payment options, or additional riders.
    • Customer service:Choose a provider with a reputation for excellent customer support.

    Conclusive Thoughts

    In conclusion, cheap term life insurance without a medical exam offers a valuable alternative for individuals seeking affordable and accessible life insurance coverage. By eliminating the medical exam requirement, this insurance solution empowers individuals to protect their loved ones’ financial well-being with ease and convenience.

    FAQ Guide

    Who can benefit from cheap term life insurance without a medical exam?

    Individuals who prioritize convenience, value privacy, or have health concerns that may impact traditional medical exams can greatly benefit from this insurance option.

    How does the underwriting process work without a medical exam?

    Insurance companies typically assess your health and lifestyle factors through a simplified application process that includes questions about your medical history, occupation, and lifestyle habits.

    Are there any limitations or exclusions in cheap term life insurance without a medical exam?

    While these policies generally offer comprehensive coverage, it’s essential to carefully review the policy terms and conditions to understand any potential exclusions or limitations that may apply.