Blog

  • Best Online Term Insurance: A Comprehensive Guide to Affordable Protection

    Best Online Term Insurance: A Comprehensive Guide to Affordable Protection

    In the realm of financial security, best online term insurance stands as a beacon of protection, offering a lifeline of peace of mind in the face of life’s uncertainties. With its unparalleled convenience, tailored coverage, and competitive premiums, online term insurance has revolutionized the way we safeguard our loved ones and ensure their well-being.

    From understanding the intricacies of term insurance to navigating the complexities of choosing the right provider, this comprehensive guide will illuminate the path to finding the best online term insurance that meets your unique needs and budget.

    Overview of Best Online Term Insurance

    Term insurance is a type of life insurance that provides coverage for a specific period, such as 10, 20, or 30 years. If the insured person dies during the term, the beneficiaries will receive a death benefit. Term insurance is typically less expensive than other types of life insurance, such as whole life insurance, because it does not have a cash value component.

    Online term insurance has become increasingly popular in recent years. This is because it is convenient, affordable, and easy to compare quotes from different insurers. However, there are also some disadvantages to purchasing term insurance online, such as the lack of personal interaction with an agent and the potential for fraud.

    Advantages of Purchasing Term Insurance Online

    • Convenience: You can purchase term insurance online from the comfort of your own home.
    • Affordability: Online term insurance is typically less expensive than term insurance purchased through an agent.
    • Easy to compare quotes: You can easily compare quotes from different insurers online.
    • No need for a medical exam: Some online insurers offer term insurance without requiring a medical exam.

    Disadvantages of Purchasing Term Insurance Online

    • Lack of personal interaction: You will not have the opportunity to meet with an agent in person when you purchase term insurance online.
    • Potential for fraud: There is a potential for fraud when you purchase term insurance online, as you are not dealing with an agent face-to-face.
    • Limited coverage options: Online term insurance providers may not offer as many coverage options as traditional insurers.
    • May not be suitable for everyone: Online term insurance may not be suitable for everyone, such as those with complex financial needs or those who are not comfortable purchasing insurance online.

    Factors to Consider When Choosing an Online Term Insurance Provider

    Best online term insurance

    Selecting the right online term insurance provider is crucial for securing financial protection for your loved ones. Several key factors must be considered to ensure you make an informed decision that meets your specific needs.

    Financial Stability

    The financial stability of an insurance provider is paramount. Look for companies with a strong track record of paying claims and a high financial strength rating from reputable agencies like AM Best or Standard & Poor’s. This rating indicates the insurer’s ability to meet its financial obligations, ensuring that your beneficiaries will receive the promised death benefit.

    Customer Service

    Excellent customer service is essential for a smooth and hassle-free experience. Choose providers with a responsive and knowledgeable support team available through multiple channels, such as phone, email, and online chat. Read reviews from other policyholders to gauge the provider’s customer service quality.

    Policy Options

    Consider the range of policy options offered by the provider. This includes coverage amounts, policy terms, and riders. Ensure that the provider offers options that align with your financial goals and risk tolerance. Some providers may offer additional benefits, such as accelerated death benefits or guaranteed insurability options, which can enhance your coverage.

    Underwriting and Medical Exams

    Underwriting is the process by which an insurance company assesses your risk and determines your premium. Some providers use simplified underwriting, which involves answering a few health questions without requiring a medical exam. Others may require a full medical exam to assess your health and lifestyle factors more accurately.

    Understand the underwriting process and medical exam requirements of each provider to choose one that suits your circumstances.

    Top-Rated Online Term Insurance Providers

    When choosing an online term insurance provider, it’s important to consider factors such as coverage options, premiums, customer service, and financial strength. To help you make an informed decision, we’ve compiled a table comparing the top-rated online term insurance providers.

    Coverage Options

    The coverage options offered by online term insurance providers vary widely. Some providers offer basic coverage that includes death benefits only, while others offer more comprehensive coverage that includes additional benefits such as disability income protection and long-term care coverage.

    Premiums

    The premiums you pay for online term insurance will depend on a number of factors, including your age, health, and the amount of coverage you purchase. It’s important to compare quotes from multiple providers to find the best rate.

    Customer Service

    The quality of customer service you receive from an online term insurance provider is important. You want to make sure that you can easily get in touch with a customer service representative if you have any questions or need to file a claim.

    Financial Strength

    The financial strength of an online term insurance provider is important because it indicates the provider’s ability to pay claims. You want to make sure that you choose a provider that has a strong financial track record.

    Table of Top-Rated Online Term Insurance Providers

    Provider Coverage Options Premiums Customer Ratings
    Bestow Death benefits only Low Excellent
    Haven Life Death benefits only Low Excellent
    Ladder Death benefits, disability income protection, long-term care coverage Moderate Good
    Lemonade Death benefits, critical illness coverage, accidental death coverage Low Good
    Policygenius Death benefits, disability income protection, long-term care coverage Moderate Good

    Strengths and Weaknesses of Each Provider

    Bestow:Strengths: Low premiums, excellent customer service. Weaknesses: Limited coverage options.

    Haven Life:Strengths: Low premiums, excellent customer service. Weaknesses: Limited coverage options.

    Ladder:Strengths: Comprehensive coverage options, moderate premiums. Weaknesses: Customer service can be slow at times.

    Lemonade:Strengths: Low premiums, innovative coverage options. Weaknesses: Customer service can be slow at times.

    Policygenius:Strengths: Comprehensive coverage options, moderate premiums. Weaknesses: Customer service can be slow at times.

    Tips for Getting the Best Term Insurance Quotes

    Obtaining the most competitive term insurance quotes online requires careful consideration and a strategic approach. Here are some valuable tips to guide you in securing the best possible coverage at an affordable price:

    Importance of Comparing Quotes:

    • Never settle for the first quote you receive. It’s crucial to compare quotes from multiple providers to ensure you’re getting the best deal. Different insurers may offer varying premiums based on their underwriting criteria and risk assessment models.
    • Use online comparison tools or work with an independent insurance agent who represents multiple carriers. This allows you to quickly and easily compare coverage options and premiums from various providers.

    Factors Influencing Premiums:

    The cost of your term insurance premium is largely determined by three key factors:

    • Age:Generally, younger individuals pay lower premiums due to a lower perceived risk of mortality. As you age, the likelihood of health issues increases, leading to higher premiums.
    • Health:Your overall health and medical history play a significant role in determining your premium. Insurers assess your health through medical exams, blood tests, and questionnaires. A healthy lifestyle, including regular exercise and a balanced diet, can positively impact your insurability and premium rates.

    • Lifestyle:Certain risky behaviors, such as smoking or participating in dangerous hobbies, can increase your premium. Insurers view these activities as potential risk factors that may affect your life expectancy.

    Online Term Insurance Policy Features

    Best online term insurance

    Online term insurance policies offer various features and benefits that enhance their value. Understanding these features is crucial for making informed decisions about your coverage.

    Coverage Amounts

    Coverage amounts refer to the maximum payout your beneficiaries will receive upon your death. Selecting the right coverage amount is essential to ensure your loved ones are financially protected. Consider your income, expenses, debts, and future financial goals when determining the appropriate coverage.

    Policy Terms

    Policy terms specify the duration of your coverage. Common policy terms range from 10 to 30 years. Choose a policy term that aligns with your financial obligations and life stage. Longer policy terms provide more extended coverage but may come with higher premiums.

    Riders

    Riders are optional add-ons that can enhance your policy’s coverage. Common riders include:

    • Accidental Death Benefit: Provides an additional payout if your death results from an accident.
    • Waiver of Premium Rider: Waives your premium payments if you become disabled and unable to work.
    • Guaranteed Insurability Rider: Allows you to purchase additional coverage without undergoing a medical exam at predetermined intervals.

    Accelerated Death Benefits

    Accelerated death benefits allow you to access a portion of your death benefit while you are still living if you are diagnosed with a terminal illness or experience a critical health event. This benefit provides financial assistance for medical expenses or other needs during a difficult time.

    Living Benefits, Best online term insurance

    Living benefits provide access to a portion of your death benefit while you are still alive. These benefits can be used for long-term care expenses, chronic illnesses, or other qualifying events. Living benefits offer flexibility and financial security in the face of unexpected life circumstances.

    Concluding Remarks: Best Online Term Insurance

    Term insurance plan max life plus plans thus protected concept based community family

    As we conclude our exploration of best online term insurance, it is evident that this innovative solution has transformed the landscape of financial planning. By embracing the advantages of online insurance, you empower yourself to make informed decisions, optimize coverage, and secure the future of those who matter most.

    Remember, the best term insurance is the one that aligns seamlessly with your financial goals and provides unwavering protection against life’s unforeseen events.

    Answers to Common Questions

    What is the difference between term insurance and whole life insurance?

    Term insurance provides coverage for a specific period, while whole life insurance offers lifelong coverage and has a cash value component.

    How do I choose the right term insurance amount?

    Consider your income, expenses, debts, and family situation to determine the appropriate coverage amount.

    What factors affect term insurance premiums?

    Age, health, lifestyle, and coverage amount are key factors that influence premiums.

  • Best No Medical Exam Life Insurance Policies: A Comprehensive Guide

    Dive into the realm of life insurance policies that offer peace of mind without the hassle of medical exams. Best no medical exam life insurance policies are gaining traction, and this comprehensive guide will illuminate the benefits, drawbacks, and nuances of these policies, empowering you to make informed decisions about protecting your loved ones.

    Uncover the secrets of no medical exam life insurance, tailored to meet the unique needs of seniors, young adults, individuals with pre-existing conditions, those in high-risk occupations, and those seeking term life insurance. Explore the underwriting processes, compare coverage amounts, premiums, and riders, and gain insights into the factors that influence policy approvals.

    Best No Medical Exam Life Insurance Policies for Seniors

    Best no medical exam life insurance policies

    No medical exam life insurance policies can be a good option for seniors who are in good health but don’t want to go through the hassle of a medical exam. These policies are typically easier to qualify for than traditional life insurance policies, and they can provide valuable financial protection for your loved ones in the event of your death.

    However, there are some drawbacks to no medical exam life insurance policies. One is that they typically have lower coverage limits than traditional policies. Another is that they may be more expensive than traditional policies, especially for seniors.

    Benefits of No Medical Exam Life Insurance Policies for Seniors

    • No medical exam required
    • Easier to qualify for than traditional life insurance policies
    • Can provide valuable financial protection for your loved ones

    Drawbacks of No Medical Exam Life Insurance Policies for Seniors, Best no medical exam life insurance policies

    • Lower coverage limits than traditional policies
    • May be more expensive than traditional policies

    Table Comparing Different No Medical Exam Life Insurance Policies for Seniors

    Company Coverage Amount Premium Riders
    Mutual of Omaha Up to $250,000 $20 per month Accidental death benefit, waiver of premium
    Prudential Up to $100,000 $30 per month Accidental death benefit, waiver of premium, long-term care rider
    Transamerica Up to $50,000 $40 per month Accidental death benefit, waiver of premium, child rider

    Underwriting Process for No Medical Exam Life Insurance Policies for Seniors

    The underwriting process for no medical exam life insurance policies for seniors is typically less stringent than the underwriting process for traditional life insurance policies. This is because insurers are taking on more risk when they issue a policy without a medical exam.

    As a result, seniors may be asked to provide additional information, such as their medical history and lifestyle habits.

    Best No Medical Exam Life Insurance Policies for Young Adults

    Exam

    No medical exam life insurance policies are an increasingly popular option for young adults. These policies offer a number of benefits, including:

    • No medical exam required
    • Quick and easy to apply for
    • Affordable premiums
    • Coverage amounts up to $1 million

    However, there are also some drawbacks to no medical exam life insurance policies. These include:

    • Coverage amounts may be lower than with a traditional life insurance policy
    • Premiums may be higher than with a traditional life insurance policy
    • There may be more restrictions on coverage

    Overall, no medical exam life insurance policies can be a good option for young adults who are looking for an affordable and easy way to get life insurance coverage. However, it is important to weigh the benefits and drawbacks of these policies before making a decision.

    Underwriting Process for No Medical Exam Life Insurance Policies for Young Adults

    The underwriting process for no medical exam life insurance policies for young adults is typically less stringent than the underwriting process for traditional life insurance policies. This is because no medical exam is required, so the insurance company cannot use your medical history to assess your risk.

    Instead, the insurance company will use other factors to assess your risk, such as your age, occupation, and lifestyle.

    If you are a young adult who is in good health and has a low-risk lifestyle, you may be able to qualify for a no medical exam life insurance policy with a low premium. However, if you have any health conditions or engage in high-risk activities, you may be required to pay a higher premium or you may not be able to qualify for coverage.

    Best No Medical Exam Life Insurance Policies for People with Pre-Existing Conditions

    No medical exam life insurance policies can be a good option for people with pre-existing conditions who need life insurance coverage but cannot qualify for a traditional policy. These policies do not require a medical exam, so you can get coverage without having to worry about your health history.

    However, there are some important things to keep in mind before you purchase a no medical exam life insurance policy.

    Benefits of No Medical Exam Life Insurance Policies for People with Pre-Existing Conditions

    There are several benefits to purchasing a no medical exam life insurance policy if you have a pre-existing condition. First, these policies can provide you with peace of mind knowing that your loved ones will be financially protected if you pass away.

    Second, no medical exam life insurance policies can be more affordable than traditional policies, as they do not require the insurer to pay for a medical exam.

    Drawbacks of No Medical Exam Life Insurance Policies for People with Pre-Existing Conditions

    There are also some drawbacks to purchasing a no medical exam life insurance policy if you have a pre-existing condition. First, these policies typically have lower coverage amounts than traditional policies. Second, the premiums for no medical exam life insurance policies can be higher than the premiums for traditional policies.

    Third, no medical exam life insurance policies may not cover all pre-existing conditions. It is important to read the policy carefully before you purchase it to make sure that your condition is covered.

    Underwriting Process for No Medical Exam Life Insurance Policies for People with Pre-Existing Conditions

    The underwriting process for no medical exam life insurance policies for people with pre-existing conditions is different from the underwriting process for traditional policies. When you apply for a no medical exam life insurance policy, the insurer will ask you a series of questions about your health history.

    The insurer will use this information to determine your risk of dying and set your premium. If you have a pre-existing condition, the insurer may require you to provide additional information, such as a doctor’s note or medical records. The insurer may also order a medical exam to confirm your health status.

    Best No Medical Exam Life Insurance Policies for High-Risk Occupations

    Best no medical exam life insurance policies

    Individuals working in high-risk occupations face unique challenges when it comes to obtaining life insurance. Traditional policies require extensive medical examinations, which can be invasive and time-consuming. No medical exam life insurance policies offer a convenient alternative for high-risk workers, providing coverage without the need for intrusive medical tests.

    Benefits and Drawbacks of No Medical Exam Life Insurance for High-Risk Occupations

    Benefits:*

    -*Convenience

    No medical exams required, making the application process quick and hassle-free.

    • -*Speed

      Policies can be approved within days, providing peace of mind and financial protection.

    • -*Accessibility

      Available to individuals with pre-existing conditions or risky occupations.

    Drawbacks:*

    -*Limited Coverage

    Coverage amounts may be lower than traditional policies due to the lack of medical underwriting.

    • -*Higher Premiums

      Premiums can be higher than traditional policies to compensate for the increased risk.

    • -*Riders

      Some riders, such as accidental death or dismemberment, may not be available with no medical exam policies.

    Comparison of No Medical Exam Life Insurance Policies for High-Risk Occupations

    The following table compares different no medical exam life insurance policies for high-risk occupations:| Company | Coverage Amount | Premiums | Riders ||—|—|—|—||

    *Haven Life | Up to $1 million | Starting at $15/month | Accidental death and dismemberment |

    |

    *Ladder | Up to $3 million | Starting at $20/month | Critical illness, child riders |

    |

    *Fabric | Up to $5 million | Starting at $25/month | Disability, hospital indemnity |

    Underwriting Process for No Medical Exam Life Insurance for High-Risk Occupations

    The underwriting process for no medical exam life insurance for high-risk occupations involves:*

    -*Occupation Review

    Insurers will assess the applicant’s occupation and determine the associated risk level.

    • -*Financial History

      Applicants will need to provide financial information to demonstrate their ability to pay premiums.

    • -*Lifestyle Factors

      Insurers may consider factors such as smoking, alcohol consumption, and overall health habits.

    Based on these factors, insurers will determine the coverage amount and premium for the policy. It’s important to disclose all relevant information accurately to ensure a fair underwriting decision.

    Best No Medical Exam Life Insurance Policies for Term Life Insurance

    Term life insurance policies provide coverage for a specific period of time, such as 10, 20, or 30 years. No medical exam life insurance policies for term life insurance offer the convenience of obtaining coverage without undergoing a medical examination.

    Benefits of No Medical Exam Life Insurance Policies for Term Life Insurance

    • Convenience: No medical exam required, making the application process faster and easier.
    • Speed: Policies can be issued quickly, often within a few days.
    • Accessibility: Available to individuals who may not qualify for traditional life insurance due to health conditions or high-risk occupations.

    Drawbacks of No Medical Exam Life Insurance Policies for Term Life Insurance

    • Limited Coverage Amounts: Coverage amounts may be lower than traditional life insurance policies.
    • Higher Premiums: Premiums may be higher to offset the risk associated with not having a medical exam.
    • Limited Rider Options: Riders, such as disability or accidental death benefits, may not be available.

    Comparison of No Medical Exam Life Insurance Policies for Term Life Insurance

    Provider Coverage Amount Premiums Riders
    Haven Life Up to $1 million Starting at $15 per month Accidental death benefit
    Ladder Life Up to $3 million Starting at $20 per month None
    Fidelity Life Up to $2 million Starting at $25 per month Disability waiver of premium

    Underwriting Process for No Medical Exam Life Insurance Policies for Term Life Insurance

    The underwriting process for no medical exam life insurance policies for term life insurance typically involves the following steps:

    • Application:Complete an online or paper application, providing basic information about your health and lifestyle.
    • Phone Interview:A representative from the insurance company may contact you to ask additional questions about your health and medical history.
    • Motor Vehicle Report:The insurance company may obtain a motor vehicle report to assess your driving history and risk factors.
    • Prescription Check:The insurance company may check prescription databases to review your medication history.
    • Social Media Review:Some insurance companies may review your social media accounts to assess your lifestyle and health-related information.

    Conclusion

    In the tapestry of life, securing the future well-being of your loved ones is paramount. Best no medical exam life insurance policies offer a path to safeguard their financial stability in the face of life’s uncertainties. By navigating the complexities of these policies with the guidance provided in this comprehensive guide, you can make informed choices that will provide peace of mind and lasting protection.

    Essential Questionnaire

    Can I get a no medical exam life insurance policy if I have a pre-existing condition?

    Yes, there are no medical exam life insurance policies available for individuals with pre-existing conditions. However, the underwriting process may be more stringent, and coverage amounts and premiums may be affected.

    Are no medical exam life insurance policies more expensive than traditional policies?

    In general, no medical exam life insurance policies tend to have higher premiums compared to traditional policies that require medical exams. This is because the insurer assumes a higher risk by not conducting a medical examination.

    What is the maximum coverage amount I can get with a no medical exam life insurance policy?

    Coverage amounts for no medical exam life insurance policies vary depending on the insurer and the applicant’s age, health, and other factors. Typically, coverage amounts range from $10,000 to $500,000.

  • Business Liability Insurance: A Safety Net for Small Business Owners

    Business liability insurance for small business – In the dynamic world of small businesses, safeguarding your enterprise against unforeseen liabilities is paramount. Enter business liability insurance, a crucial shield that empowers entrepreneurs to navigate the complexities of risk and liability with confidence.

    From protecting against costly lawsuits to safeguarding reputation and customer trust, business liability insurance serves as a cornerstone of a comprehensive risk management strategy. Dive into this detailed guide to understand the types of coverage available, assess your insurance needs, and find the right provider to ensure your small business thrives in the face of potential liabilities.

    Liability Coverage for Business Owners

    Business liability insurance for small business

    Liability insurance is a crucial protection for small businesses, shielding them from financial losses resulting from claims of negligence or harm caused to others. Various types of liability coverage are available, each tailored to specific risks faced by different businesses.

    General Liability Insurance

    General liability insurance provides broad coverage for a wide range of common business risks, including:

    • Bodily injury or property damage to customers, clients, or third parties
    • Advertising injuries, such as libel, slander, or copyright infringement
    • Personal and advertising injuries, such as defamation or invasion of privacy

    Professional Liability Insurance

    Professional liability insurance, also known as errors and omissions (E&O) insurance, protects businesses that provide professional services from claims of negligence, mistakes, or omissions in their work. This coverage is particularly important for professionals such as accountants, lawyers, consultants, and healthcare providers.

    Product Liability Insurance

    Product liability insurance protects businesses from claims that their products have caused injury or damage to consumers. This coverage is essential for businesses that manufacture, distribute, or sell products.

    Benefits of Business Liability Insurance

    Business liability insurance is a crucial safeguard for small businesses, providing financial protection against a wide range of risks that can threaten their stability and reputation.

    Protection against Lawsuits

    Liability insurance acts as a financial buffer against lawsuits filed by customers, employees, or third parties who suffer injuries or property damage due to the business’s operations or negligence. It covers legal expenses, settlements, and judgments, preventing the business from bearing the full financial burden of these claims.

    Property Damage Coverage

    Liability insurance also covers property damage caused by the business’s activities or negligence. This includes damage to customer property, rented premises, or equipment owned by the business. By mitigating the financial impact of property damage, liability insurance helps businesses avoid costly repairs or replacements.

    Lost Income Protection, Business liability insurance for small business

    In the event of a covered incident that forces the business to close temporarily, liability insurance can provide compensation for lost income. This coverage ensures that the business can continue to pay its bills, retain employees, and recover from the financial setbacks caused by the incident.

    Reputation and Customer Trust

    Beyond financial protection, liability insurance also helps businesses maintain their reputation and customer trust. By demonstrating that the business is insured and prepared to handle unforeseen events, it instills confidence in customers and partners, who are more likely to engage with a business that prioritizes safety and responsibility.

    Determining Insurance Needs

    Business liability insurance for small business

    Assessing your liability risks and determining the appropriate level of coverage is crucial for small business owners. Understanding your industry, business size, and potential exposure to claims will guide you in making informed decisions.

    Factors to consider when determining insurance needs include:

    Industry

    • Different industries have varying liability risks. For example, a construction company faces higher risks compared to an office-based consulting firm.
    • Consider the specific hazards associated with your industry and the potential for accidents or incidents.

    Business Size

    • Larger businesses typically have more employees, customers, and assets, which increases their exposure to claims.
    • Smaller businesses may have lower risks, but still need to consider potential liabilities.

    Potential Exposure to Claims

    • Evaluate the likelihood of facing lawsuits or claims related to your business activities.
    • Consider factors such as the number of customers you serve, the nature of your products or services, and your business location.

    Finding the Right Insurance Provider

    Liability unpredictable

    Selecting the appropriate insurance provider is crucial for small businesses. There are several types of providers available:

    • Captive insurers:These are insurance companies owned by a specific industry or group of businesses, providing coverage tailored to their unique needs.
    • Commercial insurance companies:These are traditional insurance providers that offer a wide range of coverage options to businesses of all sizes.
    • Brokers:These are independent agents who represent multiple insurance companies and can assist businesses in finding the best coverage for their needs.

    When selecting an insurance provider, consider the following factors:

    • Financial stability:Ensure the provider has a strong financial track record and can fulfill its obligations in the event of a claim.
    • Coverage options:Review the provider’s coverage options to ensure they align with your business’s specific needs and risks.
    • Customer service:Consider the provider’s reputation for responsiveness, claims handling, and overall customer support.

    Managing Liability Risks

    Minimizing liability risks is crucial for small businesses. By implementing comprehensive risk management strategies, businesses can protect themselves from potential financial and reputational damage.

    Proactive measures, such as establishing clear safety protocols and conducting regular risk assessments, help identify and mitigate potential hazards. Maintaining accurate and up-to-date documentation, including employee training records and incident reports, provides a strong foundation for defense in case of claims.

    Insurance as a Risk Management Tool

    Liability insurance is an essential component of a comprehensive risk management plan. It provides financial protection against legal claims and expenses arising from accidents, injuries, or property damage. By transferring the risk to an insurance provider, businesses can mitigate the financial burden associated with liability.

    Choosing the right insurance policy requires careful consideration of coverage limits, deductibles, and exclusions. Businesses should work with an experienced insurance agent to determine the appropriate level of coverage based on their specific risks and financial situation.

    Ultimate Conclusion: Business Liability Insurance For Small Business

    As you embark on the journey of entrepreneurship, remember that business liability insurance is not merely an expense but an investment in the longevity and resilience of your enterprise. By proactively managing your liability risks, you create a solid foundation for growth, innovation, and unwavering customer trust.

    Embrace the power of business liability insurance and unlock the full potential of your small business.

    Q&A

    What are the different types of liability coverage available for small businesses?

    Small businesses can choose from various liability coverage options, including general liability, professional liability, product liability, and cyber liability insurance.

    How can business liability insurance benefit my small business?

    Business liability insurance provides financial protection against lawsuits, property damage, lost income, and reputational damage, allowing you to focus on growing your business with peace of mind.

    How do I determine the right level of liability insurance for my business?

    To determine the appropriate coverage, assess your industry, business size, potential exposure to claims, and financial situation.

    What factors should I consider when choosing an insurance provider?

    When selecting an insurance provider, evaluate their financial stability, coverage options, customer service, and industry expertise.

  • Effortless Ways to Load Money on Your Chime Card: A Comprehensive Guide

    Effortless Ways to Load Money on Your Chime Card: A Comprehensive Guide

    Load money on chime card – Loading money on your Chime card has never been easier! Dive into our comprehensive guide to discover a plethora of methods, from direct deposits and cash deposits to mobile check deposits and alternative options. Whether you’re receiving your paycheck or adding funds for everyday expenses, we’ve got you covered.

    From the convenience of your home to the security of cash deposits, our in-depth exploration provides clear instructions, helpful tips, and insightful troubleshooting advice. Get ready to streamline your financial management and enjoy the seamless experience of loading money on your Chime card.

    Load Money on Chime Card

    Loading money onto your Chime card is convenient and can be done in several ways. One of the most common methods is through direct deposit.

    Setting Up Direct Deposit

    To set up direct deposit with Chime, you’ll need to provide your employer or payroll department with the following information:

    • Your Chime account number
    • Chime’s routing number (044000029)
    • Your name and address

    Once you’ve provided this information, your employer will be able to send your paycheck directly to your Chime card.

    Benefits of Direct Deposit

    There are several benefits to using direct deposit with Chime, including:

    • Convenience:Direct deposit is a convenient way to get your paycheck without having to go to the bank or wait for a paper check to arrive in the mail.
    • Security:Direct deposit is a more secure way to receive your paycheck than cash or paper checks, as it eliminates the risk of theft or loss.
    • Timeliness:Direct deposit ensures that you’ll receive your paycheck on time, even if you’re out of town or unable to get to the bank.

    Limitations of Direct Deposit

    There are also a few potential limitations to using direct deposit with Chime, including:

    • Fees:Some employers may charge a fee for direct deposit. However, Chime does not charge any fees for direct deposit.
    • Availability:Direct deposit may not be available to all employees. Some employers may only offer paper checks.
    • Access to funds:If you need to access your funds immediately, direct deposit may not be the best option, as it can take up to two business days for the funds to become available in your account.

    Load Money on Chime Card

    Chime offers multiple convenient options for making cash deposits onto your Chime card, empowering you to manage your finances with ease and flexibility. Explore the various methods available to find the one that best suits your needs.

    Cash Deposits, Load money on chime card

    Depositing cash onto your Chime card is a straightforward process that can be completed through various channels, ensuring your convenience and peace of mind.

    Green Dot Locations

    Green Dot locations, conveniently located across the United States, provide a reliable and accessible option for making cash deposits onto your Chime card. Simply visit a participating Green Dot location, present your Chime card, and deposit the desired amount in cash.

    • Wide network of Green Dot locations for easy access
    • Fast and efficient deposit process

    Participating Retailers

    In addition to Green Dot locations, Chime has partnered with select retailers to offer cash deposit services. Visit a participating retailer, such as Walmart or CVS, and inquire about their cash deposit options.

    • Convenience of making deposits at familiar retail locations
    • Extended hours of operation for added flexibility

    It’s important to note that cash deposits may incur a small fee, which varies depending on the deposit amount and the method used. Additionally, there may be limits or restrictions on the amount of cash that can be deposited within a certain period.

    To ensure the security of your cash deposits, Chime has implemented robust security measures. These measures include encryption of sensitive information, fraud monitoring systems, and collaboration with trusted partners to safeguard your funds.

    Load Money on Chime Card

    Mobile Check Deposits

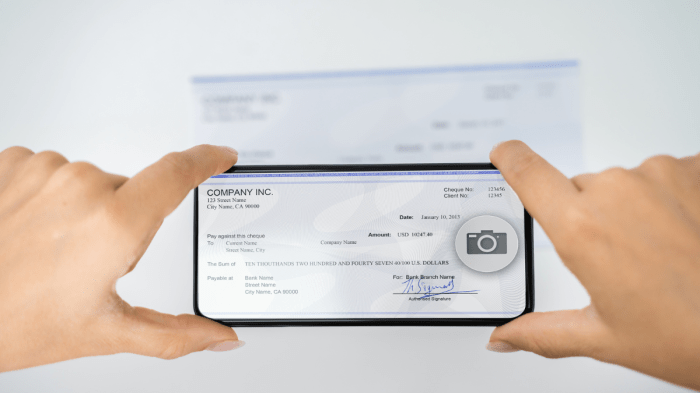
    Deposit checks conveniently using the Chime mobile app. Here’s a detailed guide:

    Requirements:

    • Clear and well-lit image of the front and back of the check.
    • Endorsement on the back of the check: Sign your name exactly as it appears on the front, and write “For Mobile Deposit Only at Chime.”

    Steps:

    1. Open the Chime app and tap “Move Money.”
    2. Select “Deposit a Check.”
    3. Follow the on-screen instructions to capture images of the check.
    4. Review and confirm the deposit details.
    5. Submit the deposit.

    Processing Time:

    Deposits are typically processed within 1-2 business days, but may take longer for large or irregular checks.

    Hold Periods:

    Chime may place a hold on mobile check deposits for up to 10 business days to verify the check and protect against fraud.

    Load Money on Chime Card

    Apart from direct deposits and mobile check deposits, there are alternative methods to load money onto a Chime card. These methods include ACH transfers and prepaid cards.

    ACH Transfers

    ACH (Automated Clearing House) transfers allow you to transfer funds electronically from your bank account to your Chime card. This method is typically free or incurs a small fee, depending on your bank. Processing times can vary, but typically take 1-3 business days.

    Advantages:

    • Convenient and secure way to transfer funds
    • Typically free or low-cost

    Disadvantages:

    • Can take longer to process than other methods
    • May not be available for all banks

    Prepaid Cards

    Prepaid cards can be purchased at retail stores or online, and then loaded with funds. You can then use the prepaid card to add money to your Chime card.

    Advantages:

    • Convenient and widely available
    • Can be used to load cash onto your Chime card

    Disadvantages:

    • May incur fees for purchasing and loading the prepaid card
    • Can be less secure than other methods

    Security Considerations

    When using alternative methods to load money onto your Chime card, it’s important to take security precautions. Only use trusted websites or retail stores to purchase prepaid cards, and avoid sharing your Chime card number or PIN with anyone.

    Load Money on Chime Card: Troubleshooting

    Chime debit

    If you encounter difficulties loading money onto your Chime card, consider the following troubleshooting tips:

    Direct Deposits

    • Verify that the account and routing numbers provided to your employer or benefits provider are correct.
    • Check if the direct deposit has been processed by your employer or benefits provider.
    • Contact your employer or benefits provider if the deposit is delayed or not received within the expected timeframe.

    Cash Deposits, Load money on chime card

    • Ensure you’re using a participating retailer, such as CVS Pharmacy, Walmart, or Walgreens.
    • Confirm the cash deposit limit for your Chime account and the retailer.
    • Review the retailer’s fees associated with cash deposits.

    Mobile Check Deposits

    • Check if your Chime account is eligible for mobile check deposits.
    • Ensure you’re using the Chime mobile app and following the instructions provided.
    • Verify that the check is endorsed correctly and the amount is clearly visible.

    Customer Support

    If you continue to experience issues, reach out to Chime’s customer support team for assistance. They are available through:

    • Live chat: Access live chat support via the Chime mobile app or website.
    • Phone: Call Chime’s customer support line at 1-844-244-6363.
    • Email: Send an email to support@chime.com.

    Closing Summary

    Load money on chime card

    In the realm of financial flexibility, Chime empowers you with a myriad of options to load money onto your card. Whether you prefer the ease of direct deposits, the accessibility of cash deposits, or the convenience of mobile check deposits, there’s a method tailored to your needs.

    Embrace the simplicity and efficiency of Chime’s money-loading solutions, and unlock a world of financial freedom.

    FAQ Resource: Load Money On Chime Card

    Can I load money onto my Chime card at any ATM?

    No, Chime cards are not compatible with all ATMs. You can load cash onto your Chime card at Green Dot locations or participating retailers.

    Is there a fee for loading money onto my Chime card?

    Cash deposits at Green Dot locations may incur a fee. Other methods, such as direct deposit and mobile check deposit, are typically free.

    How long does it take for a mobile check deposit to be processed?

    Mobile check deposits are usually processed within 1-2 business days, but the time frame may vary depending on the amount and your bank’s policies.

  • Secure Your Business: Essential Insurance Coverage for Entrepreneurs

    Secure Your Business: Essential Insurance Coverage for Entrepreneurs

    In today’s dynamic business landscape, safeguarding your enterprise with comprehensive insurance is not merely an option but a necessity. Need insurance for my business becomes a resounding call for entrepreneurs seeking financial protection, risk mitigation, and peace of mind. This guide will delve into the types of insurance coverage available, the benefits they offer, and the steps involved in obtaining and comparing policies.

    Understanding the intricacies of business insurance is crucial for every business owner. From protecting against financial losses to ensuring the well-being of employees, insurance serves as a vital safety net for your entrepreneurial journey.

    Business Insurance Types

    Importance insurance business life policy any suitable picking cover hoffman info

    Business insurance is a vital part of protecting your business from financial losses. There are many different types of business insurance available, each designed to cover a specific type of risk. It’s important to understand the different types of insurance available so that you can choose the right coverage for your business.

    Some of the most common types of business insurance include:

    • Property insuranceprotects your business’s physical assets, such as your building, equipment, and inventory.
    • Liability insuranceprotects your business from claims of negligence or wrongdoing.
    • Workers’ compensation insuranceprovides benefits to employees who are injured or become ill on the job.
    • Business interruption insuranceprovides coverage for lost income and expenses if your business is forced to close due to a covered event, such as a fire or natural disaster.

    • Cyber liability insuranceprotects your business from claims related to data breaches or cyber attacks.

    The type of insurance you need will depend on the specific risks your business faces. It’s important to work with an insurance agent to assess your risks and determine the right coverage for your business.

    Factors to Consider When Choosing Business Insurance

    When choosing business insurance, there are several factors to consider, including:

    • The size of your business: The larger your business, the more risk you face. You’ll need to purchase more insurance to protect your business from financial losses.
    • The type of business you operate: Some businesses are more risky than others. For example, a construction company faces more risk than a retail store.

      You’ll need to purchase insurance that is specific to the risks your business faces.

    • Your financial situation: You need to make sure you can afford the insurance you purchase. Don’t over-insure your business, but don’t under-insure either.
    • Your insurance history: If you have a good insurance history, you may be able to get a discount on your insurance premiums.
    It’s important to compare quotes from several different insurance companies before you purchase business insurance. This will help you find the best coverage at the best price.

    Benefits of Business Insurance

    Need insurance for my business

    Business insurance provides comprehensive financial protection against various risks and uncertainties that businesses may encounter during their operations. It safeguards businesses from potential financial losses and ensures their long-term stability.

    Risk Mitigation and Asset Protection

    Business insurance acts as a safety net, mitigating potential risks that could disrupt business operations and result in significant financial losses. By transferring the financial burden of unexpected events to the insurance company, businesses can safeguard their assets, such as property, equipment, and inventory, from damage or destruction.

    Legal Liability Protection

    Insurance policies can provide coverage against legal liabilities arising from claims of negligence, bodily injury, or property damage caused by the business or its employees. This protection ensures that businesses can continue operating without facing catastrophic financial consequences in the event of lawsuits or legal disputes.

    Peace of Mind and Business Continuity, Need insurance for my business

    Adequate insurance coverage provides peace of mind to business owners, allowing them to focus on growing their businesses without the constant worry of potential financial setbacks. It also ensures that businesses can recover quickly from unexpected events, minimizing disruptions and maintaining business continuity.

    Potential Consequences of Inadequate Insurance

    Failing to secure adequate insurance coverage can have severe consequences for businesses. In the absence of insurance, businesses may have to bear the full financial burden of unforeseen events, leading to financial distress, asset loss, and even business closure.

    Insurance Policy Comparison

    When selecting business insurance, comparing different policies is crucial to make an informed decision. This table provides a comprehensive comparison of coverage, cost, and exclusions offered by various insurance companies:

    Insurance Company Offerings

    Insurance Company Coverage Cost Exclusions
    Company A General liability, property, business interruption, workers’ compensation $1,000-$5,000 per year Intentional acts, pollution, certain types of equipment
    Company B General liability, commercial auto, cyber liability, errors and omissions $2,000-$10,000 per year Acts of war, nuclear events, employee dishonesty
    Company C Commercial property, business income, crime, directors and officers liability $3,000-$15,000 per year Natural disasters (e.g., earthquakes, floods), acts of terrorism, contractual obligations

    Case Studies of Business Insurance Claims: Need Insurance For My Business

    Business insurance is a crucial safeguard against unforeseen events that can disrupt operations and jeopardize financial stability. Here are some compelling case studies showcasing how insurance coverage has empowered businesses to recover from challenging situations.

    Property Damage Claim

    A manufacturing facility suffered a devastating fire that destroyed equipment and inventory. The business had comprehensive property insurance, which covered the cost of replacing the damaged assets and repairing the building. Thanks to this coverage, the business was able to resume operations quickly, minimizing downtime and financial losses.

    Liability Claim

    A software company faced a lawsuit alleging negligence in the design of its product. The business had liability insurance, which covered the legal defense costs and any damages awarded to the plaintiff. The insurance coverage allowed the company to settle the case without draining its financial resources and enabled it to continue operating without significant disruption.

    Business Interruption Claim

    A natural disaster forced a retail store to close for several weeks. The business had business interruption insurance, which covered the loss of income during the closure period. This coverage helped the store pay for fixed expenses such as rent, utilities, and employee salaries, ensuring its financial viability during the challenging time.

    Cybersecurity Claim

    A healthcare provider experienced a data breach that compromised patient information. The business had cyber insurance, which covered the costs of notifying affected individuals, implementing security measures, and mitigating the financial impact of the breach. The insurance coverage enabled the provider to respond effectively to the incident, protecting its reputation and patient trust.

    Insurance Quotes and Purchasing

    Securing appropriate insurance coverage for your business is crucial. Obtaining quotes from multiple providers and understanding the factors that influence premiums are essential steps in making an informed decision. This section guides you through the process of obtaining insurance quotes, deciphering the factors that determine premiums, and outlining the steps involved in purchasing business insurance.

    Obtaining Insurance Quotes

    To compare coverage options and premiums, it is advisable to obtain quotes from multiple insurance providers. Here are the steps to follow:

    1. Identify Your Insurance Needs:Determine the specific coverage you require for your business, considering factors such as industry, location, and operations.
    2. Research Insurance Providers:Explore different insurance companies, comparing their reputation, financial stability, and customer service.
    3. Request Quotes:Contact the selected insurance providers and provide them with details about your business, including its size, industry, and risk profile. You can request quotes online, over the phone, or through an insurance agent.

    Last Point

    Need insurance for my business

    As you navigate the complexities of running a business, remember that adequate insurance coverage is your steadfast companion. It provides a safety net, empowering you to focus on growth and innovation while mitigating risks and safeguarding your assets. Invest in business insurance today, and secure your path to entrepreneurial success.

    Query Resolution

    What types of insurance coverage are essential for my business?

    The specific insurance coverage your business needs will vary depending on its size, industry, and risk profile. However, some common types include general liability insurance, property insurance, business interruption insurance, and workers’ compensation insurance.

    How can I compare different insurance policies?

    To compare different insurance policies, consider factors such as coverage, cost, exclusions, and the reputation of the insurance company. It’s also helpful to obtain quotes from multiple providers to ensure you’re getting the best coverage at a competitive price.

    What are the consequences of not having adequate insurance coverage?

    Without adequate insurance coverage, your business could be financially vulnerable in the event of a covered loss. You could be held personally liable for damages or expenses, and your business could face financial ruin.

  • Cash Check Online Instantly: A Swift and Secure Solution for Your Financial Needs

    Cash Check Online Instantly: A Swift and Secure Solution for Your Financial Needs

    Cash check online instantly and experience the convenience of accessing your funds without the hassle of traditional banking methods. With advanced technology and secure platforms, you can now cash checks from the comfort of your own home, saving time and effort.

    Our comprehensive guide explores the various instant check cashing methods, their benefits, and how to choose a reputable service. Dive in to discover the advantages of instant check cashing and how it can simplify your financial management.

    Instant Check Cashing Methods

    Cash check online instantly

    In today’s digital age, cashing checks instantly has become a convenient and accessible option. Various methods allow you to convert paper checks into cash funds quickly and securely.

    Among the popular platforms for instant check cashing are mobile banking apps and online check cashing services. Mobile banking apps offered by banks and credit unions enable users to deposit checks remotely using their smartphone cameras. Online check cashing services, such as Ingo Money and Check Cashing Now, provide a web-based platform for check deposit and cash advance.

    Security Measures

    Instant check cashing methods employ robust security measures to protect user funds. Mobile banking apps leverage multi-factor authentication, including passwords and biometrics, to prevent unauthorized access. Online check cashing services typically require identity verification through government-issued IDs and bank account information.

    Fees

    Fees associated with instant check cashing vary depending on the method and platform used. Mobile banking apps often offer free check deposits for customers with eligible accounts. Online check cashing services typically charge a fee ranging from 1% to 5% of the check amount.

    Benefits of Instant Check Cashing

    Instant check cashing offers numerous advantages over traditional methods. Its speed, convenience, and accessibility make it an ideal solution for various financial needs.

    One of the primary benefits of instant check cashing is the time-saving aspect. Unlike traditional methods that require visits to physical bank branches and lengthy processing times, instant check cashing can be completed within minutes, allowing individuals to access funds almost immediately.

    Convenience and Accessibility

    Instant check cashing provides unmatched convenience. With online platforms and mobile applications, users can cash checks from anywhere with an internet connection. This eliminates the need for travel and waiting in long queues, making it particularly beneficial for those with busy schedules or limited mobility.

    Emergency Situations

    In emergency situations where immediate access to funds is crucial, instant check cashing can be a lifesaver. It allows individuals to quickly convert checks into cash, providing financial assistance during unexpected events, such as medical emergencies or unexpected expenses.

    Comparison with Traditional Methods

    Compared to traditional check-cashing methods, instant check cashing offers significant advantages. It eliminates the need for physical bank visits, saving valuable time and effort. Additionally, instant check cashing often comes with lower fees and more flexible options, making it a cost-effective and convenient alternative.

    Eligibility and Requirements

    Cash check online instantly

    To qualify for instant check cashing services, individuals must meet specific eligibility criteria and provide the necessary documentation.

    The following checklist Artikels the general requirements:

    Required Documents, Cash check online instantly

    • Government-issued photo identification (e.g., driver’s license, passport)
    • Check to be cashed
    • Bank statement or proof of income (if required by the service provider)

    Limitations and Restrictions

    Some instant check cashing services may have limitations or restrictions on the types of checks they accept or the maximum amount that can be cashed.

    • Check Types:Certain services may only accept personal checks, while others may accept business checks or money orders.
    • Check Amount:There may be a maximum check amount that can be cashed instantly, typically ranging from $1,000 to $5,000.

    Tips for Choosing a Service

    Loans payday loan

    When selecting an instant check cashing service, consider the following factors:

    Fees

    Compare the fees charged by different providers. Some services may have higher fees for larger checks or expedited processing.

    Security

    Ensure the service uses industry-standard security measures to protect your personal and financial information. Look for services that encrypt data and comply with privacy regulations.

    Customer Support

    Choose a service with responsive and helpful customer support. You should be able to easily contact the company with any questions or issues.

    Availability

    Consider the availability of the service. Some services may only operate during certain hours or days. Choose a service that aligns with your needs and schedule.

    Reviews

    Read reviews from other customers to gauge the reliability and quality of the service. Positive reviews can indicate a reputable provider, while negative reviews can highlight potential issues.

    Security and Fraud Prevention

    Cashing checks online instantly involves transmitting sensitive financial information, making security paramount. Reputable services employ robust security measures to safeguard your data and prevent fraud.

    Encryption plays a crucial role in protecting your information during transmission. It converts your data into an unreadable format, making it inaccessible to unauthorized parties. Additionally, services may implement multi-factor authentication, requiring you to provide multiple forms of identification to access your account.

    Tips for Protecting Your Information

      • Choose a reputable service with a proven track record of security.
      • Never share your login credentials or sensitive information with anyone.
      • Be wary of emails or phone calls from unknown sources requesting personal information.
      • Monitor your account activity regularly for any suspicious transactions.
      • Report any unauthorized activity to the service immediately.


    Concluding Remarks: Cash Check Online Instantly

    Whether you’re facing a financial emergency or simply want to avoid the lines at the bank, cash check online instantly offers a fast and secure solution. By understanding the different methods, benefits, and security measures involved, you can make informed decisions and enjoy the convenience of accessing your funds in real-time.

    FAQ Compilation

    How long does it take to cash a check online instantly?

    With instant check cashing services, you can typically receive your funds within minutes or hours, depending on the platform and method you choose.

    Are there any fees associated with instant check cashing?

    Yes, most instant check cashing services charge a fee, which varies depending on the amount of the check and the platform used. It’s important to compare fees before selecting a service.

    What documents are required to cash a check online instantly?

    Typically, you will need to provide a photo ID, such as a driver’s license or passport, and a clear image of the front and back of the check.

    Is instant check cashing safe?

    Reputable instant check cashing services employ encryption and other security measures to protect your personal information and prevent fraud. However, it’s crucial to choose a trusted provider and be vigilant against potential scams.

  • Working Capital Line of Credit: A Lifeline for Business Growth

    Working Capital Line of Credit: A Lifeline for Business Growth

    The working capital line of credit, a financial lifeline for businesses, empowers them to navigate cash flow challenges and seize growth opportunities. This flexible financing solution offers a revolving credit line that can be drawn upon as needed, providing businesses with the liquidity they need to thrive.

    Understanding the ins and outs of a working capital line of credit is crucial for businesses seeking to optimize their financial health. From eligibility criteria to repayment terms, this guide delves into the intricacies of this financing option, empowering businesses to make informed decisions and unlock their growth potential.

    Working Capital Line of Credit Overview

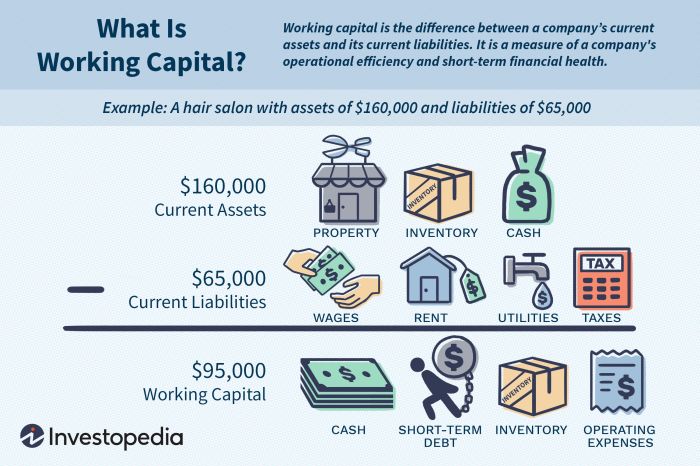
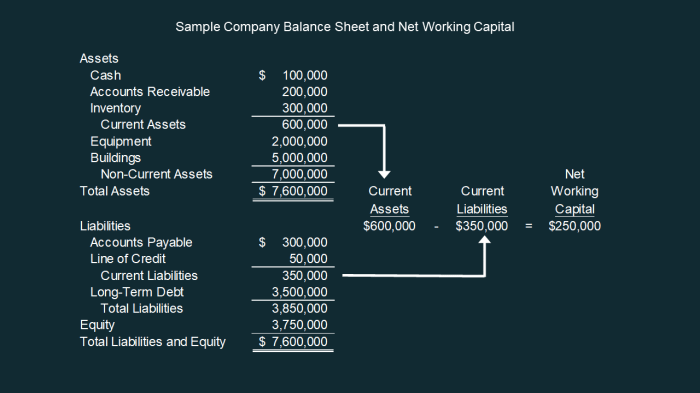
    A working capital line of credit (WCL) is a flexible source of financing that allows businesses to borrow funds to meet their short-term working capital needs. Working capital refers to the difference between a company’s current assets and current liabilities.

    A WCL provides businesses with access to additional funds to cover expenses such as inventory, accounts receivable, and operating costs.

    Businesses of all sizes and industries can benefit from a working capital line of credit. However, it is particularly useful for businesses that experience seasonal fluctuations in their cash flow, have high inventory levels, or are expanding rapidly. A WCL can provide a safety net for businesses to cover unexpected expenses or bridge gaps in cash flow.

    Advantages of Using a Working Capital Line of Credit

    • Flexibility:A WCL offers businesses flexibility in terms of the amount and timing of their borrowing. Businesses can draw on the line of credit as needed, and they only pay interest on the amount they borrow.
    • Quick Access to Funds:A WCL can provide businesses with quick access to funds, which can be crucial in meeting unexpected expenses or taking advantage of opportunities.
    • Improved Cash Flow:A WCL can help businesses improve their cash flow by providing them with additional funds to cover expenses and avoid late payments.
    • Reduced Borrowing Costs:A WCL can be a more cost-effective way to borrow money than other forms of financing, such as a term loan or invoice factoring.

    Disadvantages of Using a Working Capital Line of Credit

    • Interest Costs:Businesses will have to pay interest on the amount of money they borrow under a WCL. Interest rates can vary depending on the lender and the business’s creditworthiness.
    • Covenants and Restrictions:Lenders may impose covenants and restrictions on businesses that use a WCL. These covenants may limit the business’s ability to take on additional debt or make certain investments.
    • Personal Guarantees:In some cases, lenders may require personal guarantees from the business’s owners or directors as a condition of obtaining a WCL.

    Eligibility and Application Process

    Working capital line of credit

    Obtaining a working capital line of credit requires meeting specific criteria and following a defined application process. Lenders carefully evaluate applicants based on various factors to determine their eligibility and creditworthiness.

    Eligibility Criteria

    To qualify for a working capital line of credit, businesses typically need to:

    • Have a strong financial history with consistent revenue and profitability.
    • Maintain a healthy credit score and a low debt-to-income ratio.
    • Provide collateral or a personal guarantee to secure the loan.
    • Demonstrate a clear need for additional working capital.
    • Have a well-defined business plan outlining how the line of credit will be used.

    Application Process

    The application process for a working capital line of credit typically involves the following steps:

    1. Contacting a lender and submitting a formal application.
    2. Providing detailed financial information, including income statements, balance sheets, and cash flow projections.
    3. Submitting business plans, tax returns, and other supporting documents.
    4. Undergoing a credit check and financial analysis by the lender.
    5. Receiving a decision from the lender and negotiating loan terms if approved.

    Factors Considered by Lenders

    When evaluating an application for a working capital line of credit, lenders consider several factors, including:

    • The business’s financial performance and stability.
    • The experience and track record of the business owners.
    • The industry and market in which the business operates.
    • The purpose and intended use of the working capital.
    • The collateral or personal guarantee offered as security.

    Terms and Conditions

    Working capital lines of credit come with specific terms and conditions that borrowers must adhere to. These conditions Artikel the interest rates, repayment schedules, collateral requirements, and potential fees associated with the financing.

    Interest Rates

    Interest rates on working capital lines of credit vary depending on the lender, the borrower’s creditworthiness, and the current market conditions. Rates are typically floating, meaning they fluctuate with changes in the prime rate or other benchmark interest rates. Borrowers with strong credit histories and financial performance generally qualify for lower interest rates.

    Repayment Schedules

    Repayment schedules for working capital lines of credit can be structured to meet the borrower’s specific needs. Common repayment options include monthly installments, quarterly payments, or interest-only payments during the draw period, followed by principal and interest payments during the repayment period.

    Collateral Requirements

    Lenders may require collateral to secure working capital lines of credit, especially for larger loan amounts or borrowers with weaker credit profiles. Common forms of collateral include accounts receivable, inventory, and real estate. Providing collateral can help reduce the lender’s risk and potentially qualify the borrower for more favorable terms.

    Fees and Charges

    Working capital lines of credit may be subject to various fees and charges, including origination fees, commitment fees, and late payment fees. Origination fees are one-time charges assessed at the time the loan is established. Commitment fees are ongoing charges paid to the lender for maintaining the line of credit, even if it is not drawn upon.

    Late payment fees are charged if the borrower fails to make payments on time.

    Alternatives to Working Capital Lines of Credit

    Businesses seeking working capital have various financing options beyond working capital lines of credit. These alternatives offer distinct advantages and disadvantages, making it crucial to understand their nuances and select the most suitable option based on specific business needs.

    Key alternative financing options include term loans, invoice financing, and equity financing. Let’s explore each option in detail.

    Term Loans

    Term loans are traditional financing options where businesses borrow a lump sum of money from a lender and repay it over a fixed term, typically with monthly installments. Term loans often require collateral and can have longer application and approval processes compared to other alternatives.

    Advantages:

    • Fixed interest rates, providing predictable repayment costs.
    • Longer repayment terms, allowing for manageable monthly payments.
    • Can be used for a wide range of business purposes, including capital expenditures and working capital.

    Disadvantages:

    • Collateral requirements may limit accessibility for some businesses.
    • Longer application and approval processes compared to other alternatives.
    • Repayment schedules may not align with seasonal or fluctuating cash flows.

    Invoice Financing

    Invoice financing involves selling unpaid invoices to a financing company at a discount. The financing company advances a percentage of the invoice amount, providing businesses with immediate access to cash while waiting for customers to pay. Invoice financing is typically short-term and can be particularly useful for businesses with a high volume of accounts receivable.

    Advantages:

    • Provides quick access to cash, improving cash flow.
    • No collateral requirements, making it accessible to a wider range of businesses.
    • Flexible repayment terms that align with invoice payment schedules.

    Disadvantages:

    • Can be more expensive than other financing options, due to fees and discounts.
    • May require businesses to factor a significant portion of their invoices, limiting flexibility.
    • Can impact customer relationships if the financing company contacts customers directly for payment.

    Equity Financing

    Equity financing involves selling a portion of the business to investors in exchange for cash. This option can provide substantial funding but also dilutes ownership and may involve giving up some control of the business. Equity financing is typically considered a long-term financing solution.

    Advantages:

    • Provides access to large amounts of capital, suitable for significant growth or expansion.
    • No repayment obligations, as funds are not borrowed but invested.
    • Can enhance the credibility and reputation of the business by attracting investors.

    Disadvantages:

    • Dilutes ownership and may lead to loss of control over business decisions.
    • Can be complex and time-consuming to arrange.
    • Investors may expect a share of profits and may have influence on business operations.

    Best Practices for Utilizing a Working Capital Line of Credit

    Formula formulas calculation

    Effectively managing a working capital line of credit requires a disciplined approach and a clear understanding of its purpose and limitations. By following these best practices, businesses can maximize the benefits of this financing tool while minimizing potential risks.

    To optimize the use of a working capital line of credit, businesses should focus on cash flow management, financial forecasting, and maintaining a strong financial position.

    Cash Flow Management, Working capital line of credit

    Managing cash flow is critical for any business, but it becomes even more important when using a working capital line of credit. Businesses should implement a system for tracking cash inflows and outflows to ensure that they have sufficient liquidity to meet their obligations.

    This system should include:

    • A cash flow budget that projects future cash flows
    • Regular monitoring of accounts receivable and accounts payable
    • Procedures for managing inventory levels
    • A plan for dealing with unexpected expenses

    Financial Forecasting

    Financial forecasting is essential for businesses that want to use a working capital line of credit responsibly. By forecasting their financial needs, businesses can avoid overborrowing and ensure that they have sufficient funds to meet their obligations.

    Financial forecasting should include:

    • Preparing a detailed income statement
    • Projecting future cash flows
    • Identifying potential risks and opportunities
    • Developing contingency plans

    Maintaining a Strong Financial Position

    Maintaining a strong financial position is important for any business, but it is especially important for businesses that are using a working capital line of credit. Lenders will be more likely to approve a loan to a business with a strong financial position.

    Businesses can maintain a strong financial position by:

    • Managing their debt levels
    • Maintaining a healthy profit margin
    • Building up a cash reserve
    • Investing in their business

    Monitoring Financial Performance

    Monitoring financial performance is essential for any business, but it is especially important for businesses that are using a working capital line of credit. By monitoring their financial performance, businesses can identify potential problems early on and take corrective action.

    Financial performance should be monitored on a regular basis, and businesses should consider using financial ratios to track their progress. Financial ratios can help businesses identify trends and make informed decisions about their use of a working capital line of credit.

    Making Timely Adjustments

    Making timely adjustments to their use of a working capital line of credit is essential for businesses that want to use this financing tool responsibly. If a business’s financial situation changes, it should adjust its use of the line of credit accordingly.

    Businesses should consider making adjustments to their use of a working capital line of credit if they:

    • Experience a change in their cash flow
    • Need to make a large investment
    • Face unexpected expenses
    • Are experiencing financial difficulties

    Final Conclusion

    Working capital line of credit

    In the ever-changing business landscape, a working capital line of credit emerges as a valuable tool for businesses seeking financial agility. By understanding the eligibility requirements, terms and conditions, and best practices associated with this financing option, businesses can harness its power to overcome cash flow hurdles, invest in growth initiatives, and achieve long-term success.

    FAQ Compilation

    What is the primary purpose of a working capital line of credit?

    A working capital line of credit provides businesses with flexible access to funds to meet short-term operational expenses, such as inventory purchases, payroll, and marketing costs.

    What types of businesses typically utilize working capital lines of credit?

    Businesses of all sizes and industries can benefit from working capital lines of credit, particularly those experiencing seasonal fluctuations in cash flow or facing unexpected expenses.

    What are the advantages of using a working capital line of credit?

    Working capital lines of credit offer several advantages, including increased financial flexibility, improved cash flow management, and the ability to seize growth opportunities.

    What factors do lenders consider when evaluating a working capital line of credit application?

    Lenders typically assess an applicant’s creditworthiness, financial history, cash flow projections, and business plan when evaluating a working capital line of credit application.

    What are some best practices for managing a working capital line of credit?

    Effective management of a working capital line of credit involves careful monitoring of cash flow, regular financial forecasting, and maintaining a strong financial position.

  • Working Capital Loans: A Lifeline for Businesses

    Working Capital Loans: A Lifeline for Businesses

    Working capital loans are a vital financial tool that can provide businesses with the liquidity they need to operate and grow. These loans are typically used to finance short-term expenses such as inventory, accounts receivable, and operating costs.

    Businesses of all sizes can benefit from working capital loans. Small businesses may use them to get started or expand their operations, while larger businesses may use them to bridge seasonal gaps in cash flow or finance new projects.

    Understanding Working Capital Loans

    Loan loans

    Working capital loans are short-term loans designed to bridge the gap between a company’s current assets and its current liabilities. They provide businesses with the necessary liquidity to meet their day-to-day operational expenses, such as payroll, inventory, and marketing.

    Businesses that typically utilize working capital loans include:

    • Startups and small businesses with limited access to traditional financing.
    • Companies experiencing seasonal fluctuations in revenue.
    • Businesses facing unexpected expenses or temporary cash flow disruptions.

    Advantages of Working Capital Loans

    • Flexibility:Working capital loans can be tailored to the specific needs of a business, with flexible repayment terms and loan amounts.
    • Quick Access to Funds:These loans can be approved and disbursed quickly, providing businesses with immediate access to cash.
    • Improved Cash Flow:Working capital loans help businesses manage their cash flow more effectively, ensuring they have sufficient funds to cover expenses.

    Disadvantages of Working Capital Loans

    • Interest Charges:Working capital loans typically come with interest charges, which can increase the overall cost of borrowing.
    • Collateral Requirements:Some working capital loans may require collateral, such as inventory or equipment, which can be a risk for businesses.
    • Limited Loan Amounts:Working capital loans are typically limited in amount, which may not be sufficient for businesses with large funding needs.

    Eligibility Criteria and Application Process

    Working capital loans are designed to provide businesses with the liquidity they need to meet their short-term financial obligations. To qualify for a working capital loan, businesses must meet certain eligibility criteria and follow a specific application process.

    Eligibility Criteria

    The eligibility criteria for working capital loans vary from lender to lender. However, some common criteria include:

    • Business type:Most lenders will only provide working capital loans to businesses that are for-profit and have been in operation for at least two years.
    • Credit history:Lenders will review the business’s credit history to assess its ability to repay the loan.
    • Financial statements:Lenders will require the business to provide financial statements, such as a balance sheet and income statement, to assess its financial health.
    • Collateral:Some lenders may require the business to provide collateral, such as real estate or equipment, to secure the loan.

    Application Process

    The application process for working capital loans typically involves the following steps:

    1. Complete a loan application:The business will need to complete a loan application that provides information about the business, its financial situation, and its loan request.
    2. Submit supporting documents:The business will need to submit supporting documents, such as financial statements, tax returns, and business licenses.
    3. Meet with a lender:The business may be required to meet with a lender to discuss its loan request and provide additional information.
    4. Receive a loan decision:The lender will review the business’s loan application and supporting documents and make a decision on whether to approve the loan.

    Checklist of Required Documents for Loan Applications

    The following is a checklist of required documents for working capital loan applications:

    • Loan application
    • Financial statements (balance sheet, income statement, cash flow statement)
    • Tax returns
    • Business licenses
    • Collateral (if required)

    Types of Working Capital Loans

    Working capital loans vary based on factors like loan term, interest rates, and repayment options. Understanding these variations helps businesses choose the most suitable loan for their specific needs.

    Short-Term Loans

    Short-term working capital loans have a repayment period of less than a year. They are ideal for businesses requiring immediate cash flow to cover expenses like inventory purchases or seasonal fluctuations. Examples include:

    Line of Credit

    A flexible loan that allows businesses to draw funds as needed up to a pre-approved limit.

    Invoice Financing

    Provides an advance on outstanding invoices, enabling businesses to access cash tied up in accounts receivable.

    Long-Term Loans, Working capital loan

    Long-term working capital loans have a repayment period of more than a year. They are suitable for businesses seeking financing for capital expenditures, such as equipment purchases or property acquisitions. Examples include:

    Term Loans

    Fixed-rate loans with regular payments over a specified period.

    Equipment Financing

    Loans specifically designed to finance the purchase of business equipment.

    Variable-Rate Loans

    Variable-rate working capital loans have interest rates that fluctuate with market conditions. They are suitable for businesses comfortable with interest rate risk and seeking potential savings when rates decline.

    Fixed-Rate Loans

    Fixed-rate working capital loans have interest rates that remain constant throughout the loan term. They provide stability and predictability in repayment costs, making them suitable for businesses seeking to manage cash flow effectively.

    Secured Loans

    Secured working capital loans are backed by collateral, such as property or equipment. They typically offer lower interest rates than unsecured loans due to the reduced risk for the lender.

    Unsecured Loans

    Unsecured working capital loans do not require collateral. They are typically more expensive than secured loans due to the higher risk for the lender. However, they may be suitable for businesses with limited or no assets to pledge as collateral.

    Impact on Business Operations

    Working capital loan

    Working capital loans can significantly impact business operations, both positively and negatively. Understanding these impacts is crucial for businesses considering such loans.

    Positive Impacts

    • Improved Cash Flow:Working capital loans provide immediate access to funds, which can alleviate cash flow constraints and improve the business’s financial flexibility.
    • Support Growth:Access to additional capital can support expansion plans, such as investing in new equipment, hiring additional staff, or entering new markets.
    • Enhanced Financial Stability:Working capital loans can provide a financial cushion during periods of slow sales or unexpected expenses, helping businesses maintain stability and avoid financial distress.

    Potential Risks and Challenges

    • Interest Payments:Working capital loans typically come with interest charges, which can increase the business’s overall financing costs.
    • Repayment Obligations:Businesses must ensure they can meet the loan repayment schedule to avoid default and potential damage to their creditworthiness.
    • Collateral Requirements:Some working capital loans may require collateral, which can tie up valuable assets and increase the risk to the business.

    Alternatives to Working Capital Loans

    Working capital loans are a common financing option for businesses, but they are not the only option. There are a number of alternative financing options available, each with its own advantages and disadvantages.

    When choosing an alternative financing option, it is important to consider the business’s specific needs. Some factors to consider include the amount of financing needed, the length of time the financing is needed for, and the business’s creditworthiness.

    Invoice Factoring

    Invoice factoring is a type of financing that allows businesses to sell their unpaid invoices to a factoring company. The factoring company then advances the business a percentage of the invoice amount, typically 70-85%. The factoring company then collects the payment from the customer and remits the remaining balance to the business, minus a factoring fee.

    Invoice factoring can be a good option for businesses that have a large number of unpaid invoices and need access to cash quickly. However, it can be expensive, as factoring fees can range from 1-5% of the invoice amount.

    Accounts Receivable Financing

    Accounts receivable financing is similar to invoice factoring, but it allows businesses to borrow against their unpaid invoices without selling them. The lender advances the business a percentage of the invoice amount, typically 80-90%, and the business repays the loan when the customer pays the invoice.

    Accounts receivable financing can be a good option for businesses that have a large number of unpaid invoices and need access to cash quickly. However, it can also be expensive, as interest rates can range from 10-15%.

    Asset-Based Lending

    Asset-based lending is a type of financing that allows businesses to borrow against their assets, such as inventory, equipment, or real estate. The lender advances the business a percentage of the value of the assets, typically 50-75%. The business then repays the loan over a period of time.

    Asset-based lending can be a good option for businesses that have a large amount of assets and need access to cash quickly. However, it can be risky, as the lender can seize the assets if the business defaults on the loan.

    Final Wrap-Up

    Working capital loan

    Working capital loans can be a valuable resource for businesses, but it is important to understand the terms and conditions of the loan before applying. Businesses should also consider the alternatives to working capital loans, such as lines of credit or equity financing, to determine the best option for their needs.

    Q&A

    What are the benefits of working capital loans?

    Working capital loans can provide businesses with a number of benefits, including:

    • Improved cash flow
    • Increased flexibility
    • Reduced financial risk
    • Support for growth

    What are the risks of working capital loans?

    Working capital loans also come with some risks, including:

    • High interest rates
    • Short repayment terms
    • Default risk

    What are the alternatives to working capital loans?

    There are a number of alternatives to working capital loans, including:

    • Lines of credit
    • Equity financing
    • Invoice factoring
    • Asset-based lending
  • Business Consolidation Loans: A Comprehensive Guide to Debt Consolidation for Businesses

    Business Consolidation Loans: A Comprehensive Guide to Debt Consolidation for Businesses

    Business consolidation loans take center stage in this illuminating narrative, inviting readers to delve into a world of financial strategies and debt management solutions. This comprehensive guide unveils the intricate details of consolidation loans, empowering businesses with the knowledge to navigate the complexities of debt and emerge with renewed financial strength.

    From understanding the types of consolidation loans available to exploring the factors that influence loan approval, this guide provides a roadmap for businesses seeking to streamline their debt obligations and achieve long-term financial stability.

    Overview of Business Consolidation Loans

    Business consolidation loan

    Business consolidation loans are financial solutions designed to simplify and streamline business operations by consolidating multiple debts into a single, manageable loan. This consolidation process offers several benefits, including reduced interest expenses, improved cash flow, and simplified debt management.

    Businesses of various sizes and industries can benefit from consolidation loans. Companies with high-interest debts, multiple loan payments, or a need to improve their credit profile are prime candidates for this type of financing.

    Types of Business Consolidation Loans

    There are two primary types of business consolidation loans:

    • Secured Consolidation Loans:These loans require collateral, such as real estate or equipment, to secure the loan. Secured loans typically offer lower interest rates and longer repayment terms.
    • Unsecured Consolidation Loans:These loans do not require collateral. They typically have higher interest rates and shorter repayment terms than secured loans.

    Factors to Consider When Applying for a Business Consolidation Loan

    Business consolidation loan

    When applying for a business consolidation loan, several factors influence the lender’s decision-making process. Understanding these factors can increase your chances of loan approval and secure favorable terms.

    Creditworthiness

    Lenders evaluate your business’s credit history and score to assess its financial stability and ability to repay the loan. A strong credit history, with timely payments and a high score, indicates a lower risk to the lender.

    Debt-to-Income Ratio, Business consolidation loan

    The debt-to-income ratio measures your business’s ability to manage its existing debt obligations relative to its income. A high ratio indicates a higher risk of default and can negatively impact loan approval.

    Cash Flow

    Lenders assess your business’s cash flow to ensure it can cover loan repayments while maintaining operational expenses. A steady and sufficient cash flow demonstrates the business’s financial stability and ability to meet its obligations.

    Business Plan

    A well-defined business plan Artikels your business’s financial goals, strategies, and growth potential. It provides lenders with a clear understanding of your business’s viability and future prospects.

    Collateral

    Some lenders may require collateral, such as real estate or equipment, to secure the loan. Providing collateral reduces the lender’s risk and can improve your chances of approval.

    Industry and Market Analysis

    Lenders consider the industry and market your business operates in. They evaluate factors such as competition, growth potential, and economic conditions to assess the business’s long-term viability.

    Tips for Improving Your Chances of Loan Approval

    • Maintain a strong credit history by making timely payments and managing debt responsibly.
    • Keep your debt-to-income ratio low by reducing existing debt or increasing income.
    • Generate a steady and sufficient cash flow by optimizing operations and exploring new revenue streams.
    • Develop a comprehensive business plan that Artikels your financial goals, strategies, and growth potential.
    • Consider providing collateral to reduce the lender’s risk and improve your chances of approval.

    Benefits and Drawbacks of Business Consolidation Loans

    Consolidating business debts can offer advantages and disadvantages. Understanding these factors helps businesses make informed decisions. Advantages

    • Simplified Debt Management:Consolidation combines multiple debts into one, reducing the number of payments and simplifying accounting.
    • Lower Interest Rates:Consolidation loans often secure lower interest rates than individual business debts, saving money on interest expenses.
    • Improved Cash Flow:By reducing the total monthly debt payments, consolidation frees up cash flow for other business needs.

    Disadvantages

    • Extended Loan Term:Consolidation loans may have longer repayment periods, which can increase the overall interest paid.
    • Credit Score Impact:Applying for a consolidation loan can trigger a credit inquiry, which may temporarily lower the business’s credit score.
    • Additional Fees:Some consolidation loans come with fees, such as origination fees or prepayment penalties, which can add to the overall cost.

    Impact on Cash FlowConsolidation loans can significantly improve cash flow by reducing the total monthly debt payments. This freed-up cash can be used for business expansion, investment, or working capital. Impact on Interest RatesConsolidation loans typically secure lower interest rates than individual business debts. This can result in significant savings on interest expenses over the loan term.

    Impact on Credit ScoresApplying for a consolidation loan can trigger a credit inquiry, which may temporarily lower the business’s credit score. However, if the business makes timely payments on the consolidation loan, it can improve its credit score in the long run. Example:A small business with multiple high-interest loans consolidated its debts into a single consolidation loan with a lower interest rate.

    This reduced their monthly payments by 20%, freeing up cash flow for inventory expansion. Example:Another business experienced a temporary credit score drop after applying for a consolidation loan. However, by consistently making timely payments, their credit score rebounded within a year.

    Alternatives to Business Consolidation Loans

    When exploring options to manage debt, businesses may consider alternatives to business consolidation loans. These alternatives offer varying terms, interest rates, and repayment structures, each with its own advantages and disadvantages. Understanding these alternatives can help businesses make informed decisions based on their specific financial needs.

    Equity Financing

    Equity financing involves selling a portion of the business to investors in exchange for capital. This option can provide access to significant funding without incurring debt. However, it dilutes ownership and control of the business.

    • Pros:No monthly payments, potential for long-term growth.
    • Cons:Loss of ownership, potential for conflicts with investors.

    Invoice Factoring

    Invoice factoring involves selling outstanding invoices to a factoring company at a discount. This provides immediate cash flow but typically comes with higher interest rates than traditional loans.

    • Pros:Quick access to cash, no personal guarantees required.
    • Cons:Higher costs, potential damage to customer relationships.

    Line of Credit

    A line of credit provides access to a revolving pool of funds that can be drawn upon as needed. It offers flexibility but requires regular interest payments even when funds are not utilized.

    • Pros:Flexibility, no restrictions on use of funds.
    • Cons:Interest charges on unused funds, potential for overdraft fees.

    Government Grants

    Government grants provide non-repayable funding to businesses that meet specific criteria. While they can be a valuable source of capital, they are often competitive and may require significant time and effort to secure.

    • Pros:No repayment required, potential for substantial funding.
    • Cons:Highly competitive, may require specific qualifications.

    Case Studies and Success Stories

    Consolidation loans have proven to be a valuable tool for businesses looking to improve their financial health. Here are a few case studies of businesses that have successfully utilized consolidation loans:

    Case Study 1: Small Business with High-Interest Debt

    A small business owner with multiple high-interest loans was struggling to keep up with payments. The business had a good track record and strong cash flow, but the high interest rates were eating into profits. The business owner consolidated their loans into a single loan with a lower interest rate, freeing up cash flow and reducing monthly payments.

    Case Study 2: Business with Seasonal Cash Flow

    A business with seasonal cash flow was facing cash flow shortages during the off-season. The business owner used a consolidation loan to bridge the gap during these periods, ensuring they could meet their expenses and avoid late payments.

    Case Study 3: Business with Expansion Plans

    A business with expansion plans needed additional capital to purchase new equipment and hire more staff. The business owner consolidated their existing loans and used the extra cash flow to fund their expansion plans, resulting in increased revenue and profitability.

    Long-Term Impact of Consolidation Loans

    Consolidation loans can have a significant long-term impact on businesses. By reducing interest expenses and freeing up cash flow, businesses can improve their financial stability, increase profitability, and invest in growth opportunities. Additionally, consolidation loans can simplify financial management and improve credit scores, making it easier to secure future financing.

    Epilogue

    Debt consolidation cons pros

    As we conclude our exploration of business consolidation loans, it becomes evident that these financial tools can be instrumental in revitalizing a business’s financial health. By carefully considering the advantages and disadvantages, businesses can make informed decisions that align with their specific needs and goals.

    Whether it’s improving cash flow, reducing interest expenses, or enhancing creditworthiness, consolidation loans offer a path towards financial freedom and sustainable growth.

    FAQ Summary

    What are the primary benefits of business consolidation loans?

    Consolidation loans simplify debt management by combining multiple debts into a single, manageable payment. This streamlined approach reduces interest expenses, improves cash flow, and enhances credit scores.

    How can businesses improve their chances of loan approval?

    Strong financial statements, a clear business plan, and a solid credit history are crucial for loan approval. Businesses should also demonstrate their ability to repay the loan and Artikel how the funds will be used to improve the company’s financial health.

    What are some alternatives to business consolidation loans?

    Invoice factoring, merchant cash advances, and equity financing are alternative options for businesses seeking to manage debt. Each option has its own advantages and disadvantages, and businesses should carefully consider their specific needs before making a decision.

  • Unlock Financial Flexibility: Best Small Business Line of Credit

    Unlock Financial Flexibility: Best Small Business Line of Credit

    In the realm of small business finance, the best small business line of credit emerges as a lifeline, empowering entrepreneurs with a flexible funding solution that adapts to their ever-changing needs. This financial instrument offers a revolving pool of funds, akin to a trusty financial companion ready to support your business’s growth and unexpected expenses.

    Navigating the complexities of small business lines of credit can be a daunting task. But fear not, for this comprehensive guide will illuminate the path, empowering you to make informed decisions that unlock the full potential of this financial tool.

    Understanding Small Business Lines of Credit

    A line of credit is a type of financing that allows small businesses to borrow money up to a predetermined limit. It is a flexible and convenient way to access capital, as businesses can draw on the funds as needed and only pay interest on the amount they borrow.

    There are several benefits to using a line of credit for small businesses. First, it provides a source of liquidity that can be used to cover unexpected expenses, fund growth initiatives, or purchase inventory. Second, it can help businesses improve their cash flow by allowing them to borrow money to cover expenses until they receive payment from customers.

    Third, lines of credit can be a more affordable option than other types of financing, such as loans or credit cards.

    However, there are also some drawbacks to using a line of credit. First, businesses may be required to provide collateral to secure the loan, which can put their assets at risk. Second, lines of credit can have high interest rates, which can increase the cost of borrowing.

    Third, businesses may be required to make regular payments on the line of credit, even if they are not using the funds.

    Types of Lines of Credit

    There are several different types of lines of credit available to small businesses. The most common type is a secured line of credit, which is backed by collateral, such as real estate or equipment. Unsecured lines of credit are not backed by collateral and are therefore more risky for lenders.

    As a result, unsecured lines of credit typically have higher interest rates than secured lines of credit.

    Another type of line of credit is a revolving line of credit. A revolving line of credit allows businesses to borrow money up to a predetermined limit and then repay the loan over time. The business can then borrow the money again up to the limit, as long as they make the required payments.

    Evaluating Your Business’s Needs

    Credit business line small lines ultimate guide among businesses common

    Assessing your business’s financial health is crucial before applying for a line of credit. Lenders will thoroughly evaluate your business’s eligibility, considering factors like cash flow, credit history, and business plan.

    Strong cash flow demonstrates your business’s ability to generate sufficient income to cover expenses and repay debts. A positive credit history reflects your business’s track record of meeting financial obligations.

    Financial Health Assessment, Best small business line of credit

    • Review financial statements (income statement, balance sheet, cash flow statement) to analyze revenue, expenses, and cash flow.
    • Calculate key financial ratios (e.g., current ratio, debt-to-equity ratio) to assess liquidity and financial leverage.
    • Identify areas of strength and weakness in your financial performance.

    Eligibility Considerations

    • Lenders typically require a minimum annual revenue or profitability threshold.
    • Good to excellent personal and business credit scores are often necessary.
    • A solid business plan outlining your financial projections and growth strategy is essential.

    Researching and Comparing Lenders

    Best small business line of credit

    Choosing the right lender is crucial for securing the best terms and conditions for your small business line of credit. Thorough research and comparison among multiple lenders can help you identify the most suitable option that aligns with your specific business needs and financial situation.

    Comparing Different Lenders

    To make an informed decision, it is essential to compare the offerings of various lenders. Consider the following key factors when comparing small business lines of credit:

    • Interest Rates:The interest rate charged on the line of credit will impact your overall borrowing costs. Compare annual percentage rates (APRs) to determine the most competitive rates available.
    • Fees:Lenders may charge origination fees, annual fees, or other administrative fees. Understand all applicable fees to avoid unexpected expenses.
    • Loan Terms:The loan term refers to the duration of the line of credit. Consider the repayment period and any prepayment penalties to ensure alignment with your business’s financial capabilities.
    • Loan Limits:The maximum amount you can borrow under the line of credit is known as the loan limit. Determine the appropriate loan size to meet your business’s funding needs.
    • Eligibility Criteria:Lenders have varying eligibility requirements for small business lines of credit. Review the criteria, such as credit score, revenue, and business history, to assess your eligibility.
    • Customer Service:The quality of customer service can be a valuable asset when managing your line of credit. Consider the availability, responsiveness, and helpfulness of lender representatives.

    By carefully researching and comparing multiple lenders, you can make an informed decision and secure the most favorable terms for your small business line of credit.

    Applying for a Line of Credit

    Best small business line of credit

    Applying for a small business line of credit involves gathering the necessary documentation and completing loan applications. It is important to present your business in a favorable light to increase your chances of approval.

    Steps Involved in Applying for a Line of Credit

    1. Gather the necessary documentation.This includes financial statements, tax returns, business plans, and personal credit reports.
    2. Complete loan applications.These applications will ask for information about your business, your financial situation, and your use of the funds.
    3. Submit your application to lenders.You can submit applications to multiple lenders to compare offers.
    4. Wait for a decision.Lenders will review your application and make a decision on whether or not to approve your loan.

    Tips for Presenting Your Business in a Favorable Light

    • Highlight your strengths.Emphasize your business’s strengths, such as your experience, your financial stability, and your growth potential.
    • Be prepared to answer questions.Lenders will likely have questions about your business, so be prepared to answer them in a clear and concise manner.
    • Be honest and transparent.Do not try to hide any negative information about your business. Lenders will appreciate your honesty and transparency.
    • Get help from a professional.If you are not comfortable applying for a loan on your own, you can get help from a financial advisor or a loan broker.

    Managing and Using a Line of Credit

    Managing a line of credit responsibly is crucial for maintaining financial stability and utilizing it effectively. To ensure optimal usage, it’s essential to adhere to best practices, including maintaining a strong credit score and making timely payments.

    Beyond these fundamentals, exploring creative ways to utilize a line of credit can unlock its full potential in supporting business growth and operations. This includes leveraging the line of credit for strategic investments, managing seasonal fluctuations in cash flow, and covering unexpected expenses.

    Maximizing Line of Credit Utilization

    To maximize the benefits of a line of credit, consider the following strategies:

    • Investing in Growth Initiatives:Utilize the line of credit to finance expansion projects, new equipment purchases, or marketing campaigns that can drive revenue growth.
    • Managing Cash Flow Seasonality:Smooth out cash flow fluctuations by accessing the line of credit during periods of lower income or increased expenses.
    • Covering Unexpected Expenses:Prepare for unexpected events, such as emergencies or unexpected invoices, by having a line of credit as a safety net.

    Closing Summary

    As you venture into the world of small business lines of credit, remember that knowledge is your most valuable asset. By understanding your business’s needs, researching lenders diligently, and managing your line of credit responsibly, you can harness its power to fuel your business’s success.

    May this guide serve as your trusty compass, leading you towards financial stability and growth.

    Question Bank: Best Small Business Line Of Credit

    What are the advantages of a small business line of credit?

    A small business line of credit offers numerous advantages, including flexibility in accessing funds, the ability to cover unexpected expenses, and the potential to improve your business’s cash flow.

    How do I determine if my business qualifies for a line of credit?

    Lenders typically assess your business’s financial health, cash flow, credit history, and business plan when evaluating your eligibility for a line of credit.

    What are the different types of small business lines of credit?

    There are various types of small business lines of credit available, including secured, unsecured, and revolving lines of credit. Each type offers unique features and requirements.