Blog

  • Small Business Line of Credit: A Lifeline for Growth and Success

    Small Business Line of Credit: A Lifeline for Growth and Success

    Small business line of credit, a financial lifeline, empowers entrepreneurs to seize opportunities, navigate challenges, and propel their ventures to new heights. Its versatility and flexibility make it an indispensable tool for businesses seeking growth and stability.

    This comprehensive guide delves into the intricacies of small business lines of credit, exploring their benefits, eligibility criteria, application process, terms and conditions, and alternatives. Case studies and best practices provide valuable insights, empowering you to make informed decisions and harness the full potential of this financing solution.

    Overview of Small Business Lines of Credit
    Small business line of credit

    Small business lines of credit are a type of financing that provides businesses with access to a pool of funds that they can draw on as needed. This can be a valuable tool for businesses that need to cover unexpected expenses, fund growth, or manage cash flow.

    There are many different types of small business lines of credit available, each with its own unique features and benefits. Some of the most common types of lines of credit include:

    Secured Lines of Credit

    Secured lines of credit are backed by collateral, such as real estate or equipment. This type of line of credit typically has a lower interest rate than unsecured lines of credit, but it also comes with the risk of losing the collateral if the business defaults on the loan.

    Unsecured Lines of Credit

    Unsecured lines of credit are not backed by collateral. This type of line of credit typically has a higher interest rate than secured lines of credit, but it also comes with the benefit of not having to put up any collateral.

    Revolving Lines of Credit

    Revolving lines of credit allow businesses to draw on the funds as needed and then repay the borrowed amount plus interest. This type of line of credit is often used for short-term financing needs, such as covering unexpected expenses or funding seasonal inventory.

    Term Loans

    Term loans are a type of line of credit that is paid back in fixed installments over a set period of time. This type of line of credit is often used for long-term financing needs, such as purchasing equipment or expanding operations.

    Eligibility and Application Process

    To qualify for a small business line of credit, businesses typically need to meet certain eligibility criteria, which may vary depending on the lender. These criteria often include factors such as:

    • Time in business: Lenders may require businesses to have been operating for a certain period, often between one and three years.
    • Annual revenue: Businesses may need to demonstrate a minimum level of annual revenue to qualify.
    • Credit history: Lenders will typically review the business owner’s personal and business credit history to assess their creditworthiness.
    • Collateral: Some lenders may require businesses to provide collateral, such as real estate or equipment, to secure the line of credit.

    The application process for a small business line of credit typically involves submitting a loan application to the lender. This application will typically require the business to provide information such as:

    • Business financial statements, including income statements, balance sheets, and cash flow statements.
    • Tax returns.
    • Business plan.
    • Personal financial statements for the business owner(s).

    To increase the chances of approval for a small business line of credit, businesses should:

    • Have a strong business plan that demonstrates the viability of the business.
    • Maintain good credit history.
    • Provide collateral, if required.
    • Be prepared to provide the lender with all necessary documentation.

    Terms and Conditions: Small Business Line Of Credit

    Small business line of credit

    Understanding the terms and conditions of a small business line of credit is crucial before applying. These terms Artikel the interest rates, fees, and repayment schedules that govern the loan.

    It’s essential to carefully review the loan agreement to ensure a clear understanding of the obligations and responsibilities involved.

    Interest Rates

    Interest rates on small business lines of credit vary depending on the lender, your creditworthiness, and the current market conditions. Rates can be fixed or variable, so it’s important to understand how changes in interest rates may affect your monthly payments.

    Fees

    Lenders may charge various fees associated with small business lines of credit, such as origination fees, annual fees, and late payment fees. These fees can add to the overall cost of borrowing, so it’s important to factor them into your decision.

    Repayment Schedules, Small business line of credit

    Repayment schedules for small business lines of credit typically involve monthly payments that include both principal and interest. The length of the repayment period can vary, and some lenders offer flexible repayment options that allow you to adjust your payments based on your cash flow.

    Comparison Table of Lenders’ Terms and Conditions

    To make an informed decision, it’s helpful to compare the terms and conditions offered by different lenders. The following table provides a quick overview of key terms from various lenders:

    Lender Interest Rate Fees Repayment Schedule
    Bank A 5.5%

    7.5%

    $500 origination fee, $50 annual fee Monthly payments over 3-5 years
    Bank B 6.0%

    8.0%

    $250 origination fee, $25 monthly maintenance fee Monthly payments over 2-7 years
    Bank C 5.0%

    7.0%

    $1,000 origination fee, no annual fee Monthly payments over 1-10 years

    Alternatives to Small Business Lines of Credit
    Ultimate

    Small business lines of credit are not the only financing option available to small businesses. Other alternatives include business loans, credit cards, and equity financing. Each option has its own unique features and benefits, and the best choice for a particular business will depend on its specific needs.

    The following table compares the key features of each of these financing options:

    Feature Business Loan Business Credit Card Equity Financing
    Amount of financing Varies depending on the lender and the creditworthiness of the business Typically lower than business loans Can be significant, but can also dilute ownership of the business
    Interest rate Typically higher than business credit cards, but lower than equity financing Typically higher than business loans, but lower than equity financing No interest payments, but the investor will receive a share of the business’s profits
    Repayment terms Typically have fixed repayment terms, with monthly payments Typically have revolving balances, with minimum monthly payments No fixed repayment terms, but the investor will typically expect to receive a return on their investment within a certain period of time
    Collateral May require collateral, such as real estate or equipment Typically do not require collateral May require the business to give up some ownership
    Application process Can be lengthy and complex Typically easier and faster than business loans Can be complex and time-consuming

    When choosing a financing option, it is important to consider the following factors:

    • The amount of financing needed
    • The interest rate and repayment terms
    • The collateral requirements
    • The application process

    By carefully considering these factors, businesses can choose the financing option that is best suited to their needs.

    Case Studies and Best Practices

    Delve into real-world success stories of small businesses that have harnessed the power of lines of credit to fuel their growth. Explore the strategies they employed and the positive outcomes they achieved. Learn from their experiences and gain valuable insights into the effective utilization of this financing tool.

    Best Practices for Managing a Small Business Line of Credit

    • Establish Clear Objectives:Determine the specific business needs that the line of credit will address, whether it’s inventory expansion, seasonal cash flow fluctuations, or unexpected expenses.
    • Track and Monitor Usage:Regularly review your line of credit balance and usage patterns to ensure alignment with your business goals. Avoid overextending yourself and maintain a manageable debt-to-income ratio.
    • Negotiate Favorable Terms:Explore different lenders and compare interest rates, fees, and repayment schedules. Choose the option that best suits your business’s financial situation and long-term objectives.
    • Maintain a Strong Credit Profile:Your creditworthiness plays a crucial role in securing and maintaining a favorable line of credit. Pay bills on time, keep debt levels low, and build a positive credit history.
    • Consider Seasonality:If your business experiences seasonal fluctuations, adjust your line of credit usage accordingly. Use the funds during peak periods and repay during slower months to optimize your cash flow.

    Concluding Remarks

    In the competitive landscape of today’s business world, a small business line of credit stands as a beacon of hope, providing a flexible and reliable source of funding. By understanding its nuances and leveraging its advantages, entrepreneurs can unlock a world of possibilities, driving their ventures towards success and leaving an indelible mark on their industries.

    General Inquiries

    What is the purpose of a small business line of credit?

    A small business line of credit provides a flexible source of funding that can be used for various business expenses, such as inventory purchases, equipment upgrades, or unexpected costs.

    How do I qualify for a small business line of credit?

    Eligibility requirements vary among lenders, but generally include factors such as business revenue, credit history, and collateral.

    What are the interest rates and fees associated with a small business line of credit?

    Interest rates and fees vary depending on the lender and the borrower’s creditworthiness.

    How do I apply for a small business line of credit?

    The application process typically involves submitting financial statements, business plans, and personal credit information.

    What are the alternatives to a small business line of credit?

    Alternatives include business loans, credit cards, and equity financing.

  • Apply for a Business Line of Credit: Unlock Financial Flexibility

    Apply for a Business Line of Credit: Unlock Financial Flexibility

    In the realm of business finance, the Apply for Business Line of Credit emerges as a versatile tool, empowering entrepreneurs with a lifeline of liquidity to fuel growth and navigate unforeseen challenges. This comprehensive guide delves into the intricacies of securing a business line of credit, providing a roadmap to unlocking financial flexibility and propelling your enterprise to new heights.

    As we embark on this journey, we will explore the eligibility criteria, application process, and best practices for utilizing a business line of credit. Through insightful comparisons of different lenders, you will gain the knowledge to make informed decisions and secure the most advantageous terms for your business.

    Business Line of Credit Overview: Apply For Business Line Of Credit

    Apply for business line of credit

    A business line of credit (LOC) is a revolving credit facility that allows businesses to borrow money up to a predetermined limit. It’s similar to a credit card, but it’s specifically designed for business purposes. Businesses can use a LOC to cover various expenses, such as inventory purchases, payroll, or unexpected costs.

    LOCs offer several benefits. They provide businesses with access to quick and flexible financing, which can be crucial during periods of growth or unexpected financial challenges. Additionally, LOCs typically have lower interest rates than other forms of business financing, making them a cost-effective option.

    Drawbacks of Using a Line of Credit

    However, there are also some drawbacks to using a LOC. One potential concern is that LOCs can lead to excessive debt if not managed responsibly. Businesses should carefully monitor their LOC usage and ensure they have a plan to repay the borrowed funds.

    Another drawback is that LOCs may require personal guarantees from business owners. This means that the owner’s personal assets could be at risk if the business defaults on the loan.

    Eligibility Criteria

    To qualify for a business line of credit, applicants must meet certain eligibility criteria set by lenders. These criteria typically assess the financial health and stability of the business, as well as the personal creditworthiness of the business owners.

    Financial factors considered by lenders include the business’s revenue, profitability, debt-to-income ratio, and cash flow. Lenders also evaluate the business’s financial projections and business plan to assess its future growth potential.

    Non-Financial Factors

    In addition to financial factors, lenders also consider non-financial factors when evaluating business line of credit applications. These factors include the business’s industry, experience, and management team. Lenders may also consider the business’s location, customer base, and competitive landscape.

    Application Process

    Templates

    Applying for a business line of credit involves a straightforward process designed to assess your business’s financial health and creditworthiness.

    To initiate the application, you’ll need to gather essential documentation and information that will provide a comprehensive overview of your business’s financial standing.

    Required Documents and Information

    • Business plan:Outlining your business goals, strategies, and financial projections.
    • Financial statements:Including income statements, balance sheets, and cash flow statements.
    • Tax returns:For both the business and personal.
    • Business license and registration documents:Proof of your business’s legal existence.
    • Personal identification:Including a government-issued ID and proof of address.
    • Credit history:Both personal and business, if applicable.
    • Collateral:If required by the lender, this could include assets such as real estate or inventory.

    Lender Comparison

    To make an informed decision, it’s crucial to compare various lenders offering business lines of credit. Consider factors like interest rates, fees, loan amounts, and repayment terms to identify the most suitable option for your business needs.

    The table below provides a comprehensive comparison of different lenders, enabling you to evaluate their offerings side-by-side and make a well-informed choice.

    Lender Comparison Table

    Lender Interest Rates Fees Loan Amounts Repayment Terms
    Lender A 5%

    10%

    $100 origination fee, $50 annual fee $25,000

    $500,000

    Up to 5 years
    Lender B 4%

    9%

    No origination fee, $25 monthly fee $10,000

    $250,000

    Up to 3 years
    Lender C 6%

    12%

    $150 origination fee, no annual fee $50,000

    $1,000,000

    Up to 7 years
    Lender D 5%

    11%

    $75 origination fee, $35 annual fee $15,000

    $300,000

    Up to 4 years

    Best Practices for Using a Business Line of Credit

    Apply for business line of credit

    Effectively managing a business line of credit requires careful planning and disciplined use. By following these best practices, businesses can maximize the benefits and mitigate the risks associated with this valuable financing tool.

    Here are some key strategies for using a business line of credit effectively:

    Understanding the Terms and Conditions

    Before using a business line of credit, it’s crucial to thoroughly review and understand the terms and conditions, including the interest rate, repayment schedule, and any fees associated with the account. This knowledge will help businesses make informed decisions about how to use the funds and avoid any potential surprises.

    Establishing a Clear Purpose

    Businesses should have a clear understanding of the specific purposes for which they intend to use the business line of credit. This will help them avoid unnecessary borrowing and ensure that the funds are used for essential business needs.

    Managing Cash Flow, Apply for business line of credit

    A business line of credit can be an effective tool for managing cash flow. Businesses can draw on the line of credit to cover short-term expenses or seasonal fluctuations in revenue. By carefully managing cash flow, businesses can avoid overdraft fees and maintain a healthy financial position.

    Maintaining a Good Credit Score

    The interest rate and fees associated with a business line of credit are often based on the borrower’s credit score. Businesses should strive to maintain a good credit score by making timely payments and managing their debt responsibly.

    Monitoring Usage and Repayments

    Businesses should regularly monitor their usage of the business line of credit and make timely repayments. This will help them stay within their credit limit and avoid excessive interest charges.

    Seeking Professional Advice

    If businesses have any questions or concerns about using a business line of credit, they should consult with a financial advisor or accountant. These professionals can provide guidance and help businesses make informed decisions about their financing options.

    Closure

    In conclusion, applying for a business line of credit is a strategic move that can transform your financial landscape. By carefully considering the factors discussed in this guide, you can optimize your chances of approval and leverage this valuable resource to drive your business towards success.

    Remember, a business line of credit is not merely a financial tool; it is a catalyst for growth, innovation, and the realization of your entrepreneurial aspirations.

    Question & Answer Hub

    What are the typical eligibility requirements for obtaining a business line of credit?

    Lenders typically consider factors such as business revenue, profitability, credit history, and collateral when evaluating eligibility for a business line of credit.

    What documentation is required during the application process?

    Commonly required documents include financial statements, tax returns, business plan, and personal financial statements of the business owners.

    What are the advantages of using a business line of credit?

    Business lines of credit offer flexibility, as businesses can access funds as needed without having to reapply for a loan each time. They also provide a lower cost of borrowing compared to other short-term financing options.

  • Business Capital Loans: The Cornerstone of Business Growth

    Business Capital Loans: The Cornerstone of Business Growth

    In the vibrant landscape of business, capital loans emerge as a beacon of growth, empowering entrepreneurs and business owners to transcend boundaries and seize opportunities. As we delve into the intricacies of business capital loans, we embark on a journey that unveils the power to unlock financial potential and propel businesses towards unprecedented heights.

    Capital loans, the lifeblood of businesses, provide the necessary fuel for expansion, innovation, and strategic acquisitions. They serve as a catalyst for businesses to amplify their impact, optimize operations, and establish a solid foundation for long-term success.

    Understanding Business Capital Loans

    Business capital loans are a form of financing specifically designed to meet the capital needs of businesses. They provide businesses with the necessary funds to invest in growth, expand operations, or cover unexpected expenses.

    There are several key benefits to obtaining a business capital loan. Firstly, they provide businesses with access to capital that may not be readily available through other sources, such as personal savings or traditional bank loans. Secondly, capital loans can help businesses improve their cash flow by providing them with the funds to cover expenses or invest in new opportunities.

    Thirdly, they can help businesses grow and expand by providing the necessary capital to purchase equipment, hire staff, or enter new markets.

    Types of Business Capital Loans

    There are various types of business capital loans available, each with its own unique features and benefits. Some of the most common types include:

    • Term Loans:These are traditional loans with fixed repayment terms and interest rates. They are typically used for large capital expenditures, such as purchasing equipment or real estate.
    • Lines of Credit:These are revolving loans that allow businesses to borrow up to a certain amount of money as needed. They are typically used for short-term working capital needs, such as covering payroll or purchasing inventory.
    • Equipment Loans:These are loans specifically designed to finance the purchase of equipment. They typically have lower interest rates than other types of loans and can be tailored to the specific needs of the business.
    • Invoice Factoring:This involves selling unpaid invoices to a factoring company in exchange for immediate cash. It can be a good option for businesses that have a high volume of outstanding invoices.

    Examples of Business Capital Loan Usage

    Businesses use capital loans for a wide range of purposes, including:

    • Purchasing Equipment:Capital loans can be used to purchase equipment, such as machinery, vehicles, or computers, that is essential for business operations.
    • Expanding Operations:Capital loans can be used to finance the expansion of business operations, such as opening new locations or hiring additional staff.
    • Covering Expenses:Capital loans can be used to cover unexpected expenses, such as repairs or legal fees, that may arise during the course of business.
    • Investing in Growth:Capital loans can be used to invest in growth initiatives, such as marketing campaigns or product development, that can help the business grow and expand.

    Applying for Business Capital Loans

    Applying for a business capital loan is a crucial step in securing funding for your business. Understanding the process and requirements can increase your chances of loan approval.

    The application process typically involves several steps, including submitting a loan application, providing financial documentation, and undergoing a credit check.

    Required Documentation

    When applying for a business capital loan, you will typically need to provide the following documentation:

    • Business plan
    • Financial statements (balance sheet, income statement, cash flow statement)
    • Tax returns
    • Personal financial statement
    • Business license and permits

    Tips for Loan Approval

    To increase your chances of loan approval, consider the following tips:

    • Have a strong business plan that Artikels your business goals, strategies, and financial projections.
    • Maintain good credit history and a high credit score.
    • Provide complete and accurate financial documentation.
    • Be prepared to answer questions about your business and financial situation.
    • Consider working with a loan broker who can guide you through the process and help you find the best loan options.

    Evaluating Business Capital Loan Options

    Selecting the most suitable business capital loan option is crucial for your business’s financial health. Here are key factors to consider when evaluating your options:

    Interest Rates

    Interest rates significantly impact your loan’s total cost. Compare interest rates offered by different lenders, considering both fixed and variable rates. Fixed rates provide stability, while variable rates may fluctuate with market conditions.

    Loan Terms

    Loan terms determine the duration of your loan and the frequency of repayments. Consider the length of time you need to repay the loan and whether you prefer monthly, quarterly, or annual payments.

    Fees

    Various fees may be associated with business capital loans, including application fees, origination fees, and prepayment penalties. Be aware of these fees and factor them into your evaluation.

    Comparison Table

    To simplify your evaluation, consider using a comparison table that lists the key features of different loan options. This table should include information on interest rates, loan terms, fees, and any additional features or benefits offered by each lender.

    Lender Interest Rate Loan Term Fees Additional Features
    Lender A 5% fixed 5 years $500 application fee Online application, flexible repayment options
    Lender B 4.5% variable 3 years $250 origination fee Prepayment penalty, dedicated account manager
    Lender C 6% fixed 7 years No fees Longer loan term, lower monthly payments

    Using Business Capital Loans Effectively

    Business capital loans

    Utilizing business capital loans strategically is crucial for maximizing their impact. Prudent allocation of funds, combined with careful planning and execution, ensures that businesses derive optimal value from these loans.

    Best Practices for Allocating Funds

    The effective allocation of funds from business capital loans entails a thorough understanding of the business’s needs and growth objectives. Key considerations include:

    • Capital Expenditures:Invest in tangible assets such as equipment, machinery, or property to enhance operational efficiency and capacity.
    • Inventory:Increase inventory levels to meet growing demand, optimize supply chains, and reduce lead times.
    • Marketing and Sales:Allocate funds to marketing campaigns, sales initiatives, and customer acquisition strategies to expand the customer base.
    • Research and Development:Invest in research and development to develop new products, improve existing ones, and gain a competitive edge.
    • Debt Repayment:Utilize loan proceeds to consolidate high-interest debt or refinance existing loans, reducing overall interest expenses and improving cash flow.

    Case Studies of Successful Loan Utilization

    Numerous businesses have achieved significant growth and success by effectively utilizing business capital loans. Notable examples include:

    • Case Study 1:A manufacturing company used a loan to purchase state-of-the-art machinery, increasing production capacity by 25% and reducing production costs.
    • Case Study 2:A retail chain invested in inventory to expand its product offerings, resulting in a 15% increase in sales revenue.
    • Case Study 3:A technology startup used a loan to fund marketing and sales campaigns, acquiring over 100 new clients and doubling its annual revenue.

    Alternative Financing Options

    Loans

    Businesses that do not qualify for traditional business capital loans may consider alternative financing options. These options can provide access to capital, but they may come with higher interest rates and fees.

    Crowdfunding

    Crowdfunding platforms allow businesses to raise funds from a large number of individual investors. This can be a good option for businesses with a strong online presence and a compelling story to tell.

    Pros:

    • Can reach a large number of potential investors
    • Can be a good way to build brand awareness

    Cons:

    • Can be time-consuming and expensive
    • May not be successful in raising the desired amount of funds

    Examples:Kickstarter, Indiegogo, GoFundMe

    Peer-to-Peer Lending, Business capital loans

    Peer-to-peer lending platforms connect businesses with individual investors who are willing to lend money. This can be a good option for businesses with good credit and a strong track record.

    Pros:

    • Can be a more affordable option than traditional loans
    • Can be a good way to build relationships with investors

    Cons:

    • May not be available to all businesses
    • Can be time-consuming to apply for

    Examples:LendingClub, Prosper, Upstart

    Invoice Factoring

    Invoice factoring is a type of financing that allows businesses to sell their unpaid invoices to a factoring company. This can be a good option for businesses that have a lot of outstanding invoices and need access to cash quickly.

    Pros:

    • Can provide quick access to cash
    • Can help businesses improve their cash flow

    Cons:

    • Can be expensive
    • Can damage relationships with customers

    Examples:FactorOne, Triumph Business Capital, First American

    Epilogue: Business Capital Loans

    Business capital loans

    As we conclude our exploration of business capital loans, we are left with a profound appreciation for their transformative power. By carefully evaluating loan options, implementing best practices, and exploring alternative financing avenues, businesses can harness the potential of capital loans to achieve their aspirations and shape the future of their ventures.

    May this knowledge empower you to make informed decisions and unlock the gateway to business growth.

    FAQ Guide

    What are the key factors to consider when evaluating business capital loan options?

    When evaluating business capital loan options, it is crucial to assess factors such as interest rates, loan terms, fees, repayment schedules, and the lender’s reputation.

    What are some best practices for using business capital loans effectively?

    To maximize the impact of business capital loans, allocate funds strategically, invest in revenue-generating activities, monitor cash flow diligently, and consider refinancing options when appropriate.

    What are some alternative financing options for businesses that may not qualify for traditional business capital loans?

    Alternative financing options include crowdfunding, invoice financing, merchant cash advances, equipment financing, and lines of credit, each with its own advantages and considerations.

  • Unveiling the Best Working Capital Loans: A Comprehensive Guide for Business Success

    Unveiling the Best Working Capital Loans: A Comprehensive Guide for Business Success

    In the ever-evolving business landscape, access to working capital is paramount. Our in-depth guide, “Unveiling the Best Working Capital Loans,” empowers entrepreneurs and business leaders with the knowledge and insights necessary to navigate the complexities of securing funding for their operations.

    Join us as we explore the top providers, types of loans, eligibility criteria, application processes, and effective management strategies, all presented with vivid imagery and engaging prose.

    From the initial stages of loan exploration to the intricacies of loan management, this guide serves as an indispensable resource, empowering businesses to optimize their cash flow, fuel growth, and achieve financial stability.

    Best Working Capital Loan Providers

    Best working capital loans

    Finding the right working capital loan provider is crucial for businesses seeking to bridge short-term cash flow gaps. To help you make an informed decision, we’ve compiled a comprehensive list of the top working capital loan providers, each offering unique features and terms tailored to specific business needs.

    Consider factors such as loan amounts, interest rates, repayment terms, application processes, and customer support when comparing providers. Some lenders may specialize in small business loans, while others cater to larger enterprises. Understanding the advantages and disadvantages of each provider will empower you to select the one that aligns best with your business’s financial requirements.

    Top Working Capital Loan Providers

    1. Fundbox: Offers fast and flexible loans up to $150,000 with repayment terms of 12 to 24 weeks. Known for its simple application process and quick approvals.
    2. BlueVine: Provides working capital loans up to $250,000 with competitive interest rates and repayment terms of 6 to 12 months. Features an online platform for easy loan management.
    3. Kabbage: Offers lines of credit up to $250,000 with flexible repayment options. Known for its advanced technology and automated underwriting process.
    4. Lendio: Connects businesses with multiple lenders, providing a wide range of loan options and repayment terms. Simplifies the loan application process by matching businesses with suitable lenders.
    5. OnDeck: Specializes in small business loans up to $500,000 with repayment terms of 3 to 36 months. Offers various loan products, including term loans and lines of credit.

    Types of Working Capital Loans

    Loan

    Working capital loans are designed to provide businesses with the necessary funds to meet their short-term financial obligations, such as inventory purchases, payroll, and operating expenses. There are several types of working capital loans available, each with its unique characteristics, benefits, and drawbacks.

    Term loans are a type of working capital loan that provides a lump sum of money to the business. The loan is typically repaid over a fixed period of time, with regular payments of principal and interest. Term loans are a good option for businesses that need a large amount of capital for a specific project or expansion.

    However, they can be more expensive than other types of working capital loans, and the business may have to provide collateral to secure the loan.

    Lines of credit are another type of working capital loan that provides the business with access to a pool of money that can be drawn on as needed. The business only pays interest on the amount of money that is actually used.

    Lines of credit are a good option for businesses that need flexible access to capital, but they can be more expensive than term loans and may require the business to maintain a certain balance in the account.

    Invoice financing is a type of working capital loan that allows businesses to borrow money against their outstanding invoices. The lender advances the business a percentage of the invoice amount, and the business repays the loan when the invoice is paid.

    Invoice financing is a good option for businesses that have a large number of outstanding invoices, but it can be more expensive than other types of working capital loans and may require the business to provide collateral.

    Eligibility Criteria for Working Capital Loans: Best Working Capital Loans

    Obtaining a working capital loan is contingent upon meeting specific eligibility criteria set by lenders. These criteria assess the financial health and stability of your business, ensuring its ability to repay the loan. Understanding these requirements is crucial for increasing your chances of loan approval.

    Typically, lenders consider the following factors when evaluating loan applications:

    Business Revenue

    Your business revenue serves as a primary indicator of its earning capacity. Lenders analyze revenue trends to assess the stability and growth potential of your business. A consistent revenue stream demonstrates your ability to generate sufficient cash flow to repay the loan.

    Profitability

    Profitability measures the financial performance of your business. Lenders examine profit margins and net income to determine your business’s profitability. A profitable business indicates that it is generating revenue in excess of its expenses, enhancing its capacity to service debt obligations.

    Credit History

    Your credit history reflects your track record of managing debt. Lenders assess your credit score and report to evaluate your creditworthiness. A strong credit history demonstrates your reliability in meeting financial obligations, making you a more favorable candidate for loan approval.

    Other Factors

    • Business Plan:A well-crafted business plan Artikels your business goals, strategies, and financial projections. It provides lenders with insights into your business’s direction and growth potential.
    • Collateral:Some lenders may require collateral, such as equipment or real estate, to secure the loan. Providing collateral reduces the risk for lenders, increasing your chances of loan approval.
    • Industry Experience:Lenders prefer businesses with experienced management teams and a proven track record in their industry. Industry knowledge and expertise enhance the likelihood of business success and loan repayment.

    Application Process for Working Capital Loans

    Obtaining a working capital loan involves a standardized application process designed to assess the borrower’s financial health and creditworthiness. Understanding the steps and requirements can help streamline the process and increase the chances of approval.

    The application process typically begins with gathering the necessary documentation, including financial statements, tax returns, and business plans. Lenders will use these documents to evaluate the borrower’s financial performance, stability, and growth potential.

    Document Requirements

    The specific document requirements may vary depending on the lender and the loan amount. However, common documents include:

    • Business financial statements (balance sheet, income statement, cash flow statement)
    • Personal financial statements (if applicable)
    • Tax returns
    • Business plan
    • Collateral (if required)

    Underwriting Procedures

    Once the necessary documents have been submitted, the lender will conduct an underwriting process to assess the borrower’s creditworthiness. This process involves analyzing the borrower’s financial history, credit score, and other factors to determine the risk of default.

    The underwriting process may include the following steps:

    • Credit check
    • Financial ratio analysis
    • Cash flow analysis
    • Collateral evaluation (if applicable)

    Approval Timelines

    The approval timeline for working capital loans can vary depending on the lender, the loan amount, and the complexity of the application. However, most lenders aim to provide a decision within a few weeks of receiving the completed application.

    Common Challenges

    While the application process for working capital loans is generally straightforward, there are some common challenges that borrowers may face:

    • Insufficient documentation:Failure to provide all the required documentation can delay the application process.
    • Weak financial performance:Lenders are more likely to approve loans to borrowers with strong financial performance and a track record of profitability.
    • Low credit score:A low credit score can make it more difficult to qualify for a working capital loan and may result in higher interest rates.

    Tips for Overcoming Challenges

    To overcome these challenges, borrowers can take the following steps:

    • Gather all necessary documentation:Ensure that all the required documents are complete and organized before submitting the application.
    • Improve financial performance:Take steps to improve the business’s financial performance, such as increasing sales, reducing expenses, and managing cash flow effectively.
    • Build credit history:Establish a strong credit history by making timely payments on existing debts and avoiding excessive borrowing.

    By understanding the application process, gathering the necessary documentation, and addressing potential challenges, borrowers can increase their chances of obtaining a working capital loan to meet their business needs.

    Managing Working Capital Loans Effectively

    Best working capital loans

    Managing working capital loans effectively requires a combination of financial discipline and strategic planning. By optimizing cash flow, controlling expenses, and monitoring loan covenants, businesses can maximize the benefits of working capital loans while minimizing the associated risks.

    Optimizing Cash Flow

    Cash flow is the lifeblood of any business. To optimize cash flow, businesses should:

    • Invoice promptly:Send invoices as soon as possible after completing work or delivering goods.
    • Offer early payment discounts:Encourage customers to pay early by offering discounts for prompt payment.
    • Manage inventory efficiently:Keep inventory levels low to reduce carrying costs and improve cash flow.
    • Negotiate extended payment terms with suppliers:Extend payment terms with suppliers to free up cash flow.

    Controlling Expenses

    Controlling expenses is crucial for managing working capital loans effectively. Businesses should:

    • Review expenses regularly:Identify areas where expenses can be reduced or eliminated.
    • Negotiate with vendors:Negotiate lower prices or discounts with vendors.
    • Outsource non-core functions:Outsource non-core functions to reduce labor costs.
    • Implement cost-saving initiatives:Implement initiatives such as energy efficiency measures or process improvements to reduce operating costs.

    Monitoring Loan Covenants

    Loan covenants are restrictions imposed by lenders to protect their interests. Businesses should:

    • Understand loan covenants:Carefully review and understand all loan covenants.
    • Monitor compliance:Track financial performance regularly to ensure compliance with covenants.
    • Communicate with lenders:Keep lenders informed of any potential covenant breaches or financial difficulties.
    • Negotiate covenant modifications:If necessary, negotiate with lenders to modify loan covenants to avoid default.

    Potential Risks Associated with Working Capital Loans

    Working capital loans come with potential risks that businesses should be aware of:

    • Interest payments:Working capital loans accrue interest, which can increase the cost of borrowing.
    • Covenants and restrictions:Loan covenants can restrict a business’s financial flexibility and operations.
    • Default risk:Failure to comply with loan covenants or repay the loan on time can lead to default and severe consequences.

    Strategies for Mitigating Risks, Best working capital loans

    Businesses can mitigate the risks associated with working capital loans by:

    • Carefully assessing financial needs:Determine the exact amount of working capital needed to avoid excessive borrowing.
    • Negotiating favorable loan terms:Negotiate with lenders to secure the best possible loan terms, including interest rates, repayment schedules, and covenants.
    • Maintaining financial discipline:Implement sound financial management practices to ensure compliance with loan covenants and avoid default.
    • Seeking professional advice:Consult with financial advisors or accountants to ensure that working capital loans are used effectively and managed prudently.

    Final Summary

    As we conclude our exploration of the best working capital loans, it is evident that the key to unlocking financial success lies in a comprehensive understanding of the available options and a strategic approach to loan management. By leveraging the insights and guidance provided in this guide, businesses can confidently navigate the lending landscape, secure the necessary funding, and propel their operations to new heights.

    Question & Answer Hub

    What are the primary benefits of working capital loans?

    Working capital loans provide businesses with immediate access to funds, enabling them to meet short-term obligations, such as inventory purchases, payroll expenses, and operational costs. They offer flexibility, as businesses can borrow only what they need, and they can help businesses avoid dipping into their cash reserves or taking on long-term debt.

    How do I improve my chances of qualifying for a working capital loan?

    To improve your chances of qualifying for a working capital loan, it is crucial to maintain a strong business credit score, provide detailed financial statements, and demonstrate a clear plan for how you will use the loan proceeds. Additionally, having a solid track record of profitability and positive cash flow can enhance your application.

    What are the potential risks associated with working capital loans?

    Working capital loans can pose risks if not managed effectively. These risks include high interest rates, short repayment terms, and the potential for default. It is essential to carefully consider the terms of the loan and ensure that your business can comfortably meet the repayment obligations.

  • Fast Business Loan: The Ultimate Guide to Securing Quick Funding

    Fast Business Loan: The Ultimate Guide to Securing Quick Funding

    In today’s fast-paced business world, time is of the essence. That’s why fast business loans have become increasingly popular, providing entrepreneurs with the quick funding they need to seize opportunities and drive growth. In this comprehensive guide, we’ll delve into the world of fast business loans, exploring the different types available, the application process, and strategies for effective utilization.

    Whether you’re looking to expand your operations, invest in new equipment, or manage unexpected expenses, a fast business loan can provide the financial flexibility you need to succeed.

    Business Loan Types

    Navigating the world of fast business loans can be daunting, given the plethora of options available. Each loan type caters to specific business needs, offering varying features, benefits, and eligibility criteria. Understanding these nuances is crucial for making an informed decision that aligns with your financial goals.

    Let’s delve into the key business loan types, exploring their characteristics and suitability for different scenarios:

    Short-Term Loans

    Short-term loans, typically ranging from a few days to a year, provide a quick influx of capital for immediate business expenses or emergencies. These loans often have higher interest rates but offer flexible repayment terms.

    Long-Term Loans

    Long-term loans extend over several years, offering larger loan amounts and lower interest rates. They are suitable for major investments, such as equipment purchases, property acquisition, or business expansion.

    Line of Credit

    A line of credit is a flexible financing option that allows businesses to borrow up to a predetermined limit as needed. Interest is charged only on the amount borrowed, providing greater financial flexibility.

    Invoice Financing

    Invoice financing provides businesses with an advance on unpaid invoices, bridging the gap between invoice issuance and payment. This option helps maintain cash flow during periods of high accounts receivable.

    Equipment Financing

    Equipment financing is tailored to businesses seeking to acquire essential equipment or machinery. The equipment itself serves as collateral, often resulting in lower interest rates and longer repayment terms.

    SBA Loans

    SBA loans, backed by the Small Business Administration, offer favorable terms and low interest rates to qualifying small businesses. They require a strong credit history and a well-defined business plan.

    Merchant Cash Advance

    Merchant cash advances provide businesses with a lump sum in exchange for a percentage of future sales. This option is suitable for businesses with predictable cash flow from card transactions.

    Fast Loan Application Process

    Applying for a fast business loan is designed to be a straightforward and efficient process. Here’s a step-by-step guide to help you navigate the application journey:

    Step 1: Online Application

    The first step is to initiate the application process online through the lender’s website. The online application typically requires basic information about your business, such as its legal structure, industry, revenue, and loan amount.

    Step 2: Documentation Submission

    Once you have submitted the initial application, the lender will request supporting documentation to verify your business’s financial health and creditworthiness. This may include:

    • Business financial statements (balance sheet, income statement, cash flow statement)
    • Personal financial statements (if required)
    • Tax returns
    • Business license and permits

    Step 3: Credit Check

    The lender will perform a credit check to assess your business’s credit history and score. This helps them determine your creditworthiness and the loan terms you qualify for.

    Step 4: Approval and Funding

    Based on the submitted information and credit check, the lender will make a decision on your loan application. If approved, the loan amount will be disbursed into your business account within a few days.

    Loan Comparison and Selection

    Business quick loan might times need biz2credit osterling sam

    Choosing the right fast business loan can make a significant impact on your business’s financial health. To ensure you make an informed decision, it’s crucial to compare different loan providers and select the option that best aligns with your needs.

    Here are key factors to consider when comparing fast business loans:

    Interest Rates and Fees

    Interest rates and fees vary among lenders. High interest rates can increase your borrowing costs, while excessive fees can erode your profits. Compare the annual percentage rate (APR), which includes both interest and fees, to get a comprehensive view of the loan’s cost.

    Loan Terms

    Loan terms determine the repayment period and monthly payments. Shorter loan terms typically have higher monthly payments but lower overall interest costs. Conversely, longer loan terms result in lower monthly payments but higher total interest paid.

    Approval Times

    Approval times can range from a few hours to several days. If you need funds quickly, consider lenders with fast approval processes. However, don’t compromise on other factors like interest rates or loan terms for the sake of speed.

    Eligibility Criteria

    Different lenders have varying eligibility criteria, such as minimum revenue, credit score, and time in business. Ensure you meet the eligibility requirements before applying for a loan to avoid wasting time and effort.

    Customer Support

    Excellent customer support can make a world of difference when you encounter issues or have questions. Look for lenders with responsive and helpful support teams.

    Loan Comparison Table

    To facilitate your comparison, we’ve created a table that Artikels the key features of different fast business loan providers:

    Lender Interest Rate (APR) Fees Loan Terms Approval Time
    Provider A 10%

    15%

    $250 origination fee 12

    24 months

    2

    3 days

    Provider B 8%

    12%

    $0 origination fee 6

    18 months

    Same day
    Provider C 12%

    18%

    $100 origination fee 12

    36 months

    1

    2 days

    Use this table as a reference when evaluating different loan options. Remember to consider your specific business needs and financial situation to make an informed decision.

    Loan Utilization and Management

    Effective utilization of fast business loan funds is crucial for business growth and expansion. Strategic planning and prudent management of loan payments help mitigate potential financial risks.

    Fund Allocation and Tracking

    • Identify specific areas of investment, such as inventory expansion, equipment upgrades, or marketing campaigns.
    • Establish a detailed budget and track expenses diligently to ensure funds are used efficiently.
    • Consider consulting with financial advisors or business coaches for guidance on optimal fund allocation.

    Loan Repayment Management, Fast business loan

    • Make timely loan payments to avoid penalties and maintain a positive credit history.
    • Explore loan restructuring options, such as refinancing or extending the loan term, if cash flow challenges arise.
    • Create a contingency plan to anticipate and manage unexpected expenses or economic downturns.

    Case Studies and Success Stories

    Fast business loan

    Numerous businesses have reaped the benefits of fast business loans, experiencing positive transformations in their operations, revenue, and overall growth. These case studies showcase the remarkable impact these loans can have on entrepreneurial ventures.

    One notable example is a small manufacturing company that faced a cash flow crunch due to unexpected expenses. With the help of a fast business loan, they were able to purchase new equipment, increase production, and meet growing customer demand.

    This resulted in a significant increase in revenue and allowed the company to expand its operations.

    Enhanced Operations and Productivity

    Fast business loans have enabled businesses to upgrade their infrastructure, acquire state-of-the-art machinery, and implement innovative technologies. These investments have led to increased efficiency, reduced production costs, and improved product quality. The resulting improvements in operations have contributed to increased customer satisfaction and competitive advantage.

    Revenue Growth and Expansion

    The influx of capital from fast business loans has provided businesses with the necessary resources to expand their operations, enter new markets, and launch new products. By seizing growth opportunities, these businesses have experienced substantial increases in revenue and profitability.

    The ability to scale up operations has also created new employment opportunities and contributed to economic growth.

    Financial Stability and Resilience

    Fast business loans have acted as a financial safety net for businesses, particularly during challenging economic times. The quick access to funds has enabled them to navigate unexpected expenses, cover seasonal fluctuations in cash flow, and invest in growth initiatives.

    This financial stability has fostered resilience and allowed businesses to adapt to changing market conditions.

    Wrap-Up: Fast Business Loan

    Fast business loan

    With the right fast business loan and a strategic approach, you can unlock your business’s potential and achieve your financial goals. Remember, time is money, and with a fast business loan, you can seize opportunities and drive growth like never before.

    Key Questions Answered

    What are the eligibility criteria for a fast business loan?

    Eligibility criteria vary depending on the lender, but typically include factors such as your business’s credit score, revenue, and time in operation.

    How long does it take to get approved for a fast business loan?

    Approval times vary, but many lenders offer fast approval within a few hours or days.

    What are the interest rates and fees associated with fast business loans?

    Interest rates and fees vary depending on the lender and your business’s creditworthiness. It’s important to compare different options to find the most competitive rates.

  • Receive Paychecks Up to Two Days Early with Varo Early Direct Deposit

    Receive Paychecks Up to Two Days Early with Varo Early Direct Deposit

    Get ready to experience financial freedom with Varo Early Direct Deposit! This revolutionary feature allows you to access your hard-earned paychecks up to two days sooner, empowering you to take control of your finances like never before.

    Imagine the convenience of having your paycheck in your account before the weekend hits, giving you ample time to plan your expenses, pay your bills, and treat yourself to something special. Varo Early Direct Deposit is not just a service; it’s a game-changer that puts you in the driver’s seat of your financial journey.

    Varo Early Direct Deposit Overview

    Varo Bank offers an Early Direct Deposit feature that allows customers to access their paychecks up to two days earlier than the scheduled payment date. This feature is available to eligible customers who meet certain criteria and complete the setup process.

    Eligibility Criteria

    To be eligible for Varo Early Direct Deposit, customers must meet the following criteria:

    • Have an active Varo Bank account
    • Receive recurring direct deposits from an employer or government agency
    • Have a consistent deposit history
    • Meet Varo Bank’s other eligibility requirements

    Setup Process

    To set up Early Direct Deposit, eligible customers can follow these steps:

    1. Log in to their Varo Bank account
    2. Navigate to the “Direct Deposit” section
    3. Click on the “Early Direct Deposit” option
    4. Follow the on-screen instructions to complete the setup process

    Benefits of Using Varo Early Direct Deposit

    With Varo Early Direct Deposit, you can receive your paychecks up to two days earlier than your regular payday. This can be a major advantage, especially if you’re living paycheck to paycheck or have unexpected expenses. Here are some of the benefits of using Varo Early Direct Deposit:

    • More time to plan and budget.When you receive your paycheck early, you have more time to plan your budget and make sure your bills are paid on time. This can help you avoid overdraft fees and other financial penalties.
    • Less stress.Knowing that you have your paycheck in the bank early can give you peace of mind and reduce financial stress. This can be especially helpful if you have a lot of expenses or are worried about making ends meet.
    • More financial freedom.When you have your paycheck early, you can use it to take advantage of sales, discounts, and other opportunities that may not be available later in the month. This can help you save money and get ahead financially.

    Customer Testimonials

    Here are some testimonials from Varo customers who have benefited from using Early Direct Deposit:

    “I love Varo Early Direct Deposit! It’s so convenient to get my paycheck two days early. It gives me more time to plan my budget and make sure my bills are paid on time.”

    Sarah J.

    “I’m so grateful for Varo Early Direct Deposit. It’s helped me avoid overdraft fees and other financial penalties. I highly recommend it to anyone who wants to get ahead financially.”

    John D.

    Comparison with Other Early Direct Deposit Services: Varo Early Direct Deposit

    Varo’s early direct deposit service offers several advantages over similar offerings from other banks and financial institutions. One key advantage is that Varo does not charge any fees for early direct deposit, while some other providers may charge a monthly fee or a per-deposit fee.

    Another advantage of Varo’s early direct deposit service is that it is available to all Varo account holders, regardless of their account balance or direct deposit frequency. Some other providers may only offer early direct deposit to customers who meet certain criteria, such as maintaining a minimum account balance or receiving a certain number of direct deposits per month.

    However, one potential drawback of Varo’s early direct deposit service is that it may not be as widely accepted as early direct deposit services from larger banks. This means that some employers or government agencies may not be able to send early direct deposits to Varo accounts.

    Key Differences and Similarities between Varo and its Competitors

    Feature Varo Other Providers
    Fees No fees May charge a monthly fee or a per-deposit fee
    Availability Available to all Varo account holders May only be available to customers who meet certain criteria
    Acceptance May not be as widely accepted as early direct deposit services from larger banks Generally widely accepted

    Security and Reliability of Varo Early Direct Deposit

    Varo

    Varo is committed to the safety and reliability of its early direct deposit service. The company employs industry-leading security measures to protect customer funds, including encryption, fraud detection systems, and multi-factor authentication.

    Security Measures

    Varo uses bank-grade encryption to protect customer data and transactions. All information is encrypted both in transit and at rest, ensuring that it remains confidential and secure. Additionally, Varo has implemented robust fraud detection systems to monitor transactions for suspicious activity and prevent unauthorized access to accounts.

    Reliability

    Varo’s early direct deposit service has a proven track record of reliability. Customers consistently receive their funds on time, even before the scheduled payday. Varo partners with trusted financial institutions to ensure seamless and timely delivery of funds.

    Customer Testimonials

    Numerous customers have expressed their satisfaction with the security and dependability of Varo’s early direct deposit service:

    “I’ve been using Varo for over a year now and I’ve never had any problems with my direct deposit. The funds always arrive on time and I feel confident that my money is safe.”

    John Smith, Varo customer

    “I switched to Varo because I needed a reliable way to get my paycheck early. Varo has never let me down. I always receive my funds on time and the service is secure.”

    Mary Johnson, Varo customer

    Alternatives to Varo Early Direct Deposit

    Varo early direct deposit

    While Varo Early Direct Deposit is a convenient and reliable way to access your paycheck early, there are other options available. These alternatives may offer different benefits and drawbacks, so it’s important to consider which one is right for you.

    Payroll Advance Services

    Payroll advance services allow you to borrow against your future paycheck. You typically need to provide proof of employment and income, and the amount you can borrow is usually limited to a percentage of your paycheck. The fees associated with payroll advance services can vary, so it’s important to compare different providers before signing up.

    Negotiating with Your Employer

    If you have a good relationship with your employer, you may be able to negotiate an earlier payday. This can be a simple and effective way to get access to your money sooner, but it’s important to be aware that your employer may not be willing or able to accommodate your request.

    Comparison of Alternatives, Varo early direct deposit

    The following table summarizes the key differences and similarities between Varo Early Direct Deposit and other alternatives:

    Feature Varo Early Direct Deposit Payroll Advance Services Negotiating with Your Employer
    Availability Available to Varo bank account holders Available through third-party providers Depends on your employer’s policies
    Fees None May vary depending on the provider None
    Amount you can access Up to 100% of your paycheck Typically limited to a percentage of your paycheck Depends on your agreement with your employer
    Speed Receive your paycheck up to 2 days early Can receive funds within hours May take several days to receive your paycheck
    Convenience Easy to set up and use May require additional paperwork and verification May require negotiation with your employer

    Last Point

    Varo early direct deposit

    With Varo Early Direct Deposit, you’ll never have to worry about unexpected expenses or late fees again. Embrace financial flexibility and peace of mind today! Join the thousands of satisfied customers who have already experienced the transformative power of Varo Early Direct Deposit.

    It’s time to unlock a new level of financial freedom and start living life on your terms.

    Questions Often Asked

    How do I set up Varo Early Direct Deposit?

    Setting up Varo Early Direct Deposit is a breeze! Simply provide your employer with your Varo account and routing numbers, and they’ll take care of the rest. You’ll start receiving your paychecks up to two days earlier, without any hassle.

    Is Varo Early Direct Deposit secure?

    Absolutely! Varo employs industry-leading security measures to protect your funds. Your money is safe and secure, so you can rest easy knowing that your hard-earned paycheck is in good hands.

    Are there any fees associated with Varo Early Direct Deposit?

    No, Varo Early Direct Deposit is completely free to use. There are no hidden fees or charges, so you can enjoy the benefits of receiving your paycheck early without breaking the bank.

  • New Small Business Insurance: The Essential Guide to Protecting Your Enterprise

    New Small Business Insurance: The Essential Guide to Protecting Your Enterprise

    New small business insurance is a crucial investment for any entrepreneur looking to safeguard their enterprise against unforeseen risks. With a myriad of coverage options available, understanding the intricacies of business insurance is paramount to ensuring adequate protection and minimizing financial losses.

    This comprehensive guide delves into the essential aspects of new small business insurance, empowering you to make informed decisions and choose the optimal coverage for your unique business needs.

    Business Insurance Overview

    Business insurance provides a safety net for small businesses, protecting them from financial losses resulting from unexpected events and liabilities. It’s a crucial investment that helps safeguard the business’s assets, operations, and reputation.

    Common risks covered by business insurance include property damage, liability claims, business interruption, and employee injuries. It’s essential to assess the specific risks faced by your business and tailor an insurance policy that meets your needs.

    Types of Business Insurance

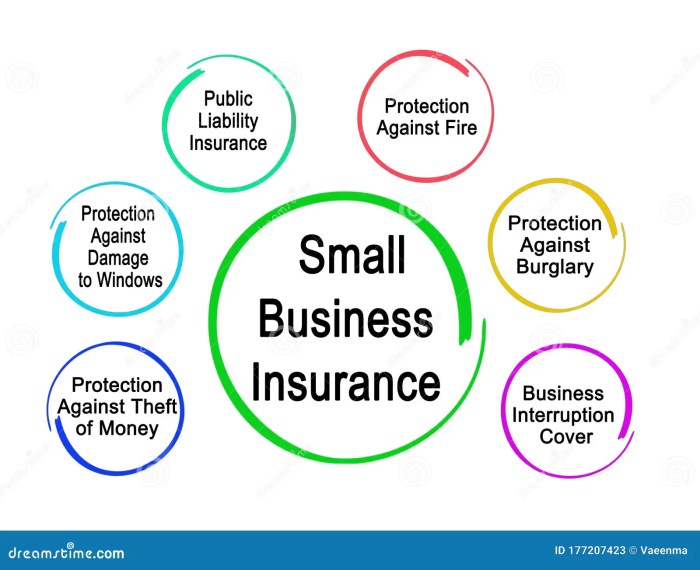
    Various types of business insurance are available, each designed to address specific risks:

    • Property Insurance:Covers damage or loss to business property, including buildings, equipment, and inventory.
    • Liability Insurance:Protects the business from legal claims arising from injuries or damages caused to third parties.
    • Business Interruption Insurance:Provides coverage for lost income and expenses incurred during a business interruption caused by an insured event.
    • Workers’ Compensation Insurance:Covers medical expenses and lost wages for employees injured on the job.
    • Cyber Liability Insurance:Protects the business from financial losses resulting from data breaches, cyberattacks, and other technology-related incidents.

    Coverage and Exclusions

    Business insurance policies provide a comprehensive safety net for small businesses, safeguarding them against potential financial losses and liabilities. Understanding the coverage and exclusions of these policies is crucial for making informed decisions and ensuring adequate protection.

    Essential coverages included in a new small business insurance policy typically encompass:

    • General liability insurance:Protects against claims of bodily injury, property damage, and personal injury.
    • Property insurance:Covers physical assets such as buildings, equipment, and inventory in case of damage or loss due to fire, theft, or natural disasters.
    • Business interruption insurance:Provides coverage for lost income and expenses if business operations are disrupted due to covered events.
    • li> Commercial auto insurance:Protects vehicles used for business purposes against accidents, collisions, and other liabilities.

    While these coverages provide a solid foundation, it’s important to be aware of common exclusions and limitations in business insurance policies. These may include:

    • Intentional acts:Coverage typically excludes damages resulting from deliberate or intentional actions by the policyholder.
    • Acts of war or terrorism:Most policies do not cover losses caused by war, terrorism, or other acts of violence.
    • Employee dishonesty:While some policies offer coverage for employee theft or fraud, it may be subject to specific conditions and limitations.
    • Professional liability:This coverage is not typically included in standard business insurance policies and requires separate coverage for businesses providing professional services.

    Customizing coverage to meet specific business needs is essential. By understanding the coverage and exclusions of business insurance policies, small businesses can tailor their protection to align with their unique risks and exposures. This proactive approach ensures adequate coverage and peace of mind, allowing businesses to focus on their operations without the burden of unforeseen financial losses.

    Cost and Premiums

    The cost of business insurance premiums is determined by a range of factors, including the type of business, its size, location, and risk profile. Understanding these factors can help businesses optimize their insurance coverage while minimizing costs.

    Key factors influencing premium costs include:

    • Industry and Occupation:Businesses in high-risk industries, such as construction or manufacturing, typically pay higher premiums than those in lower-risk sectors.
    • Business Size:Larger businesses generally face higher premiums due to increased potential for losses.
    • Location:Premiums can vary based on the location of the business, considering factors such as crime rates and natural disaster risks.
    • Claims History:Businesses with a history of claims may experience higher premiums, as insurers assess the likelihood of future claims.
    • Deductibles:Choosing a higher deductible can lower premiums, but it also increases the out-of-pocket expenses in the event of a claim.

    Strategies for Reducing Insurance Costs, New small business insurance

    Businesses can explore several strategies to reduce their insurance costs:

    • Shop Around:Comparing quotes from multiple insurance providers can help businesses find the most competitive rates.
    • Increase Deductibles:Raising the deductible can significantly lower premiums, but it’s essential to ensure the business can afford the higher out-of-pocket costs.
    • Improve Risk Management:Implementing measures to reduce risks, such as installing security systems or training employees on safety protocols, can lower premiums.
    • Negotiate with Insurers:Businesses with a good claims history and strong financial standing may be able to negotiate lower premiums with their insurers.

    Claims Process

    New small business insurance

    Filing a business insurance claim involves several steps to ensure a smooth and efficient process. Understanding the required documentation and the timeframe for claim processing can help businesses navigate this process effectively.

    To initiate a claim, policyholders should promptly notify their insurance provider of the incident. The insurance company will assign a claims adjuster to guide the policyholder through the process and assess the damages.

    Required Documentation

    To support a claim, policyholders typically need to provide the following documentation:

    • Proof of loss, such as a police report, medical records, or repair estimates
    • Policy number and insurance card
    • Contact information for witnesses or other parties involved
    • Financial records to substantiate the claimed losses

    Timeframe for Claim Processing

    The timeframe for claim processing varies depending on the complexity of the claim and the insurance company’s procedures. However, policyholders can expect the following general timeline:

    1. Initial claim reporting: Within 24-48 hours
    2. Claims adjuster assignment: Within 1-3 business days
    3. Investigation and documentation gathering: 1-2 weeks
    4. Claim settlement: 30-60 days or longer for complex claims

    During the claim process, policyholders should maintain open communication with their claims adjuster and provide timely updates on the status of the claim.

    Selecting an Insurance Provider

    New small business insurance

    Choosing the right insurance provider is crucial for ensuring you have the coverage you need at a price you can afford. Here are some key factors to consider when making your decision:

    • Financial stability:Make sure the insurance company you choose is financially stable and has a good track record of paying claims.
    • Coverage options:Compare the coverage options offered by different insurance providers to find the one that best meets your needs.
    • Customer service:Look for an insurance provider with a reputation for providing excellent customer service.
    • Cost:Get quotes from multiple insurance providers to compare costs and find the best deal.

    Benefits of Working with an Insurance Broker

    An insurance broker can help you find the right insurance coverage for your business. They can also negotiate the best possible rates on your behalf. Here are some of the benefits of working with an insurance broker:

    • Expertise:Insurance brokers are experts in the insurance industry and can help you understand your coverage options.
    • Access to multiple insurance companies:Insurance brokers have access to multiple insurance companies, so they can compare quotes and find the best coverage for your needs.
    • Negotiation skills:Insurance brokers have the negotiation skills to get you the best possible rates on your insurance.
    • Ongoing support:Insurance brokers can provide ongoing support and advice as your business changes.

    Tips for Negotiating the Best Possible Coverage and Rates

    Here are some tips for negotiating the best possible coverage and rates on your business insurance:

    • Be prepared:Gather all of your financial information and insurance needs before you start negotiating.
    • Shop around:Get quotes from multiple insurance providers to compare costs and coverage.
    • Negotiate:Don’t be afraid to negotiate with your insurance provider. You may be able to get a better deal on your coverage.
    • Be patient:Negotiating the best possible coverage and rates can take time. Don’t get discouraged if you don’t get the best deal right away.

    Closing Notes

    Due broker ruth

    Navigating the complexities of new small business insurance can be daunting, but with the right knowledge and guidance, you can secure your enterprise against potential threats. By carefully considering the coverage options, understanding the exclusions, and selecting a reputable insurance provider, you can ensure that your business is well-protected and poised for success.

    Common Queries: New Small Business Insurance

    What are the key benefits of new small business insurance?

    New small business insurance provides a safety net against financial losses resulting from unforeseen events, such as property damage, liability claims, and business interruptions. It offers peace of mind and allows you to focus on growing your business without the fear of financial ruin.

    How much does new small business insurance cost?

    The cost of new small business insurance varies depending on factors such as the industry, location, coverage limits, and deductible. It’s advisable to compare quotes from multiple insurance providers to find the best coverage at an affordable price.

    What are the common exclusions in new small business insurance policies?

    Common exclusions include intentional acts, criminal activities, and certain types of professional liability. It’s important to carefully review the policy exclusions to ensure that your business is adequately protected.

  • Add Money to Chime Card: Effortless Funding for Financial Freedom

    Add Money to Chime Card: Effortless Funding for Financial Freedom

    Add money to chime card – With the Chime card, adding money has never been easier. Discover the seamless ways to fund your account, empowering you with financial control and convenience. From direct deposits to mobile check deposits, this guide will unravel the options available, ensuring you make the most of your Chime card experience.

    Dive into the Chime mobile app’s intuitive features that revolutionize money management. Track expenses, set budgets, and transfer funds with ease. Learn how to maximize the app’s capabilities, gaining unparalleled financial clarity and control.

    Methods to Add Money to Chime Card

    Add money to chime card

    Chime offers several convenient methods to add money to your Chime card, providing you with flexibility and ease in managing your finances.

    The available options include direct deposit, mobile check deposit, cash deposit, and bank transfer. Each method has its unique advantages and limitations, which we will explore in detail below.

    Direct Deposit

    Direct deposit is the most common and convenient way to add money to your Chime card. You can arrange for your employer, government agencies, or other entities to deposit funds directly into your Chime account on a regular basis, such as bi-weekly or monthly.

    This method is advantageous as it automates the process of adding money, ensuring that you receive your funds on time without any manual effort. Additionally, direct deposits are typically processed quickly, making the funds available to you almost immediately.

    Mobile Check Deposit

    Chime’s mobile check deposit feature allows you to add money to your card by taking a picture of a physical check using your smartphone’s camera. This eliminates the need to visit a physical bank or ATM, providing convenience and accessibility.

    To use this service, you will need to download the Chime mobile app and follow the on-screen instructions. The app will guide you through the process of capturing the check image, verifying the details, and submitting the deposit.

    It’s important to note that mobile check deposits may take some time to process, typically within 1-2 business days. Additionally, there may be limits on the amount of money you can deposit using this method.

    Cash Deposit

    If you prefer to add cash to your Chime card, you can do so at any Green Dot location, such as a participating retailer or a Green Dot MoneyPak Reload Center.

    To make a cash deposit, you will need to bring your Chime card and the cash you wish to add. The teller will assist you in completing the transaction, which typically involves a small fee. The funds will be added to your Chime account immediately.

    Bank Transfer

    You can also add money to your Chime card through a bank transfer from another bank account. This method involves initiating a transfer from your external bank account to your Chime account using the Chime mobile app or website.

    To set up a bank transfer, you will need to provide the routing number and account number of your external bank account. The transfer process may take 1-3 business days to complete, and there may be fees associated with the transaction, depending on your bank’s policies.

    Mobile App Features for Money Management

    The Chime mobile app empowers users with a suite of features designed to simplify money management. By leveraging these features, individuals can gain control over their finances, track expenses, set budgets, and transfer funds effortlessly.

    Setting Up and Using the App

    To unlock the app’s capabilities, users can download it from the App Store or Google Play. After installation, a straightforward setup process guides them through account creation and linking their Chime card. Once set up, the app’s intuitive interface provides a clear overview of account balances, recent transactions, and upcoming bills.

    Expense Tracking and Budgeting

    The Chime app’s expense tracking feature allows users to categorize and monitor their spending habits. By analyzing this data, they can identify areas where they may need to adjust their spending. Additionally, the app’s budgeting tools enable users to set spending limits for specific categories, ensuring they stay within their financial goals.

    Fund Transfers

    The Chime app facilitates seamless fund transfers between Chime accounts and external bank accounts. Users can initiate transfers directly from the app, eliminating the need for traditional methods such as bank branches or ATMs. This convenience empowers users to manage their finances from anywhere, at any time.

    Maximizing App Capabilities

    • Regularly review the app’s expense tracking data to identify spending patterns and adjust accordingly.
    • Set realistic budgets that align with your financial goals and stick to them.
    • li>Utilize the fund transfer feature to consolidate finances and streamline payments.

    • Explore the app’s additional features, such as direct deposit alerts and savings goals, to further enhance your money management experience.

    Fees and Limits Associated with Chime Card

    Add money to chime card

    Adding money to a Chime card is generally free, but there are some fees and limits to be aware of. Understanding these charges can help you avoid unnecessary expenses and optimize your money management.

    Cash Deposits

    Chime charges a fee of $2.50 for cash deposits made at retail locations, such as Walmart and CVS. This fee is charged by the retailer, not Chime, and it is important to factor it into your budgeting.

    Mobile Check Deposits

    Chime offers mobile check deposits as a convenient way to add money to your account. However, there are limits on the amount you can deposit each day and month. The daily limit is $5,000, and the monthly limit is $10,000. If you exceed these limits, you may be charged a fee.

    Avoiding Fees

    There are a few strategies you can use to avoid fees when adding money to your Chime card:

    • Use direct deposit: Setting up direct deposit from your employer or other sources is free and eliminates the need for other deposit methods.
    • Use the Chime SpotMe feature: Chime offers a SpotMe feature that allows you to overdraft your account up to $200 without paying fees. This can be helpful for covering small expenses or unexpected costs.
    • Consider other methods: If you have a bank account with another institution, you can transfer money to your Chime card using ACH transfer. This method is typically free, but it may take a few days for the funds to appear in your account.

    Security Measures for Chime Card Transactions: Add Money To Chime Card

    Chime implements a comprehensive suite of security measures to safeguard user funds during transactions, ensuring the protection of sensitive financial data.

    Encryption Methods:Chime employs industry-standard encryption protocols, such as 256-bit SSL encryption, to encrypt all data transmitted between users and Chime servers. This encryption scrambles data, making it unreadable to unauthorized parties, even if intercepted.

    Fraud Detection Systems

    Chime utilizes advanced fraud detection systems that monitor transactions in real-time, identifying suspicious patterns and potential fraudulent activity. These systems analyze factors such as transaction amounts, locations, and device usage to detect anomalies and prevent unauthorized access to user accounts.

    Additional Safeguards

    • Multi-Factor Authentication:Chime requires users to verify their identity through multiple factors, such as a password and a one-time code sent via SMS, before completing transactions.
    • Transaction Limits:Chime sets limits on the amount of money that can be added to a Chime card at a time, helping to mitigate the impact of potential fraud.
    • Dispute Resolution Process:Chime provides a dedicated dispute resolution process for users to report unauthorized transactions and seek reimbursement for lost funds.

    Tips for Enhancing Security

    • Use Strong Passwords:Create unique and complex passwords that are difficult to guess or crack.
    • Enable Two-Factor Authentication:Activate two-factor authentication to add an extra layer of security to your account.
    • Monitor Transactions Regularly:Review your transaction history frequently to identify any unauthorized activity.
    • Report Suspicious Activity:Contact Chime immediately if you suspect any fraudulent activity on your account.

    Comparison of Chime Card to Other Prepaid Cards

    Chime card stands out among prepaid cards with its competitive features and benefits. However, it’s essential to compare it to other popular options to make an informed decision.

    Features and Benefits, Add money to chime card

    Chime card offers a range of features, including fee-free transactions, early paycheck access, and mobile app-based money management tools. Other prepaid cards may provide similar features, but the details and limitations can vary.

    Fees

    Fees associated with prepaid cards can significantly impact their overall value. Chime card charges no monthly maintenance fees, but other cards may impose such fees. Additionally, transaction fees, ATM withdrawal fees, and other charges should be considered when comparing cards.

    Accessibility

    Accessibility refers to the ease of obtaining and using a prepaid card. Chime card is widely available and can be obtained online or through retail partners. Other prepaid cards may have different distribution channels and may not be as accessible.

    Customer Support

    Reliable customer support is crucial for resolving issues and managing account-related queries. Chime card offers 24/7 customer support via phone, email, and live chat. Other prepaid cards may have varying levels of customer support, which should be taken into account.

    Key Differences Between Chime Card and Competitors
    Feature Chime Card Competitor A Competitor B
    Monthly Maintenance Fee $0 $5 $10
    Transaction Fees None $0.50 per transaction $1 per transaction
    ATM Withdrawal Fees $2.50 (out-of-network) $3 (out-of-network) $4 (out-of-network)
    Early Paycheck Access Yes Yes No
    Mobile App Features Budgeting tools, spending insights Basic account management Advanced financial planning tools
    Customer Support 24/7 via phone, email, live chat Limited hours via phone, email Live chat only during business hours

    Ultimately, the best prepaid card for an individual depends on their specific needs and preferences. By comparing the features, benefits, and limitations of different options, including Chime card and its competitors, consumers can make an informed decision that aligns with their financial goals.

    Summary

    Chime routing banking delete unlink

    Whether you’re navigating fees associated with Chime card transactions or exploring security measures to safeguard your funds, this comprehensive guide has you covered. Discover the intricacies of Chime card usage, empowering you to make informed decisions and maximize its benefits.

    Embrace financial freedom with Chime card, your trusted companion in financial empowerment.

    Essential FAQs

    What is the easiest way to add money to my Chime card?

    Direct deposit is the most convenient method, allowing you to have your paycheck or other payments deposited directly into your Chime account.

    Can I add cash to my Chime card?

    Yes, you can add cash to your Chime card at participating retail locations. However, a fee may be associated with this service.

    How do I set up mobile check deposit on my Chime app?

    Within the Chime app, navigate to the ‘Deposit Checks’ section and follow the on-screen instructions to capture and submit your check for deposit.

  • Best BOP Insurance: Comprehensive Coverage for Your Business

    Best BOP Insurance: Comprehensive Coverage for Your Business

    Best BOP insurance takes center stage in this informative guide, offering an immersive journey into the world of business insurance. With captivating details and vivid descriptions, this article unveils the intricacies of BOP policies, empowering business owners to make informed decisions about their risk management strategies.

    As we delve into the heart of this topic, we will explore the diverse coverage options available, uncovering the benefits and limitations of each policy. We will also shed light on the key features that enhance protection and provide practical tips for reducing insurance costs.

    Coverage Comparison

    Different BOP insurance policies provide varying coverage limits and exclusions. Understanding these differences helps businesses choose the most suitable policy for their specific needs.

    Commonly covered risks include property damage, business interruption, liability, and employee dishonesty. Exclusions may include acts of war, terrorism, or certain types of pollution.

    Coverage Limits

    • Property Damage:Typically covers damage or loss to buildings, equipment, inventory, and other business property.
    • Business Interruption:Provides coverage for lost income and expenses incurred due to a covered event that disrupts business operations.
    • Liability:Protects against legal claims arising from bodily injury or property damage caused by the business or its employees.
    • Employee Dishonesty:Covers losses resulting from theft, embezzlement, or other dishonest acts by employees.

    Coverage Exclusions

    • Acts of War:Damage or loss caused by acts of war, terrorism, or civil unrest are typically excluded.
    • Pollution:Environmental damage or pollution caused by the business’s operations may not be covered.
    • Intentional Acts:Damage or loss resulting from intentional or criminal acts by the business owner or employees is often excluded.
    Coverage Comparison Table
    Coverage Policy A Policy B Policy C
    Property Damage Up to $1 million Up to $2 million Up to $5 million
    Business Interruption Up to 12 months Up to 24 months Up to 36 months
    Liability $1 million per occurrence $2 million per occurrence $5 million per occurrence
    Employee Dishonesty Up to $100,000 Up to $250,000 Up to $500,000

    Policy Features and Benefits: Best Bop Insurance

    Best bop insurance

    Business owners’ policies (BOPs) provide a comprehensive suite of coverage options tailored to the specific needs of businesses. Beyond the core coverages, various additional features and benefits can enhance risk management and provide comprehensive protection.

    These features can help businesses mitigate risks, reduce financial burdens, and ensure business continuity in the face of unforeseen events.

    Loss Control Services

    • Risk assessment and safety inspections to identify and address potential hazards.
    • Training and resources to enhance employee safety and prevent accidents.
    • Development of customized loss control plans to minimize the likelihood and severity of losses.

    Business Income Coverage

    • Provides coverage for lost income and expenses resulting from a covered loss, such as a fire or natural disaster.
    • Helps businesses maintain financial stability during periods of disruption.
    • Allows businesses to continue operations and meet ongoing expenses, such as rent, payroll, and utilities.

    Cyber Liability Coverage

    • Protects businesses from financial and reputational risks associated with data breaches, cyber attacks, and privacy violations.
    • Covers costs such as legal defense, notification expenses, and credit monitoring.
    • Helps businesses mitigate the impact of cyber threats and maintain customer trust.

    Cost and Affordability

    Postmates bop coverages entrecourier

    BOP insurance policies vary in cost, depending on several factors. Understanding these factors and implementing cost-saving strategies can help businesses optimize their insurance coverage while minimizing premiums.

    The cost of BOP insurance is primarily determined by the business’s risk profile, which includes factors such as industry, size, and location. Higher-risk businesses, such as those operating in hazardous environments or with a history of claims, typically pay higher premiums.

    Factors Affecting Premiums

    • Business Size:Larger businesses generally face higher premiums due to increased exposure to risks and potential liabilities.
    • Industry:Certain industries, such as construction and manufacturing, have higher inherent risks, leading to higher insurance costs.
    • Risk Profile:Businesses with a history of accidents, claims, or legal issues may face higher premiums as insurers perceive them as higher-risk.
    • Location:Businesses located in areas prone to natural disasters or with high crime rates may pay higher premiums due to increased risk exposure.
    • Deductible:Choosing a higher deductible can lower premiums, but it also means the business will be responsible for a larger portion of claims.

    Tips for Reducing Insurance Costs

    • Implement Risk Management Practices:Establishing and maintaining robust risk management protocols can demonstrate to insurers that the business is proactive in mitigating risks, potentially leading to lower premiums.
    • Shop Around and Compare Quotes:Obtaining quotes from multiple insurance providers allows businesses to compare coverage options and premiums, ensuring they secure the best value for their needs.
    • Negotiate Premiums:Businesses can negotiate with insurers to obtain more favorable premium rates, especially if they have a good claims history or implement risk management measures.
    • Consider Bundling Policies:Bundling BOP insurance with other business insurance policies, such as workers’ compensation or commercial auto insurance, can often result in premium discounts.
    • Maintain Good Credit:Businesses with strong credit ratings are perceived as lower-risk by insurers, which can lead to lower premiums.

    Carrier Reputation and Financial Stability

    Best bop insurance

    Choosing a reliable insurance carrier is crucial for your business’s financial security. A reputable carrier will have a proven track record of providing quality coverage, excellent customer service, and fair claim settlements. Conversely, a financially unstable carrier may struggle to pay claims, leaving you vulnerable to financial losses.

    To assess a carrier’s reputation and financial stability, consider the following factors:

    Ratings from Independent Agencies

    • A.M. Best:A leading insurance rating agency that evaluates carriers’ financial strength and ability to meet their obligations.
    • Standard & Poor’s:Another reputable rating agency that assesses carriers’ creditworthiness and claims-paying ability.
    • Moody’s:Provides financial ratings for insurance companies based on their financial strength and stability.

    Look for carriers with consistently high ratings from these agencies, indicating financial stability and a strong reputation.

    Financial Statements

    Review the carrier’s financial statements to assess their financial health. Look for indicators of strong financial performance, such as:

    • High surplus
    • Low debt-to-equity ratio
    • Positive cash flow

    A financially sound carrier will have ample reserves to cover potential claims and maintain its operations.

    Consumer Reviews and Complaints

    Check online reviews and complaint databases to gather insights into the carrier’s customer service and claims handling practices. Positive reviews and a low number of complaints indicate a carrier that is responsive to customers’ needs and fair in resolving claims.

    Reputable Insurance Carriers

    Based on these criteria, here are some reputable insurance carriers offering BOP insurance:

    • Travelers
    • Chubb
    • Hartford
    • Liberty Mutual
    • Progressive

    Customer Service and Claims Handling

    Exceptional customer service and efficient claims handling are crucial for any business insurance policy. When a claim arises, you need a provider who will respond quickly, guide you through the process, and ensure a fair and timely settlement.

    Here are some key factors to consider when evaluating the customer service and claims handling of BOP insurance providers:

    Responsiveness and Efficiency

    • Look for providers with dedicated claims hotlines or online portals that allow you to report claims 24/7.
    • Inquire about average response times and claim settlement timelines to ensure prompt attention to your needs.
    • Consider providers that offer mobile apps or online tools for easy claim submission and tracking.

    Expertise and Guidance

    • Choose providers with experienced claims adjusters who can provide expert advice and support throughout the claims process.
    • Look for companies that offer proactive communication and regular updates on the status of your claim.
    • Consider providers that provide educational resources or workshops to help you understand the claims process and your coverage.

    Fair and Equitable Settlements, Best bop insurance

    • Ensure that the provider has a fair claims settlement history and a reputation for honoring valid claims.
    • Read reviews and testimonials from other businesses to gauge their satisfaction with the claims handling process.
    • Consider providers that offer mediation or arbitration services to resolve disputes amicably.

    Exceptional Customer Service Practices

    • Look for providers that go the extra mile to provide exceptional customer service, such as personalized attention and tailored solutions.
    • Consider providers that offer additional support services, such as risk management consulting or loss prevention programs.
    • Choose providers that demonstrate a genuine commitment to customer satisfaction and building long-term relationships.

    Final Summary

    In conclusion, best BOP insurance is a cornerstone of sound business management, providing a comprehensive safety net against unforeseen risks. By understanding the nuances of coverage, leveraging valuable policy features, and partnering with reputable carriers, businesses can safeguard their operations and ensure their long-term success.

    Top FAQs

    What is the primary purpose of BOP insurance?

    BOP insurance offers comprehensive coverage for businesses, combining property and liability protection in a single policy.

    What are some common exclusions in BOP policies?

    Exclusions may vary depending on the policy, but common ones include flood damage, workers’ compensation, and certain professional liability risks.

    How can I reduce the cost of my BOP insurance?

    Factors like increasing deductibles, implementing risk management measures, and bundling policies can help lower insurance premiums.

  • ACH Instant Transfer: A Fast and Convenient Payment Option

    ACH Instant Transfer: A Fast and Convenient Payment Option

    ACH instant transfer is a revolutionary payment system that enables businesses and individuals to send and receive funds instantly. Unlike traditional ACH transfers that can take days to process, ACH instant transfers are completed within seconds, making them an ideal solution for time-sensitive transactions.

    This innovative payment method offers numerous benefits, including faster access to funds, reduced processing times, and enhanced security. ACH instant transfers are widely used in various industries, such as e-commerce, healthcare, and government payments.

    ACH Instant Transfer

    ACH Instant Transfer is a payment system that allows for the near-instantaneous transfer of funds between bank accounts. It is a faster alternative to traditional ACH transfers, which can take several days to complete. ACH Instant Transfer is available 24/7, and it can be used to send and receive payments of up to $25,000.

    Benefits of ACH Instant Transfer

    There are many benefits to using ACH Instant Transfer, including:

    • Speed: ACH Instant Transfer is much faster than traditional ACH transfers, which can take several days to complete. With ACH Instant Transfer, funds are typically available within minutes.
    • Convenience: ACH Instant Transfer is available 24/7, and it can be used to send and receive payments from anywhere in the United States.
    • Security: ACH Instant Transfer is a secure payment system that uses the same security measures as traditional ACH transfers.
    • Cost-effective: ACH Instant Transfer is a cost-effective way to send and receive payments. The fees are typically lower than the fees for wire transfers.

    Limitations of ACH Instant Transfer

    There are also some limitations to using ACH Instant Transfer, including:

    • Transfer Limit: The maximum amount that can be transferred using ACH Instant Transfer is $25,000.
    • Not all banks offer ACH Instant Transfer: Not all banks offer ACH Instant Transfer. If your bank does not offer ACH Instant Transfer, you will not be able to use this service.
    • Fees: There may be fees associated with using ACH Instant Transfer. The fees will vary depending on the bank that you use.

    Examples of ACH Instant Transfer

    ACH Instant Transfer can be used in a variety of industries, including:

    • Retail: ACH Instant Transfer can be used to make purchases online or in-store.
    • Healthcare: ACH Instant Transfer can be used to pay for medical bills.
    • Government: ACH Instant Transfer can be used to pay taxes or receive government benefits.
    • Payroll: ACH Instant Transfer can be used to pay employees.

    How ACH Instant Transfer Works

    ACH instant transfer is a new type of electronic payment that allows you to send and receive money instantly. It’s similar to a wire transfer, but it’s faster and cheaper. ACH instant transfers are processed through the ACH network, which is a network of banks and credit unions that allows for the electronic transfer of funds.

    To initiate an ACH instant transfer, you’ll need to provide your bank account information and the recipient’s bank account information. You can do this online, through your bank’s mobile app, or by phone. Once you’ve provided the necessary information, your bank will send the transfer request to the ACH network.

    The ACH network will then process the transfer request and send the funds to the recipient’s bank account. The entire process usually takes less than a minute. In some cases, it may take a few hours for the funds to appear in the recipient’s account.

    Security Measures

    ACH instant transfers are protected by a number of security measures, including:

    • Encryption: All ACH instant transfers are encrypted to protect them from unauthorized access.
    • Authentication: You must authenticate yourself before you can initiate an ACH instant transfer. This is typically done through a password or PIN.
    • Fraud monitoring: ACH instant transfers are monitored for fraud. If any suspicious activity is detected, the transfer will be blocked.

    Comparison of ACH Instant Transfer with Other Payment Methods

    Ach instant transfer

    ACH instant transfer stands out among various payment methods due to its unique features and advantages. Let’s compare it with other commonly used payment methods to highlight its strengths and weaknesses.

    Wire Transfers

    Wire transfers are electronic transfers of funds between bank accounts. They are typically processed within one to three business days and incur a fee. While wire transfers are secure and reliable, they can be slow and expensive compared to ACH instant transfers.

    Credit Cards

    Credit cards allow users to make purchases or withdraw cash using a line of credit provided by a bank or financial institution. Credit cards offer convenience and flexibility but come with interest charges and potential fees. Additionally, credit card transactions may take several days to settle.

    Debit Cards, Ach instant transfer

    Debit cards are linked directly to a bank account and deduct funds directly from the account balance when making purchases or withdrawals. Debit cards are convenient and widely accepted, but they may not offer the same level of protection as credit cards in case of fraudulent transactions.

    Choosing the Most Appropriate Payment Method

    The choice of payment method depends on several factors, including the speed of transfer, cost, security, and convenience. ACH instant transfer is ideal for situations where speed and low cost are crucial, such as urgent bill payments or quick transfers between individuals.

    Wire transfers are suitable for large-value transactions or international payments where security and reliability are paramount. Credit cards are convenient for everyday purchases and online transactions but should be used responsibly to avoid debt accumulation.

    Debit cards are a good option for managing daily expenses and accessing cash quickly. However, they may not be suitable for large purchases or transactions where additional protection is desired.

    Implementation of ACH Instant Transfer

    Ach instant transfer

    Implementing ACH instant transfer requires businesses and individuals to fulfill specific technical requirements and adhere to best practices to ensure seamless integration and effective utilization.

    Technical Requirements

    To implement ACH instant transfer, businesses and individuals must meet the following technical requirements:

    • Secure connection:Establish a secure connection to the ACH network, typically via an ACH processor or financial institution.
    • Message format compliance:Ensure that all ACH messages adhere to the NACHA ACH Instant Transfer Operating Rules.
    • Fraud prevention measures:Implement robust fraud prevention measures, such as strong authentication and risk monitoring.
    • Integration with accounting systems:Integrate ACH instant transfer functionality with existing accounting systems to streamline reconciliation and reporting.

    Costs

    The costs associated with implementing ACH instant transfer vary depending on factors such as the volume of transactions, the ACH processor or financial institution used, and any additional services required.

    • Transaction fees:ACH instant transfer transactions typically incur a per-transaction fee, which may vary based on the processor or institution.
    • Setup fees:Some ACH processors or financial institutions may charge a one-time setup fee for enabling ACH instant transfer services.
    • Monthly fees:Ongoing monthly fees may apply for maintaining access to ACH instant transfer services.

    Best Practices

    To use ACH instant transfer effectively, businesses and individuals should adhere to the following best practices:

    • Verify recipient information:Carefully verify the recipient’s account and routing numbers to ensure accurate and timely delivery of funds.
    • Use for eligible transactions:Utilize ACH instant transfer for eligible transactions, such as time-sensitive payments or transactions requiring immediate settlement.
    • Monitor transactions:Regularly monitor ACH instant transfer transactions to identify any potential issues or fraudulent activity.

    Future of ACH Instant Transfer

    The advent of ACH Instant Transfer has revolutionized the financial industry, and its potential impact continues to grow. As technology advances and consumer demand for faster, more convenient payment options increases, ACH Instant Transfer is poised to play an increasingly significant role in the payments ecosystem.

    Emerging Trends and Innovations

    The future of ACH Instant Transfer lies in ongoing innovation and the adoption of emerging technologies. These include:

    • Enhanced Security Measures:To ensure the safety and security of transactions, ACH Instant Transfer providers are continuously implementing advanced security measures such as biometrics, tokenization, and fraud detection systems.
    • Expansion of Use Cases:ACH Instant Transfer is expanding beyond traditional peer-to-peer payments into new areas such as e-commerce, payroll, and government disbursements.
    • Integration with Mobile Wallets:The integration of ACH Instant Transfer with mobile wallets provides users with a convenient and seamless way to make instant payments on the go.
    • Open Banking Initiatives:Open banking initiatives are enabling third-party providers to access customer account data, which could facilitate the development of new ACH Instant Transfer services and products.

    Speculation on the Future

    As ACH Instant Transfer technology continues to evolve, it is likely to have a profound impact on the financial industry. Some potential future developments include:

    • Universal Adoption:ACH Instant Transfer could become the default payment method for a wide range of transactions, replacing traditional methods such as checks and wire transfers.
    • Real-Time Settlement:Advancements in technology could enable real-time settlement of ACH Instant Transfer payments, providing businesses and consumers with immediate access to funds.
    • Cross-Border Payments:ACH Instant Transfer could be extended to facilitate cross-border payments, offering faster and more cost-effective options for international transactions.
    • Integration with Artificial Intelligence (AI):AI could be used to optimize ACH Instant Transfer processes, such as fraud detection and payment routing, improving efficiency and reducing costs.

    In conclusion, ACH Instant Transfer is a rapidly evolving technology with the potential to transform the payments landscape. As it continues to gain traction and integrate with emerging technologies, ACH Instant Transfer is poised to play an increasingly significant role in the future of the financial industry.

    Conclusive Thoughts

    Ach funds

    ACH instant transfer is transforming the financial industry by providing a fast, convenient, and secure way to transfer funds. As technology continues to advance, we can expect to see even more innovative applications of ACH instant transfer in the future.

    Essential FAQs

    What is the difference between ACH instant transfer and traditional ACH transfer?

    Traditional ACH transfers typically take 1-3 business days to process, while ACH instant transfers are completed within seconds.

    Are ACH instant transfers secure?

    Yes, ACH instant transfers are secure and protected by multiple layers of security measures, including encryption and fraud monitoring.

    What are the benefits of using ACH instant transfer?

    ACH instant transfer offers faster access to funds, reduced processing times, enhanced security, and lower transaction fees compared to other payment methods.